
Palantir Technologies (NASDAQ:PLTR) reports bullish Q3 2026, full-year sales guidance is optimistic
Data analytics company Palantir Technologies (NASDAQ:PLTR) reported revenue ahead of Wall Street’s expectations in Q3 2026, as revenue rose 95.9% year on year to $2.31 billion. In addition, next quarter’s revenue guidance ($2.65 billion at the midpoint) was surprisingly strong, coming in 7.6% above analysts’ consensus estimates. Its non-GAAP profit of $0.44 per share was 8.1% above analysts’ consensus estimates.
For more on Palantir Technologies, read our free full research report.
Palantir Technologies (PLTR) Q3 2026 highlights:
- Revenue $2.31 billion vs S&P analysts’ consensus estimates of $2.18 billion (95.9% year-on-year growth, 5.9% beat)
- Adjusted EPS $0.44 vs S&P analysts’ consensus estimates of $0.41 (8.1% beat)
- Adjusted EBITDA $1.43 billion vs analysts’ consensus estimates of $1.34 billion (62% margin, 6.6% beat)
- Revenue guidance $2.65 billion at the midpoint for Q4 2026, above analysts’ consensus estimates of $2.46 billion
- Operating margin 46.9%, up from 33.3% in the same quarter last year
- Free cash flow margin 52.6%, down from 63.1% in the previous quarter
- Market capitalization $442.4 billion
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Palantir Technologies’s revenue grew at a strong 38.5% compounded annual growth rate over the last five years. Its growth surpassed the average software company and shows its offerings resonate with customers.
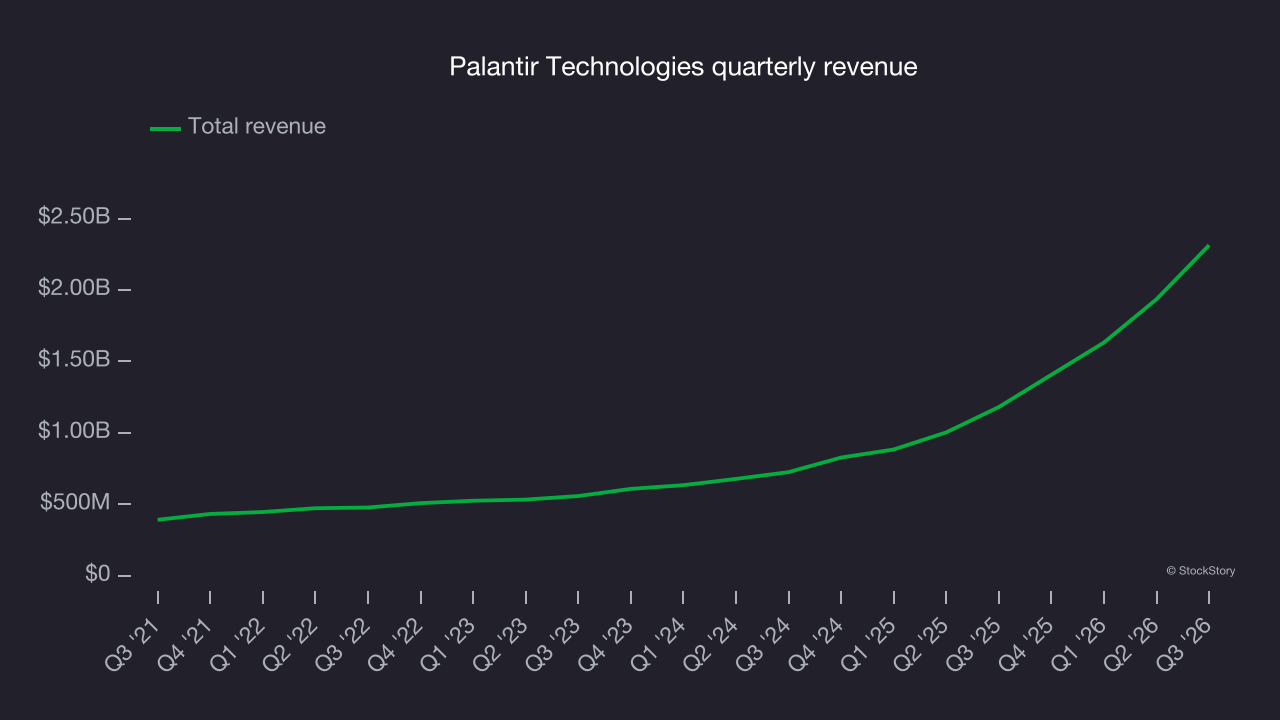
Long-term growth matters most, but within software, a half-decade historical view may miss recent innovations or disruptive industry trends. Palantir Technologies’s annualized revenue growth of 66% over the last two years is above its five-year trend, suggesting demand was strong and recently accelerated. 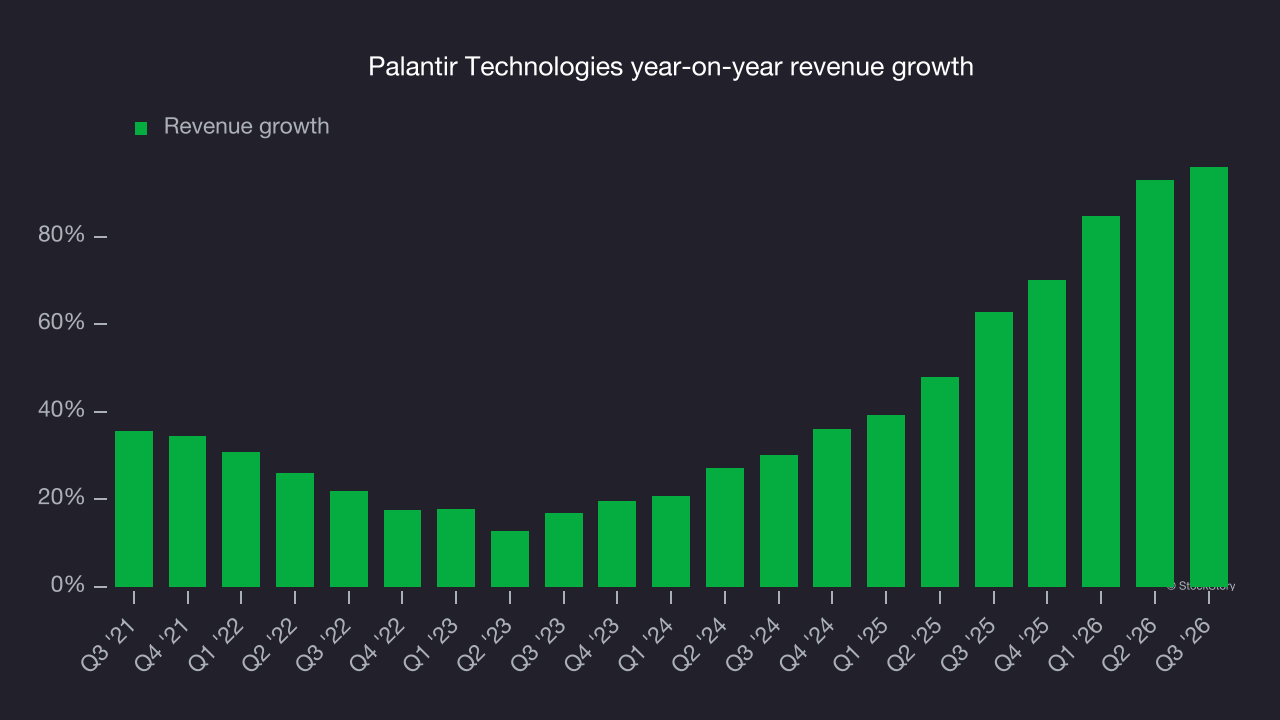
This quarter, Palantir Technologies reported year-on-year revenue growth of 95.9%, and its $2.31 billion of revenue beat Wall Street’s consensus estimates by 5.9%. Management is currently guiding for an 88.4% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 54.8% over the next 12 months, according to S&P, a deceleration versus the last two years. Despite the slowdown, this projection is strong and implies the market is pricing in success for its products and services.
Customer acquisition efficiency
The customer acquisition cost (CAC) payback period measures the months a company needs to recoup the money spent on acquiring a new customer. This metric helps assess how quickly a business can break even on its sales and marketing investments.
Palantir Technologies is efficient at acquiring new customers, and its CAC payback period was 4 months this quarter. The company’s rapid recovery of its customer acquisition costs indicates it has a highly differentiated product offering and a strong brand reputation. These dynamics give Palantir Technologies more resources to pursue new product initiatives while maintaining the flexibility to increase its sales and marketing investments.
Key takeaways from Palantir Technologies’s Q3 results
Palantir Technologies delivered a solid quarter: Adjusted operating income came in well above analysts’ consensus estimates, and its revenue guidance for next quarter also topped Wall Street’s consensus. Shares remained flat at $179.78 immediately after the results.
Palantir Technologies had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. That decision calls for a broader look at valuation, business quality and the latest earnings. For more on Palantir Technologies, read our full research report here (it’s free).