
Ibotta (NYSE:IBTA) reports bullish Q3 2026, stock jumps 12.5%
Cash-back rewards platform Ibotta (NYSE:IBTA) announced better-than-expected revenue in Q3 2026, with revenue up 17.5% year on year to $97.83 million. Revenue guidance for next quarter came in at $96 million at the midpoint, 3% above analysts’ consensus estimates. Its non-GAAP profit of $0.62 per share was 40.4% above analysts’ consensus estimates.
For more on Ibotta, read our full research report for free.
Ibotta (IBTA) Q3 2026 highlights:
- Revenue $97.83 million vs S&P analysts’ consensus estimates of $88.72 million (17.5% year-on-year growth, 10.3% beat)
- Adjusted EPS $0.62 vs S&P analysts’ consensus estimates of $0.44 (40.4% beat)
- Adjusted EBITDA $23.8 million vs analysts’ consensus estimates of $13.56 million (24.3% margin, 75.5% beat)
- Revenue guidance $96 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $93.23 million
- EBITDA guidance $16 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $13.81 million
- Operating margin 4.8%, up from 2.8% in the same quarter last year
- Free cash flow margin 17.2%, up from 12.7% in the same quarter last year
- Total redemptions increased by 35.48 million year on year
- Market capitalization $1.13 billion
“We delivered accelerating revenue growth in the third quarter, with revenue up 17% and Adjusted EBITDA up 43% year-over-year, both exceeding our expectations,” said Ibotta CEO and founder Bryan Leach. “Redemption revenue grew 23% and our redeemer base grew 30% to 23.6 million, a direct outcome of improving advertiser offer supply, consistently strong execution by our team, and significant consumer demand for value.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years.
With $357.7 million in revenue over the past 12 months, Ibotta is a small player in the business services space, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and numerous distribution channels. On the positive side, it can grow faster because it has more room to expand.
Ibotta grew its revenue at a strong 16.8% compounded annual growth rate over the last four years. This shows it had high demand.
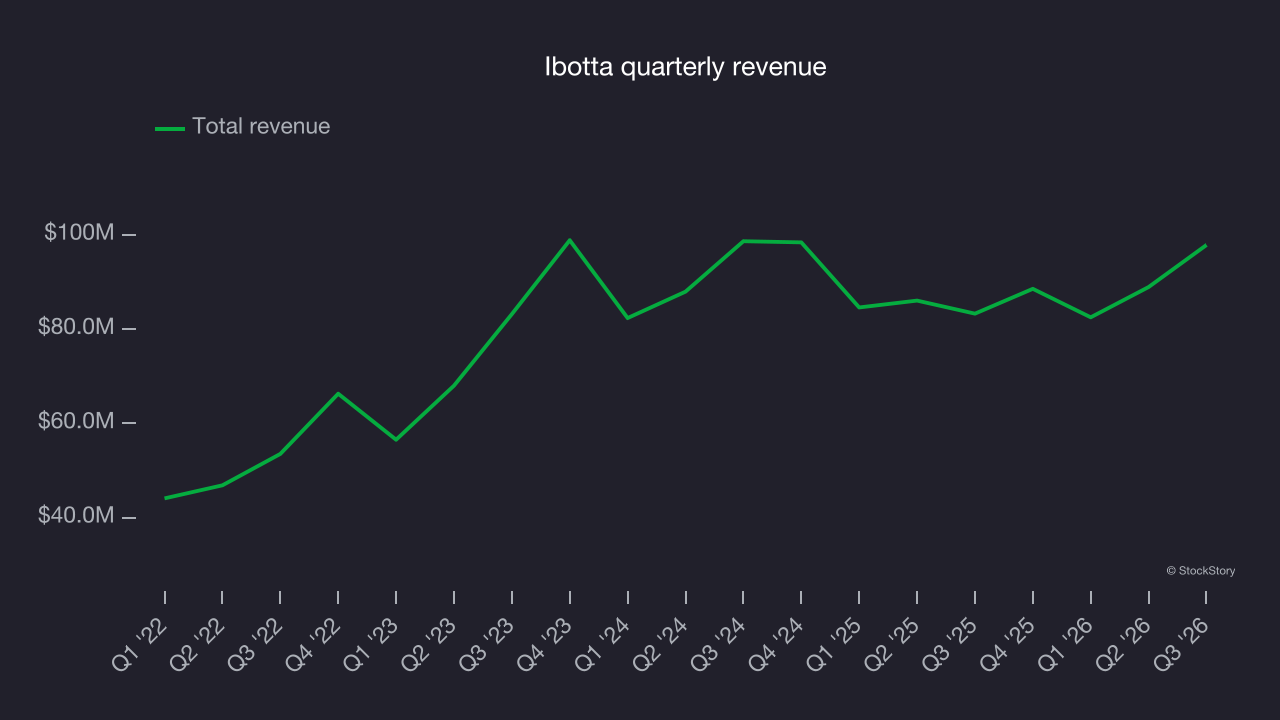
Long-term growth is the most important, but within business services, a stretched historical view may miss new innovations or demand cycles. Ibotta’s recent performance marks a sharp pivot from its four-year trend as its revenue has shown annualized declines of 1.4% over the last two years. 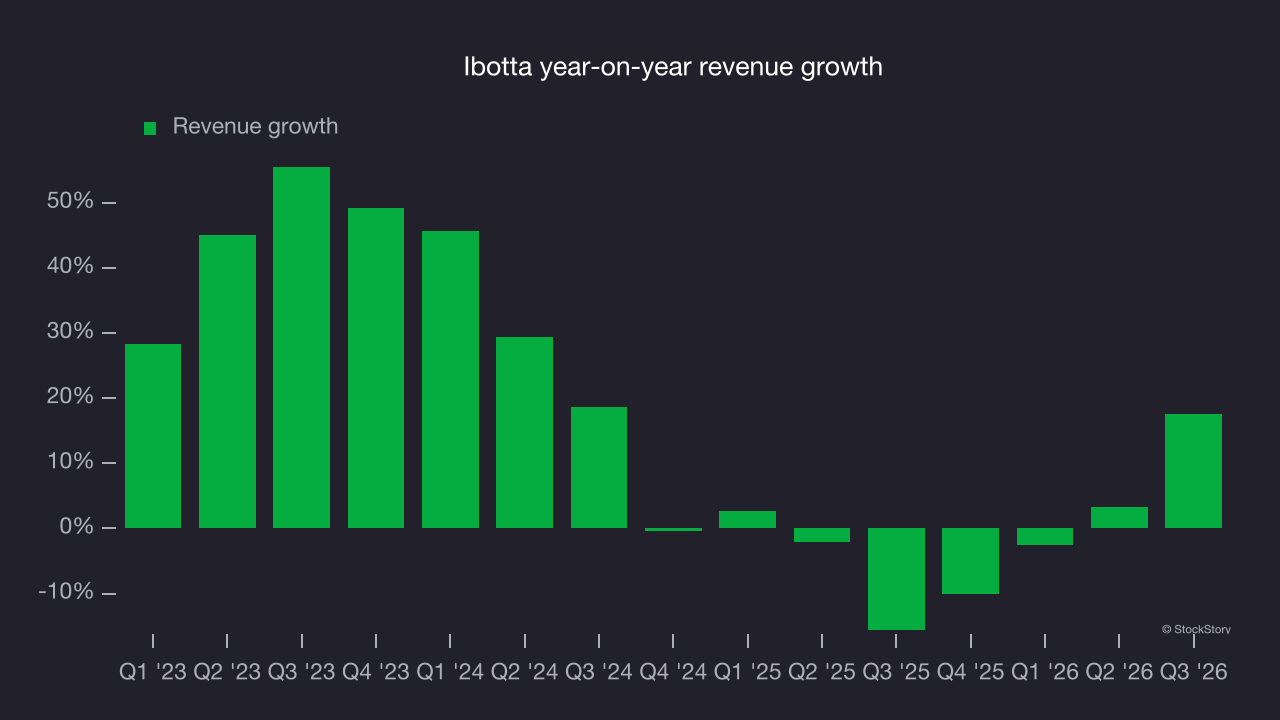
This quarter, Ibotta reported year-on-year revenue growth of 17.5%, and its $97.83 million of revenue exceeded Wall Street’s consensus estimates by 10.3%. Company management is currently guiding for an 8.4% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 4.8% over the next 12 months, according to S&P. Although this projection suggests its newer products and services will catalyze better top-line performance, it is still below the sector average.
Adjusted operating margin
Ibotta has been an efficient company over the last five years. It was one of the more profitable businesses in the business services sector, with an average adjusted operating margin of 16.3%.
Looking at the trend in its profitability, Ibotta’s adjusted operating margin rose by 40.6 percentage points over the last five years, as its revenue growth provided substantial operating leverage.
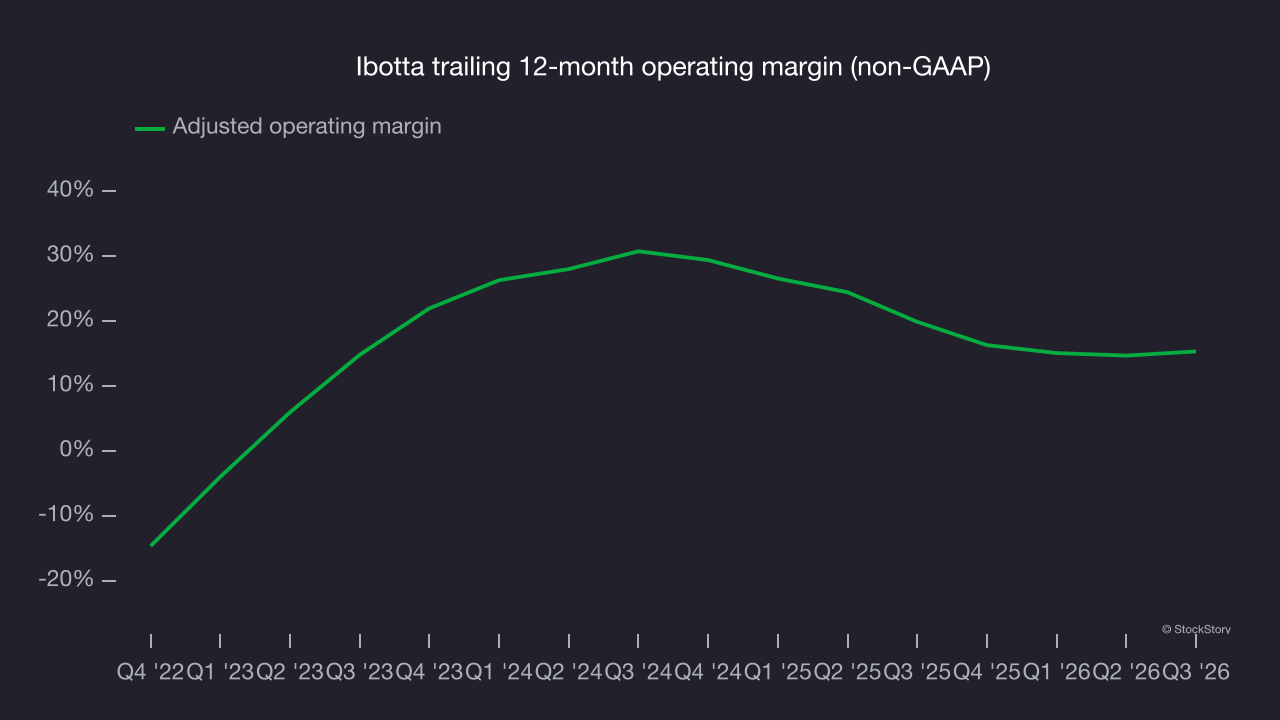
This quarter, Ibotta generated an adjusted operating margin of 20.5%, up 1.8 percentage points year on year. This increase was a positive development and shows it was more efficient.
Free cash flow
Earnings are valuable for assessing company performance, but cash flow matters because accounting profits can’t pay the bills.
Ibotta has shown strong cash profitability, giving it an edge over its competitors and the ability to reinvest or return capital to investors. The company’s free cash flow margin averaged 11.1% over the last five years, an impressive level for a business services company.
Ibotta’s margin expanded by 49 percentage points during that time. That improvement is a positive sign and indicates it became a less capital-intensive business, as its free cash flow profitability rose more than its operating profitability.
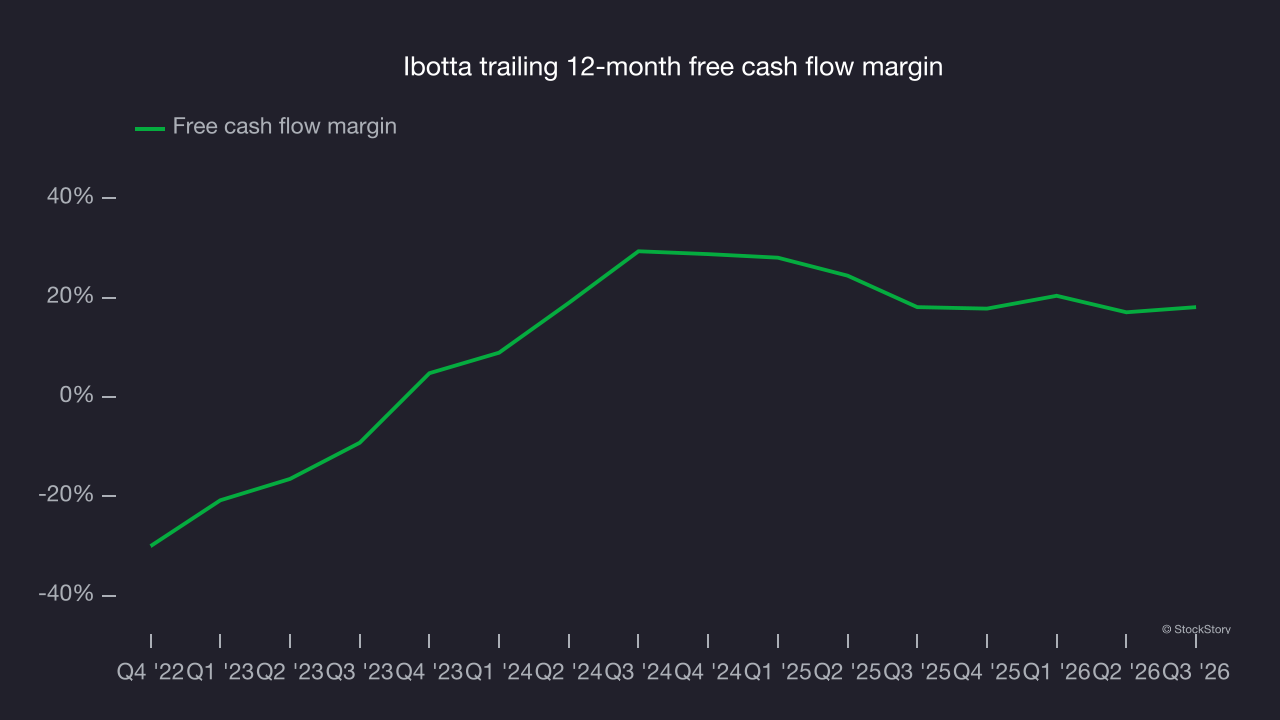
Ibotta’s free cash flow came in at $16.78 million in Q3, equivalent to a 17.2% margin. This was a good result, as its margin was 4.4 percentage points higher than in the same quarter last year, building on its favorable historical trend.
Key takeaways from Ibotta’s Q3 results
Ibotta’s wide revenue beat and EPS above analysts’ consensus estimates made for a strong third quarter with clear positives. Shares soared 12.5% to $56.35 immediately after the report.
Ibotta had a positive quarter, but one earnings result doesn’t necessarily make the stock a buy. The latest quarter matters, but not nearly as much as longer-term fundamentals and valuation when deciding whether to invest. For more on Ibotta, read our full research report here (it’s free).