
How Lung Cancer Trial Wins Will Impact Hutchmed Shares
- HUTCHMED (China) reported that ORPATHYS (savolitinib) plus TAGRISSO (osimertinib) delivered positive Phase III results in EGFR-mutated non-small cell lung cancer, with statistically significant improvements in progression-free and overall survival versus platinum chemotherapy and versus TAGRISSO alone in separate trials.
- The all oral, chemotherapy free combination targeting EGFR and MET addresses a defined resistance mechanism. This could reshape how HUTCHMED structures its oncology portfolio, allocates R&D spend, and positions ORPATHYS alongside global partners like AstraZeneca in both first-line and post-progression lung cancer settings.
- We will now look at how HUTCHMED's investment narrative could be affected by the strong survival data from the SAFFRON trial.
HUTCHMED (China) Investment Narrative Recap
To own HUTCHMED (China), you need to believe its targeted oncology portfolio can turn strong trial readouts into durable, reimbursed prescriptions across China and international markets while managing heavy R&D spend. The SAFFRON and SANOVO data sharpen that thesis around savolitinib plus TAGRISSO in EGFRm NSCLC with MET alterations, but execution on filings and label expansions still matters.
In the near term, the key catalyst is how quickly regulators and payers convert this survival data into broader use in both post TAGRISSO and first line settings. The biggest risk remains concentration in a few lead oncology assets, in markets where pricing pressure, China policy shifts and global competitive MET TKIs can still squeeze volumes and margins.
The recent GSK agreement around HMPL A830 is highly relevant when thinking about catalysts alongside the SAFFRON and SANOVO news. HUTCHMED expects a US$110 million upfront payment and may receive up to US$1.185b in milestones plus tiered royalties, which provides another non equity funding source for its sizeable development program.
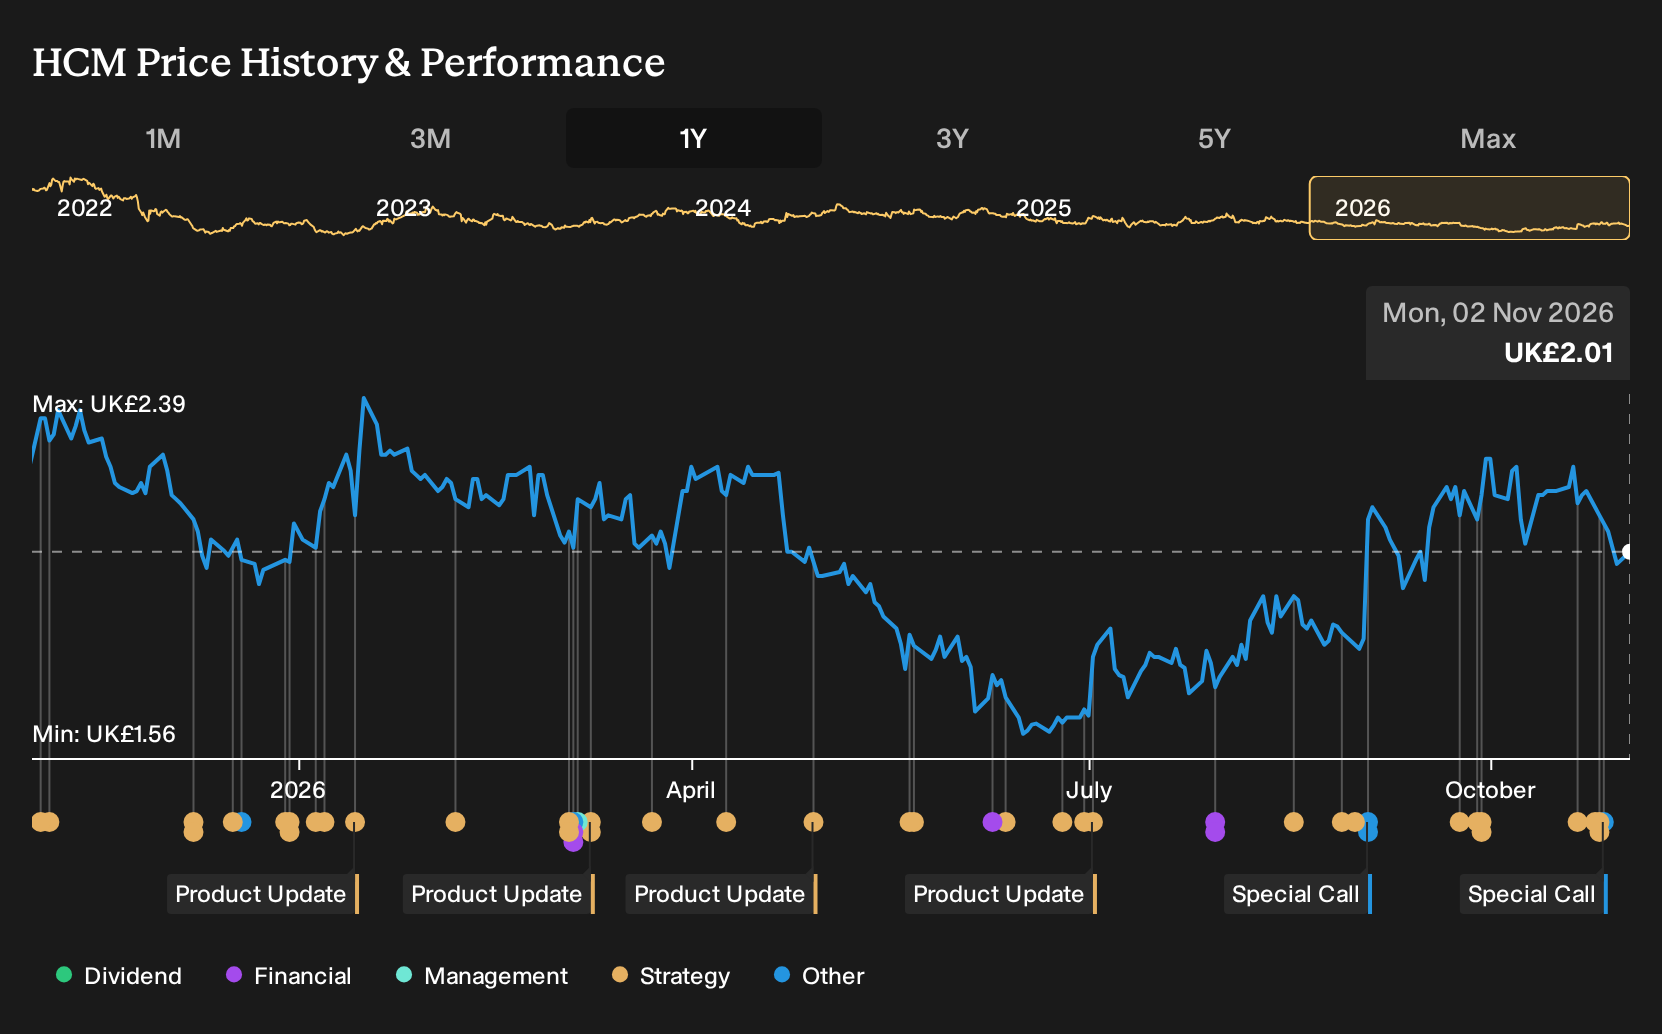
This deal also shows how management is pairing late stage assets such as ORPATHYS with earlier pipeline partnering to share trial and commercialization workload outside China. For you, the operational question is whether these collaborations and new indications can offset concentrated product risk, high R&D outlay and a share price that has lagged both the UK market and European pharma peers over the past year.
HUTCHMED (China)'s current earnings of US$17.9 million are projected by analysts to reach US$116.9 million by 2029. This implies a revenue path that moves toward US$855.4 million and uses a 15.9% yearly revenue growth assumption, which together point to an earnings increase of about US$99 million over that period.
Uncover why HUTCHMED (China)'s fair value indicates a 72% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses squarely on oncology competition. Before this SAFFRON news, the most cautious analysts were only pencilling in revenue of about US$688.2 million and earnings of roughly US$2.5 million by 2029 for HUTCHMED (China). That is a much gloomier path than consensus, so treat this as a reminder that expert opinions can sit far apart and use it as a prompt to compare several narratives for yourself.
Explore another HUTCHMED (China) fair value estimate, including one that suggests it could be worth just £3.46!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your HUTCHMED (China) research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for HUTCHMED (China). The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HUTCHMED (China)'s overall financial health at a glance.
Looking For More Ideas Beyond HUTCHMED (China)?
If you want to cross check HUTCHMED (China) against other opportunities, the Simply Wall St Screener can help you build a shortlist that fits your own risk and return preferences.
- If resilience matters most to you, start with a 4 resilient stocks with low risk scores that have historically shown lower risk scores and steadier fundamentals.
- If value is your priority, scan a 13 high quality undervalued stocks that combine solid balance sheets with quality cash flows.
- If you prefer to hunt for less crowded opportunities, comb through 5 high quality undiscovered gems that still show strong underlying financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com