
Strong Outlook Could Be A Game Changer For Regency Centers Stock (REG)
- Regency Centers reported that its third quarter 2026 results, due on 5 November, are expected to show year over year gains in revenue and funds from operations per share, supported by robust leasing demand, a grocery anchored portfolio and an active development pipeline.
- Management also increased its 2026 same property NOI growth outlook and flagged a higher lease termination fee for the quarter, which could meaningfully influence near term cash generation and reinforce the role of Regency Centers' redevelopment projects in its earnings profile.
- We will now look at how Regency Centers' investment narrative could be influenced by the raised same property NOI growth outlook.
Scan beyond Regency Centers and compare its setup with a curated 4 dividend fortresses that could appeal to investors who care about income and real estate style cash generation.
Regency Centers Investment Narrative Recap
To own Regency Centers, you need to believe in grocery-anchored, necessity-focused retail staying relevant and in the firm continuing to lease its centers effectively at solid spreads. The raised 2026 same property NOI outlook supports that view and signals confidence in the existing portfolio, not just the development pipeline.
The key near-term catalyst is how those higher NOI expectations and leasing trends appear in the 2026 numbers and cash flow, especially given higher interest costs and construction exposure. The biggest risk remains tenant health and project execution. The updated outlook does not remove those pressure points, but it does not materially worsen them either.
The specific update that matters most here is the higher 2026 same property NOI growth outlook combined with management citing a larger lease termination fee in the third quarter. Those two items sit in the area most investors tend to focus on first for a retail REIT: recurring cash generation and occupancy quality.
Higher termination fees can lift funds from operations in the short run but also hint at tenant churn, which readers may want to weigh against commentary on credit metrics and leasing spreads. For Regency Centers, the interaction between this one-off boost, the development program of roughly US$680 to US$700 million, and interest expense will influence how compelling that NOI outlook appears as an ongoing catalyst.
What The 2029 Consensus Implies For Regency Centers
Regency Centers' current analyst framework ties the near term NOI story to a longer dated set of expectations around revenue, profitability and valuation multiples. That bridge matters if you are trying to connect the raised 2026 same property NOI outlook with where earnings and cash generation may sit by the end of the decade.
On the top line, analysts are building in revenue growth of 2.0% each year over the next three years. Forecasts then point to revenues of US$1.8b by 2029, paired with earnings of US$520.5 million and an earnings per share figure of US$2.82. Profit margins are modeled to ease from 32.2% today to 29.1% by that same horizon, which frames the stronger same property NOI outlook as something that has to work against a softer margin profile in the broader model.
The earnings path embedded in this setup is not one directional. Consensus expects earnings to move from US$542.5 million today to US$520.5 million by about October 2029, which is a decline of US$22 million. There is also a wide spread of opinions around that figure, with the more cautious end of the range down at US$394.5 million. When you layer that onto management's commentary on lease termination fees and development returns, you get a picture where higher NOI expectations help offset, but do not eliminate, potential earnings pressure at the headline level.
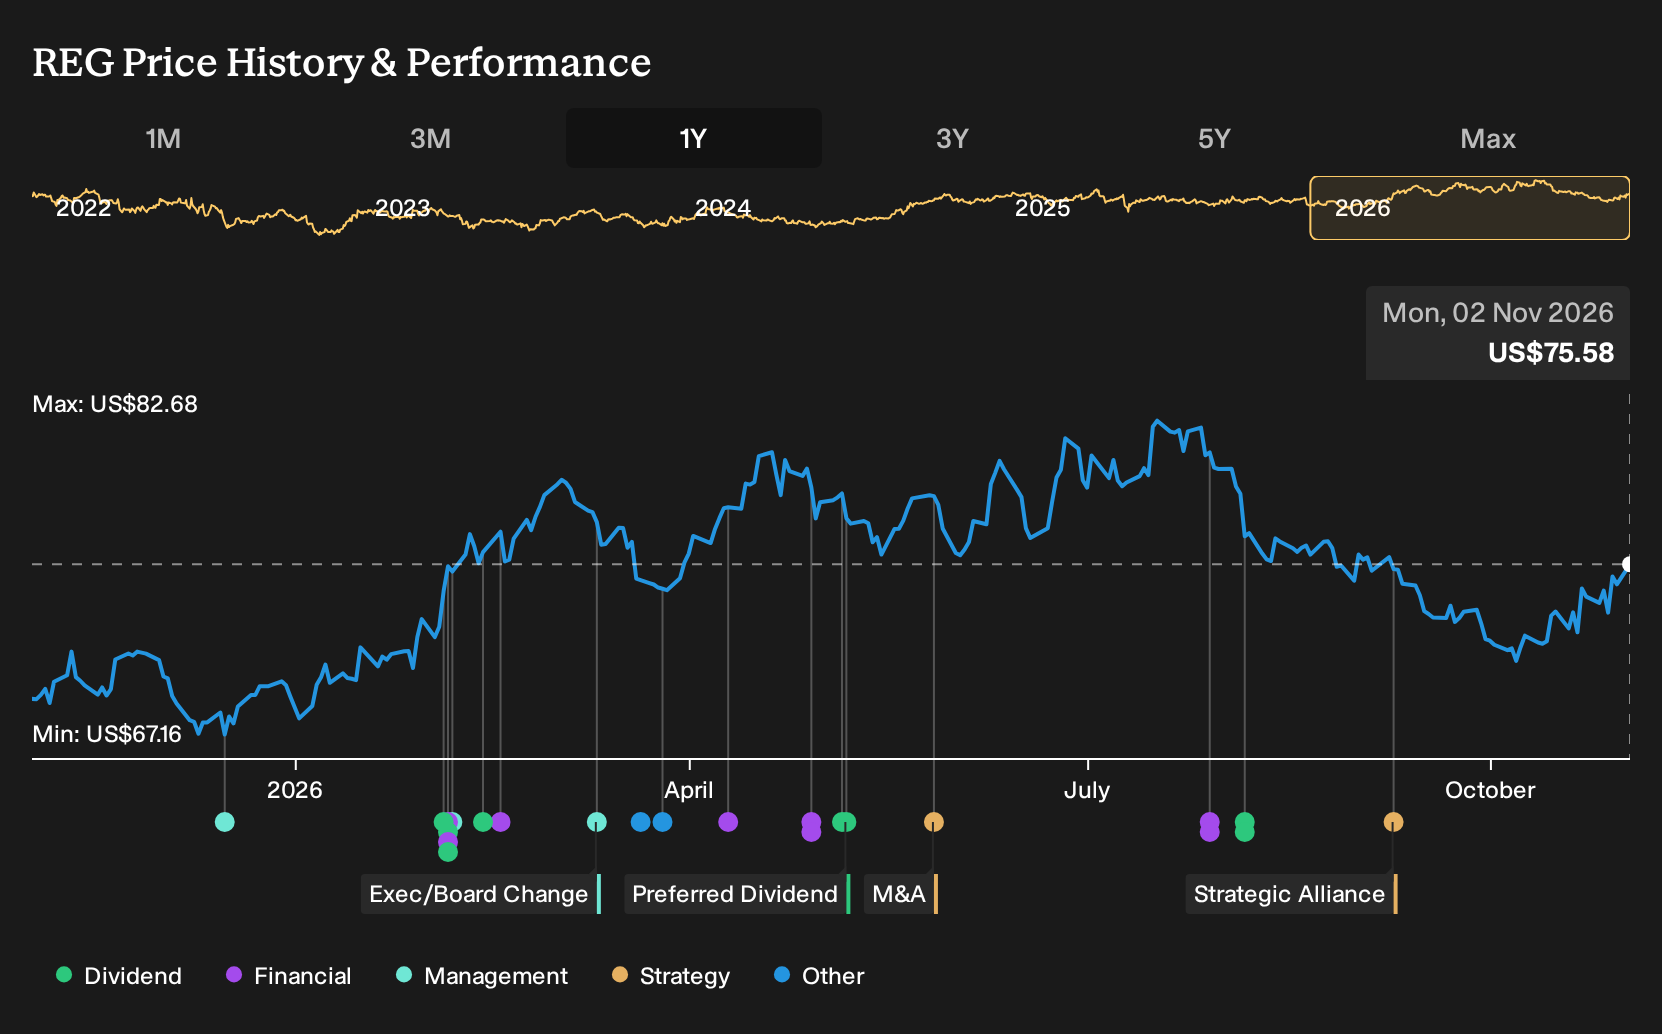
Valuation assumptions sit on top of those operating forecasts. The current consensus price target sits at US$84.83 per share, compared with a share price of US$71.71, and is based on the idea that by 2029 Regency Centers is generating US$1.8b of revenue and US$520.5 million of earnings while trading on a P/E multiple of 37.6x. That multiple is above both the firm's current P/E of 24.2x and the 25.9x figure cited for the broader US Retail REITs group, so anyone leaning on this target is implicitly assuming a richer valuation as well as the earnings path just described.
Regency Centers' narrative projects US$1.8b revenue and US$520.5 million earnings by 2029. This assumes 2.0% yearly revenue growth and an earnings decrease of US$22 million from US$542.5 million today.
Discover why Regency Centers' fair value suggests a 12% potential upside to its current price before other investors close the gap.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between about US$84 and US$104, so some members see Regency Centers close to current pricing while others pencil in a far richer outcome. Consider those opinions in light of risks around tenant distress, interest costs and development execution, then explore the full range of community perspectives yourself.
Explore 2 other Regency Centers fair value estimates, including one that suggests as much as 38% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Regency Centers research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Regency Centers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Regency Centers' overall financial health at a glance.
Looking For More Investment Ideas Beyond Regency Centers?
If you want to put Regency Centers in context, it can help to scan a wider field of stocks that share some of the qualities you care about, whether that is income resilience, balance sheet strength, or a mix of quality and value.
- For investors hunting for resilient income streams with room for capital appreciation, consider a curated set of 4 dividend fortresses that focus on reliable payouts with supporting fundamentals.
- If capital preservation and stability matter most to you, narrow your search to companies screened for strength and resilience through a 29 resilient stocks with low risk scores built around lower risk profiles.
- When you want potential future winners that the broader market may not be focused on yet, scan a targeted pool of 19 high quality undiscovered gems that combines quality metrics with less widely followed stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com