
Lattice Semiconductor (LSCC) Could Be 40% Below Fair Value As Board Changes Draw Focus
Board refresh puts governance in focus
Lattice Semiconductor (LSCC) has reshaped its board, adding industry veterans John McCool and Raejeanne Skillern, which puts governance, oversight, and long term execution back in the spotlight for shareholders.
Recent performance has been choppy. The share price is up 21.35% year to date, but the 30-day share price return is down 28.78% and the 90-day share price return is down 30.84%. The 3-year total shareholder return of 68.89% shows that longer-term holders have still seen meaningful gains.
Scan how Lattice Semiconductor compares with other potential AI and FPGA beneficiaries by reviewing our handpicked list of 53 AI infrastructure stocks in the same broader theme.
After a sharp pullback, Lattice Semiconductor now trades well below the average analyst target, even though one intrinsic value estimate points to only a small premium. This raises the question of whether the discount signals opportunity or instead reflects justified caution on the recent surge and guidance.
Most Popular Narrative: 40% Undervalued
On the narrative view, Lattice Semiconductor screens as materially below a fair value of $158 based on the last close at $95.44. This puts the focus firmly on whether the business can deliver against ambitious growth and profitability assumptions.
The expected ramp of robotics, humanoids and broader physical AI systems starting late next year, where management points to multiple FPGA sockets per system and recovering industrial demand, gives Lattice Semiconductor a second major usage driver that can broaden revenue and earnings beyond data center AI spend.
See why 29 investors see Lattice Semiconductor as 40% undervalued.
Result: Fair Value of $158 (UNDERVALUED)
Still, the bullish Lattice Semiconductor story can crack if supply chain bottlenecks squeeze margins, or if AI and industrial demand undershoot the growth baked into current forecasts.
Find out about the key risks to this Lattice Semiconductor narrative.
Another View: Lattice Semiconductor looks pricey on sales multiples
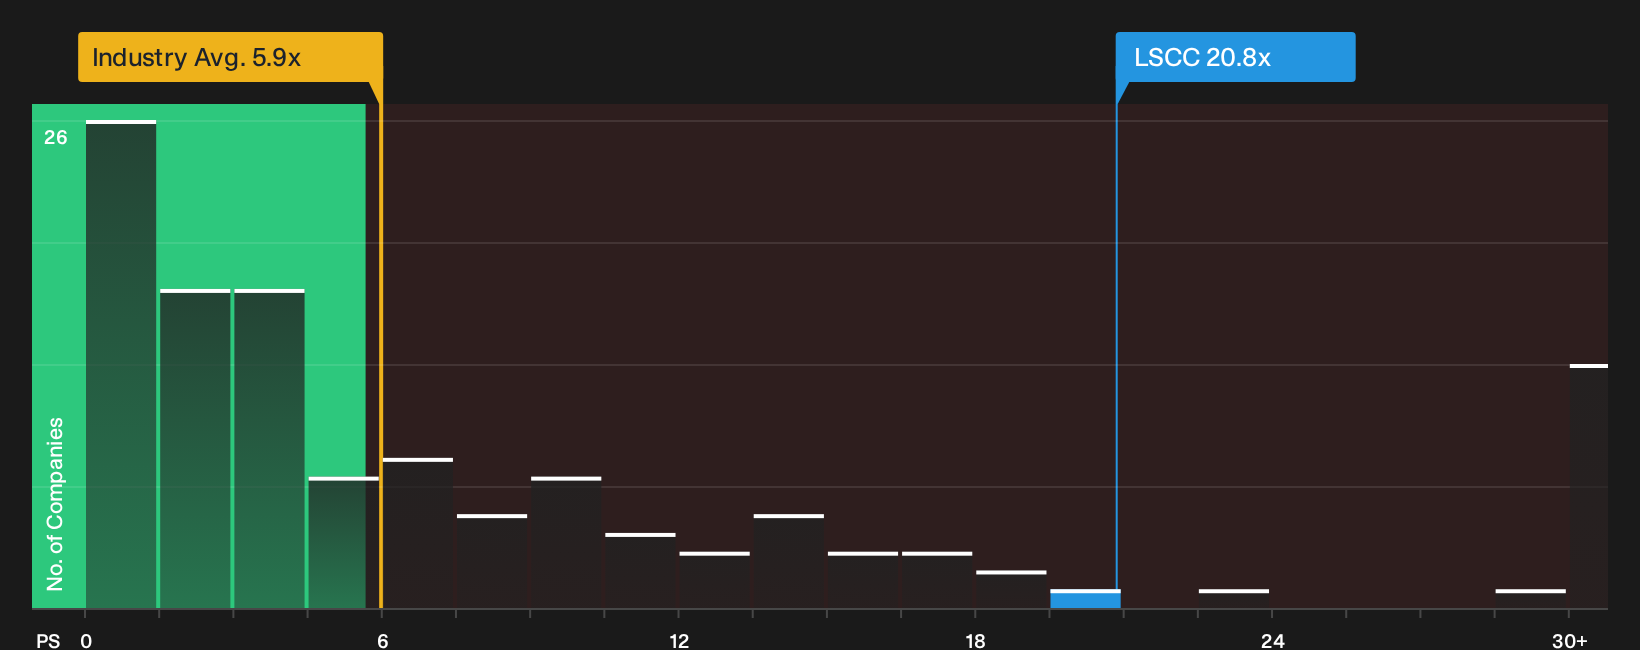
The first narrative leans on long term earnings power and analyst targets to argue Lattice Semiconductor looks undervalued. A simple P/S check tells a different story. LSCC trades on a 20.8x P/S, while peers average 5.9x and the fair ratio sits at 10.7x, putting a lot of expectation into every dollar of current revenue.
That kind of gap implies investors are already paying up for strong growth forecasts, which can amplify downside if those assumptions do not hold. For anyone weighing the story, the real question is whether this premium is a reasonable entry ticket or a margin of safety in reverse.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Lattice Semiconductor can be exciting or uneasy, depending on your risk appetite, so move quickly and pressure test the story against the underlying data. To weigh both sides with more structure, start with the 2 key rewards and 1 important warning sign.
Looking for more Lattice Semiconductor investment ideas?
If you stop at Lattice Semiconductor, you miss the chance to compare it with other compelling setups that could fit your goals even better.
- Target resilient compounding by scanning companies with strong balance sheets and healthy fundamentals using our list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities by reviewing a curated pool of quality businesses trading below their estimated value via the 34 high quality undervalued stocks.
- Secure dependable portfolio cashflow by reviewing companies that combine higher yields with sturdier payout profiles through the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com