
Is GTA 6 Demand Altering The Investment Case For Take Two (TTWO)?
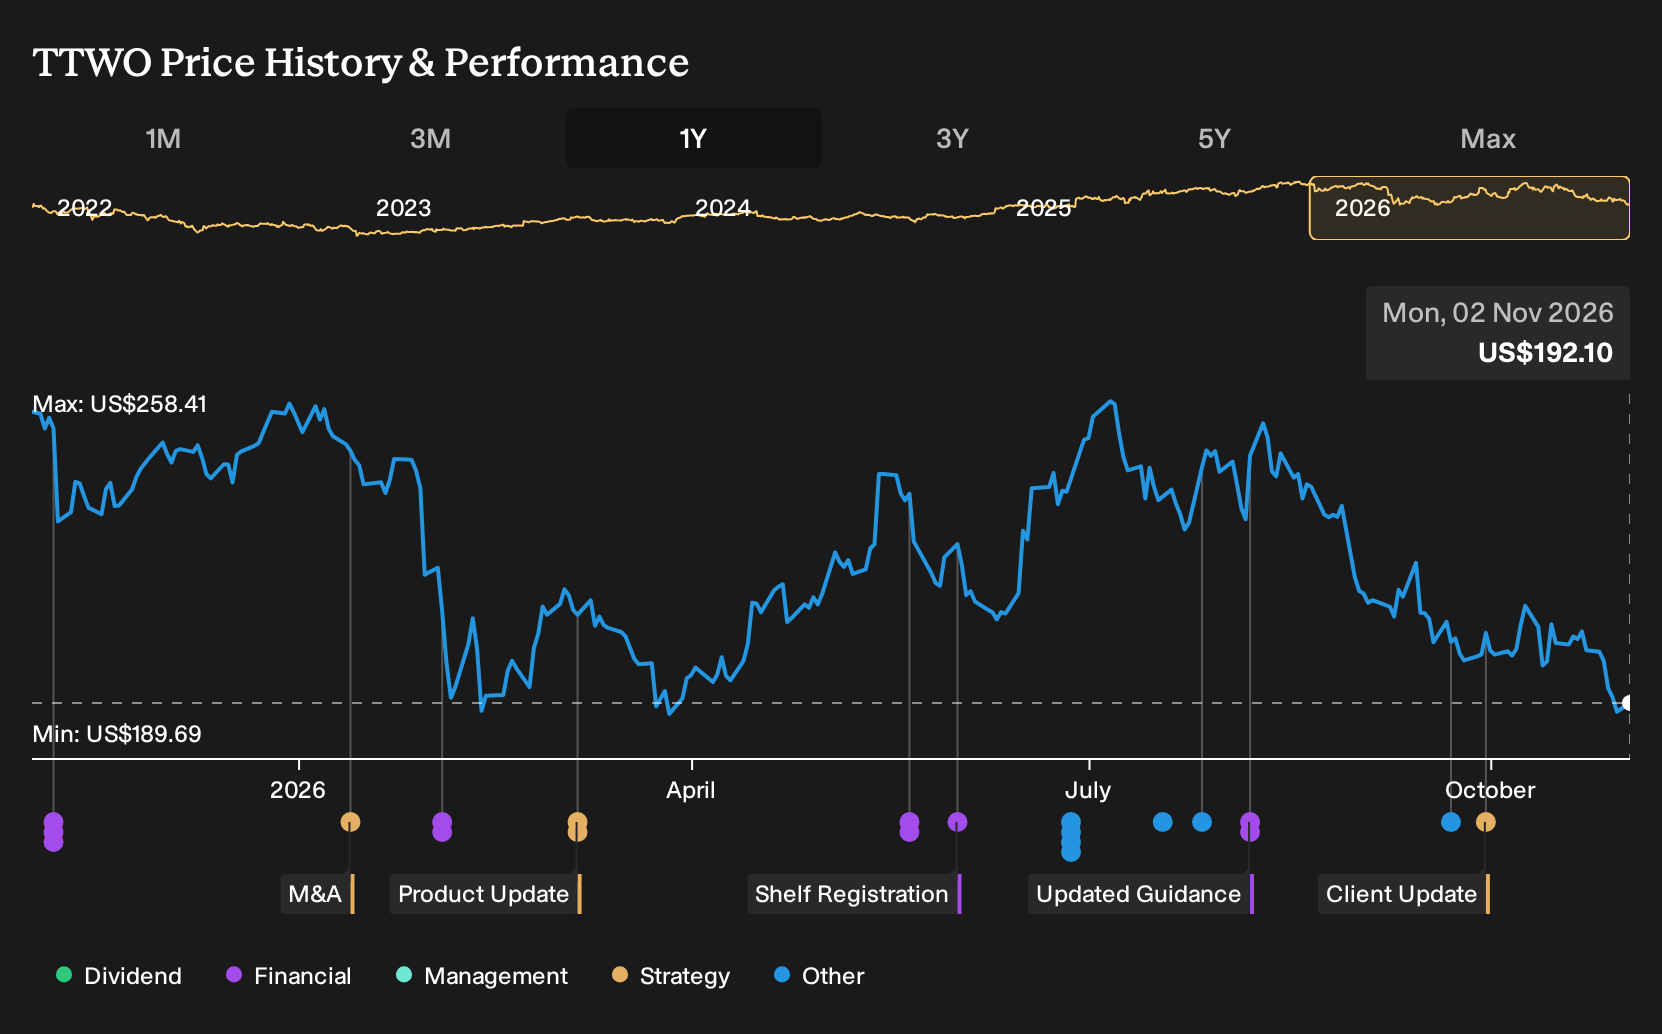
- Recent survey work pointed to strong interest in Take-Two Interactive Software’s upcoming Grand Theft Auto 6 among teen console owners, alongside expectations for earnings and revenue that are lower than the same quarter last year.
- This mix of anticipated GTA 6 demand and forecasts for softer near term bookings and earnings highlights how heavily Take-Two’s fundamentals hinge on execution around one flagship release.
- We will now look at how Take-Two Interactive Software’s investment narrative is shaped by survey backed GTA 6 demand ahead of earnings.
Take-Two Interactive Software Investment Narrative Recap
To own Take-Two Interactive Software, you need to be comfortable with a publisher whose fortunes are tightly tied to a handful of very large franchises. The big belief is that Grand Theft Auto 6 turns current interest into years of in game and online spending, while NBA 2K and Zynga titles keep underlying engagement steady. The Piper Sandler survey supports demand, but in the near term the key catalyst is still clean execution around launch timing, monetisation and platform rollout.
The biggest operational risk is that bookings and earnings expectations are already leaning heavily on that single title while the business is currently loss making. Forecasts for lower near term revenue and EPS ahead of the November 9 earnings date underline that gap between hype and reported numbers. Strong survey intent does not change that reporting risk much on its own, because management historically keeps guidance steady around preorder data.
The most relevant fresh data point is the Piper Sandler work showing 70% of teens with current generation consoles plan to buy Grand Theft Auto 6 and 90% of them expect to play GTA Online. That lines up directly with the core catalyst the market is watching. Recurrent online spending is what could support the longer term cash flow story that analysts have been modelling into FY27 and beyond.
Set that against expectations for EPS of US$0.90 and revenue of US$1.66b at the upcoming report, both below the same quarter last year, and the message is clear. The next print is likely to focus investors on guidance colour around GTA 6 engagement, online monetisation and PC timing rather than headline quarterly growth. Any sign that those engagement intentions are converting into solid visibility on bookings would be important for the Take-Two Interactive Software narrative, while execution slip or muted commentary would keep attention on the risk of overreliance on one release.
Take-Two Interactive Software's current analyst story points to forecast revenues of US$9.8b and earnings of US$1.2b by 2029, based on an assumed 13.6% yearly revenue growth rate and an earnings move from a loss of US$320.4m today to profit that is about US$1.5b higher by that forecast year.
Uncover how Take-Two Interactive Software's fair value indicates a 49% potential upside to its current price before that gap begins to close.
Exploring Other Perspectives
Some of the lowest ranked analysts frame Take-Two Interactive Software through a much more cautious lens around margins rather than GTA 6 demand. They were pencilling in revenue of about US$8.6b and earnings near US$806.5m by 2029, which is well below consensus. Those views could shift as the new GTA survey data filters into fresh models.
Explore 7 other Take-Two Interactive Software fair value estimates, including one that suggests it could be worth just $212.95.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Take-Two Interactive Software research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Take-Two Interactive Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Take-Two Interactive Software's overall financial health at a glance.
Looking for more investment ideas beyond Take-Two Interactive Software?
If the Take-Two Interactive Software story has you thinking about where else strong fundamentals or different risk profiles might show up, the Simply Wall St Screener can help you scan a wider field without getting buried in noise.
- If you want potential mispricing with solid quality traits, start by checking out 34 high quality undervalued stocks that already show healthy fundamentals and may be flying under the radar.
- For investors who care most about resilience and lower downside risk, filter the market using 29 resilient stocks with low risk scores and focus your time on businesses with more measured risk profiles.
- If balance sheet strength is the first box you want to tick, narrow the universe with a list of solid balance sheet and fundamentals (24 results) so you are only comparing companies with sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com