
Is Guidewire Software (GWRE) Cheap On Its AI Platform Launch And Gore Mutual Adoption?
Guidewire Software (GWRE) is pushing deeper into insurance automation after launching an AI driven agentic platform that ties policy, claims, pricing, and developer tools together, while Gore Mutual’s ProNavigator rollout shows early customer usage.
Guidewire Software’s latest AI platform launch and the Gore Mutual deployment land after a choppy stretch for the shares, with the 7-day share price return down 11.7% and the year-to-date share price return down 13.4%. However, the 3-year total shareholder return is up 79.9%, pointing to long-term holders still sitting on sizeable gains even as short-term momentum has cooled.
Scan beyond Guidewire Software and size up other AI infrastructure plays with the 53 AI infrastructure stocks that are also wiring advanced automation into real-world operations.
Guidewire Software now trades close to internal fair value estimates, yet sits at a meaningful discount to analyst targets after the recent slide. Is that gap a pricing error, or a rational safety buffer around execution risk and AI hype?
Most Popular Narrative: 23.8% Undervalued
Guidewire Software closed at $162.43, while the most followed narrative anchors fair value at $213.29. This points to a sizable gap that depends on how durable cloud ARR, AI tooling, and margins prove to be under the hood.
The current valuation implies the market is placing limited value on further growth from Guidewire Software’s premium linked ARR base, very low churn, and AI driven efficiency gains. This narrative views that combination as leaving the stock undervalued and providing additional upside potential if these drivers persist.
See why 11 investors see Guidewire Software as 24% undervalued.
Result: Fair Value of $213.29 (UNDERVALUED)
Still, if insurer IT budgets tighten or cloud migrations slow, the whole Guidewire Software thesis around premium ARR and AI driven upsell looks far less comfortable.
Find out about the key risks to this Guidewire Software narrative.
Another View: Guidewire Software Through The P/E Lens
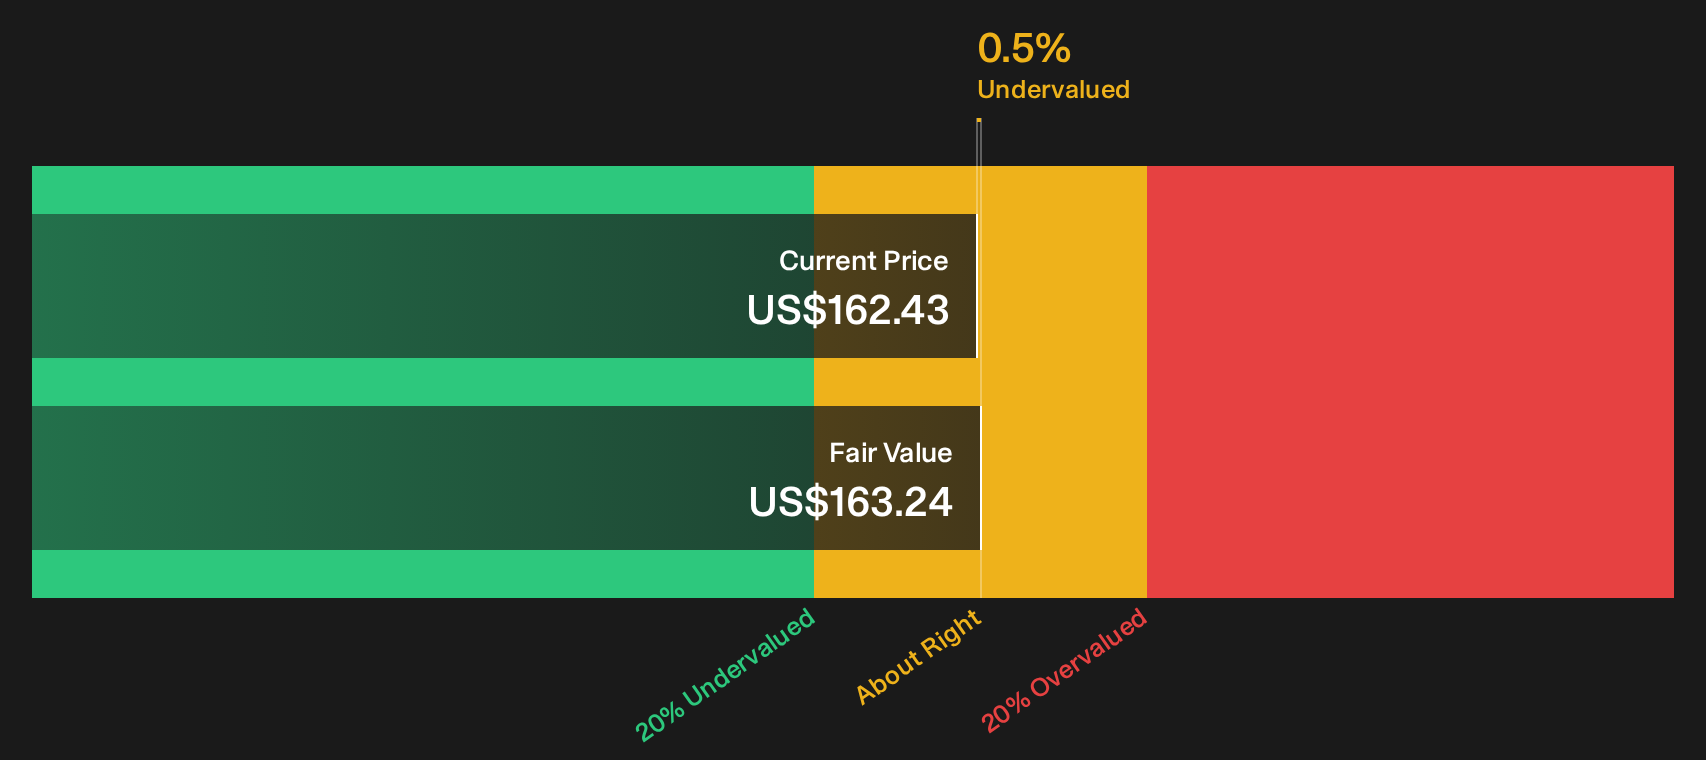
The SWS DCF model points to Guidewire Software trading roughly in line with its estimated future cash flow value, only about 0.5% below fair value at $162.43 versus $163.24. On earnings though, the picture is very different, with the stock on a P/E of 95.6x against a fair ratio of 40.2x and a US Software industry average of 31.2x. That kind of premium can reflect confidence in growth and quality. However, it also raises the risk that any disappointment in execution or AI monetisation could hit the share price harder than a cash flow model alone suggests.
For investors weighing these mixed signals, it helps to see exactly how our cash flow model gets there, step by step, through the Look into how the SWS DCF model arrives at its fair value..
Next Steps
If this mix of opportunity and risk around Guidewire Software leaves you uncertain, move quickly to inspect the underlying numbers and sentiment yourself. To see how the potential upside and downside stack up in one place, review the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Guidewire Software?
If you want a wider bench of opportunities alongside Guidewire Software, let the Simply Wall Street Screener surface ideas instead of leaving them to chance.
- Target potential mispricings by scanning for companies that combine quality fundamentals with a margin of safety through the 34 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for businesses with robust finances and dependable balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Hunt for lesser known opportunities by zeroing in on financially strong outliers via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com