
Is Somnigroup International (SGI) Undervalued As Analyst Upgrades Lift Earnings Hopes?
Somnigroup International (SGI) is back in focus after recent analyst revisions pointed to higher earnings and revenue expectations for the September 2026 quarter, putting the upcoming November 9 report under closer investor scrutiny.
Recent trading has reflected that optimism, with a 1-day share price return of 4.5% and a 7-day gain of 6.9% lifting Somnigroup International to US$66.42. However, the share price is still down 25.15% year to date and the 1-year total shareholder return has declined 15.68%, while the 3-year and 5-year total shareholder returns of 82.15% and 56.09% respectively point to stronger longer term momentum.
Compare Somnigroup International's setup with a curated group of consumer-focused businesses that have shown resilient returns and balance sheets through our 29 resilient stocks with low risk scores.
The recent bounce in Somnigroup International could be investors re-rating the business ahead of earnings rather than a lasting shift in mood. Does the current valuation reflect that distinction yet?
Most Popular Narrative: 29% Undervalued
Somnigroup International closed at $66.42, while the most followed narrative framework arrives at a fair value of about $93.44. That gap hinges on whether supply chain control and earnings expansion from acquisitions actually come through.
The integration of Mattress Firm is already generating meaningful sales and cost synergies, with $100 million in annual net cost synergies projected and sales synergies ahead of schedule. These operational improvements are set to expand EBITDA and enhance net margins moving into 2026 and beyond.
See why 6 investors see Somnigroup International as 29% undervalued.
Result: Fair Value of $93.44 (UNDERVALUED)
Still, the narrative can crack if weaker demand in key bedding categories persists or if Somnigroup International struggles to deliver the planned synergies from Leggett & Platt.
Find out about the key risks to this Somnigroup International narrative.
Another View: Somnigroup International Looks Pricey On Earnings
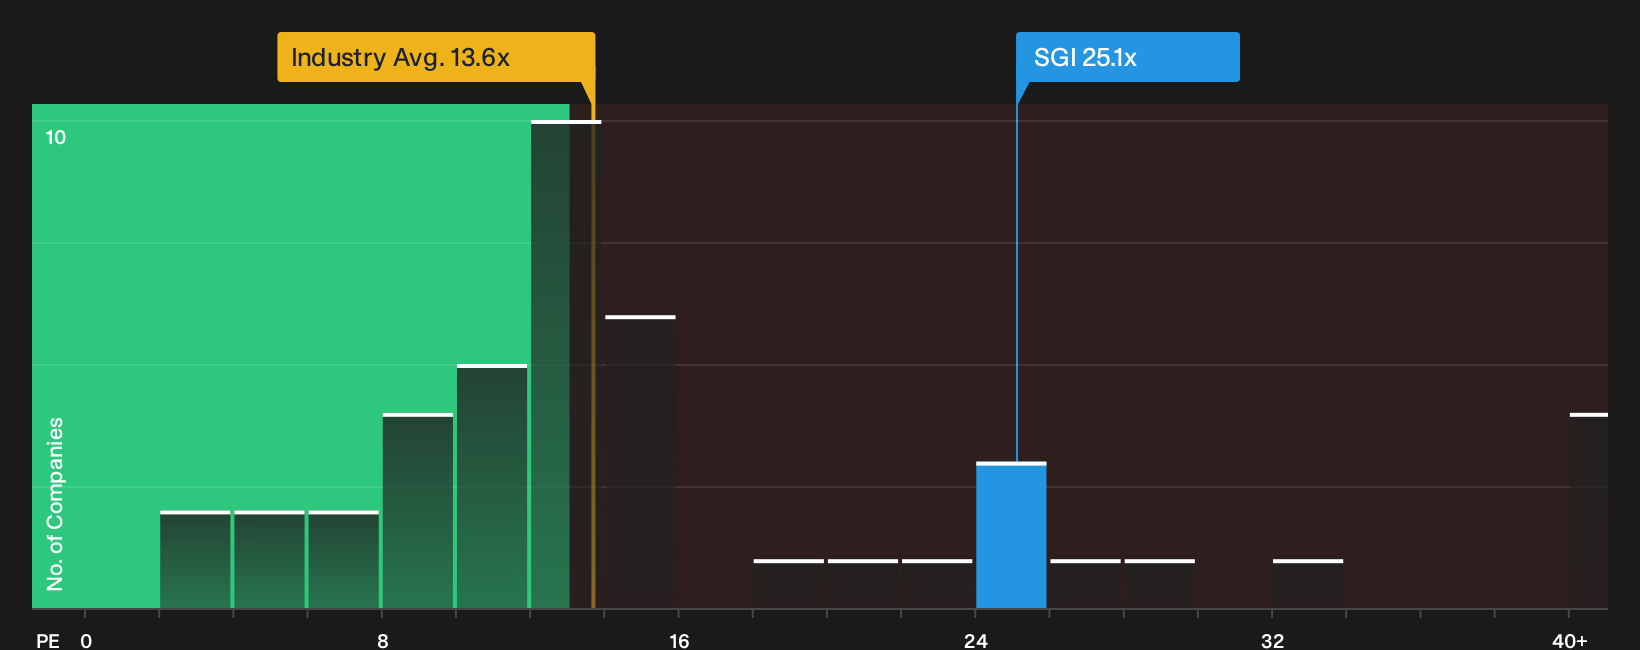
Somnigroup International screens as undervalued on fair value models, yet the P/E of 26.2x tells a tougher story. That multiple is almost double both the US Consumer Durables average and peer group at 13.6x, and slightly above a 26x fair ratio that the market could move toward over time.
If sentiment cools or expectations reset, a shift closer to industry and peer multiples could weigh on the share price before any cash flow upside plays through. The question for investors is which lens to put more weight on right now: the income-based model, or what the market is paying per dollar of earnings.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Somnigroup International can feel confusing, so treat this as your prompt to move quickly, stress test the numbers, and form your own stance. To weigh the full picture of concerns and potential upsides in one place, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Somnigroup International?
If Somnigroup International is on your radar, broaden your watchlist with a few targeted screens that surface different types of opportunities before the crowd catches them.
- Target potential value candidates by reviewing the 34 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect their underlying metrics.
- Strengthen your income approach by scanning the 4 dividend fortresses that focus on higher yielding payouts supported by more robust financial profiles.
- Hunt for earlier stage potential by zeroing in on the 8 elite penny stocks with strong financials that pair smaller market caps with stronger balance sheets and cash generation than many peers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com