
Does Stronger Earnings Change The Bull Case For Mapfre (BME:MAP)?
- Mapfre reported third quarter 2026 net income of €300.1 million and nine month net income of €924.3 million, both higher than the prior year period.
- The earnings call around these results gives investors a clearer view of how Mapfre is managing underwriting quality and profitability across its insurance portfolio.
- Next, the focus shifts to how Mapfre's stronger net income profile might reshape the investment narrative that analysts had already built.
Scan how Mapfre’s latest earnings shift compares with peers by lining it up against 221 dividend fortresses, which pairs income potential with balance sheet resilience.
Mapfre Investment Narrative Recap
To hold Mapfre, you need to be comfortable with an insurer that leans on technical discipline, capital strength and steady earnings rather than fast revenue expansion. The latest €300.1 million third quarter and €924.3 million nine month net income print supports that profit focused story. In the near term, the key swing factor is still underwriting quality, especially in Non Life and reinsurance.
The biggest operational risk remains pressure from pricing and regulation in key markets, coupled with currency moves that can dilute euro reported results. This quarter’s higher net income helps cushion those issues but does not remove them. It mostly reinforces that the current operating playbook is holding together for now.
The nine month 2026 earnings call on 28 October is the most relevant recent event for this catalyst and risk mix. Management commentary around combined ratios, pricing discipline and capital allocation gives you context for the higher net income figures. It also helps you judge whether the Safety Insurance integration and Latin America exposure still look aligned with the existing thesis.
For catalysts, the call matters because it shows how Mapfre is thinking about digital efficiency, cost control and product mix. On the risk side, any detail on tax or regulatory headwinds in markets like Mexico or Colombia, or on softer reinsurance pricing, feeds directly into how durable you see this earnings profile being.
Mapfre Earnings Assumptions and Valuation Set Up
Analysts looking at Mapfre are effectively working off a playbook where top line volume softens while profitability inches higher. The consensus view assumes revenue declines by 2.4% a year over the next three years, even as profit margins are expected to move from 3.8% today to 4.9% by 2029. That mix of slightly thinner premium volume and fatter margins sits behind a forecast that earnings today of about €1.2b rise to €1.4b by 2029, with most forecasters clustering around that line.
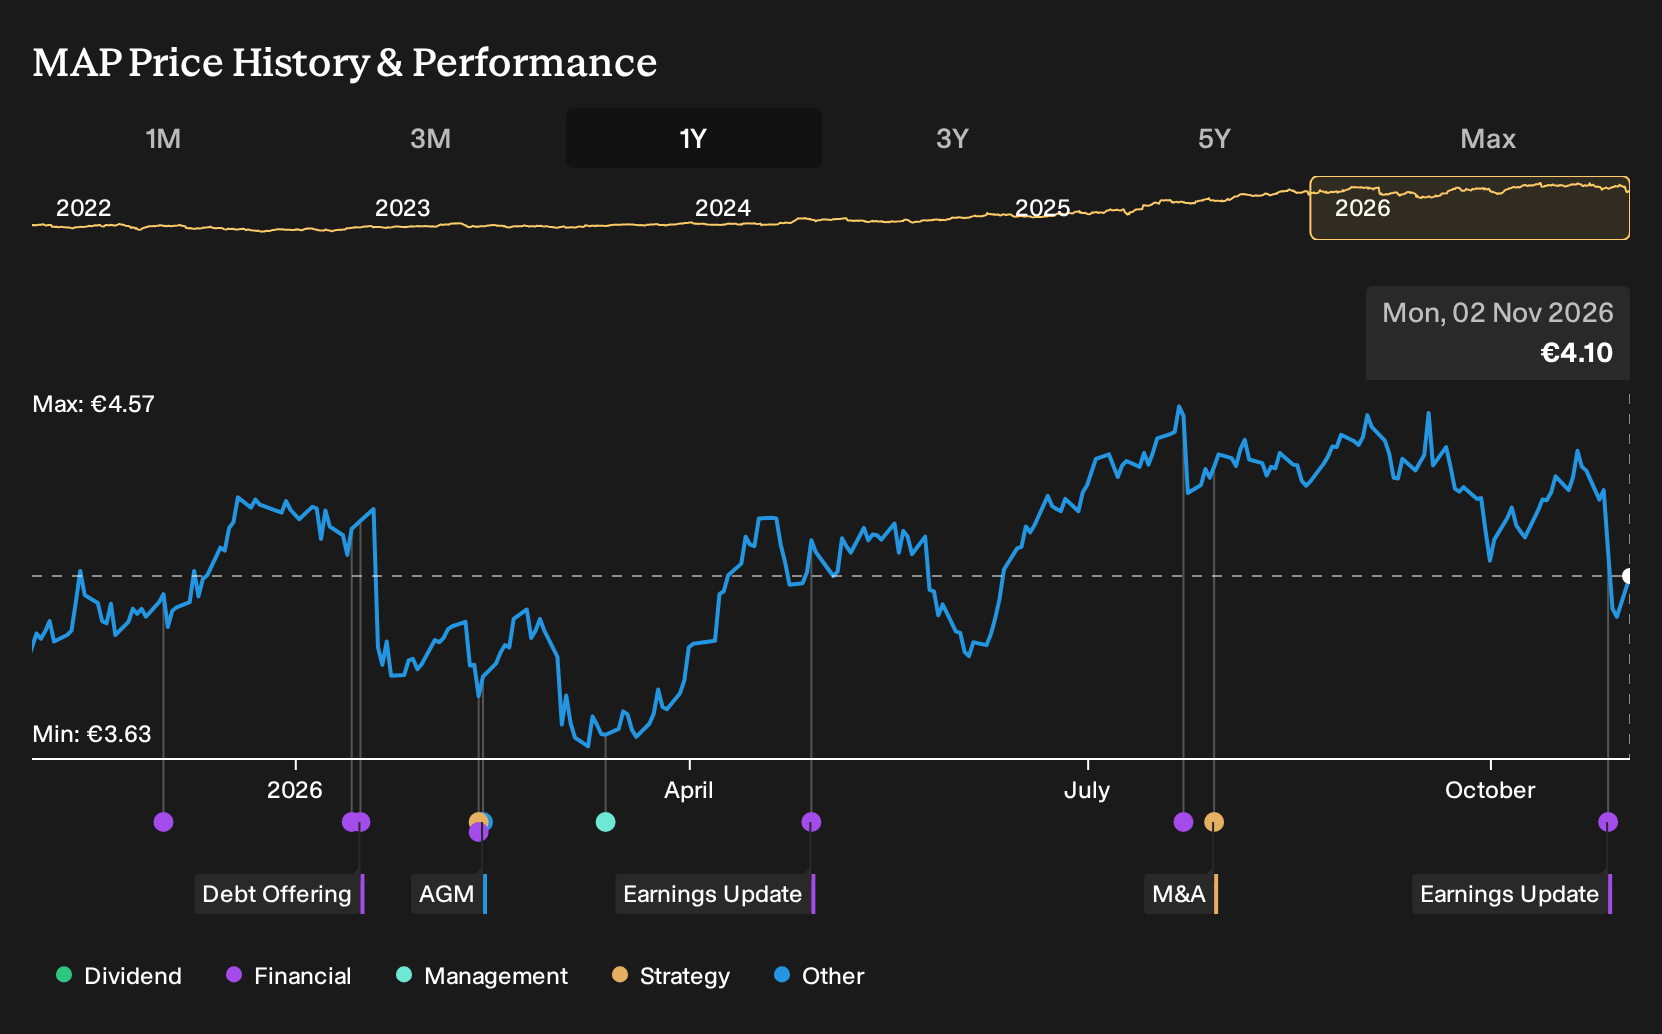
Those same projections feed directly into how the stock is framed on valuation. The analyst group is effectively anchoring on Mapfre generating about €29.0b of revenue and €1.4b of earnings in 2029. They then assume the shares trade on a P/E of 11.2x, compared with 11.4x today and 14.2x for the wider GB insurance sector. The maths is then pulled back to today using a 7.4% discount rate, along with a small expected reduction in share count of 0.12% a year, to arrive at a consensus price target of €4.24 against a current share price of €4.39.
For you as an investor, the key question is not whether those precise numbers will land, but whether the broad shape of this story feels credible. The market view implies a business that leans on underwriting discipline and margin work rather than headline revenue expansion. It also assumes that Mapfre continues to convert that margin profile into around €1.4b of earnings in 2029 without relying on a premium valuation multiple to support the equity case.
Mapfre's narrative projects €29.0b revenue and €1.4b earnings by 2029. This rests on revenue declining by 2.4% per year and an earnings increase of about €200m from current earnings of roughly €1.2b.
Uncover why Mapfre's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You might see Mapfre very differently if you focus on the bullish catalyst around Safety Insurance. The most optimistic analysts were already sketching a story that reaches about €30.6b of revenue and €1.5b of earnings by 2029, before this €300.1m quarter arrived. That gap in expectations shows how sharply views can diverge. Use the new results as a prompt to compare those pre‑news forecasts with your own read on the business and explore several alternative viewpoints.
Explore 2 other Mapfre fair value estimates, including one that suggests as much as 92% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Mapfre research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Mapfre. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mapfre's overall financial health at a glance.
Looking For More Investment Ideas Beyond Mapfre?
If the Mapfre story has sharpened your thinking about income, risk and balance sheet strength, it can be useful to line that framework up against other potential holdings using the Simply Wall St Screener.
- If resilience is your priority, scan for 216 resilient stocks with low risk scores that may offer a smoother ride through market swings.
- If you want income backed by fundamentals, scope out 221 dividend fortresses that balance yield with financial strength.
- If you prefer hunting for under followed opportunities, search through 603 high quality undiscovered gems that pair quality metrics with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com