
Why Franklin Electric Stock Is In Focus After Earnings Beat And Higher Sales Guidance
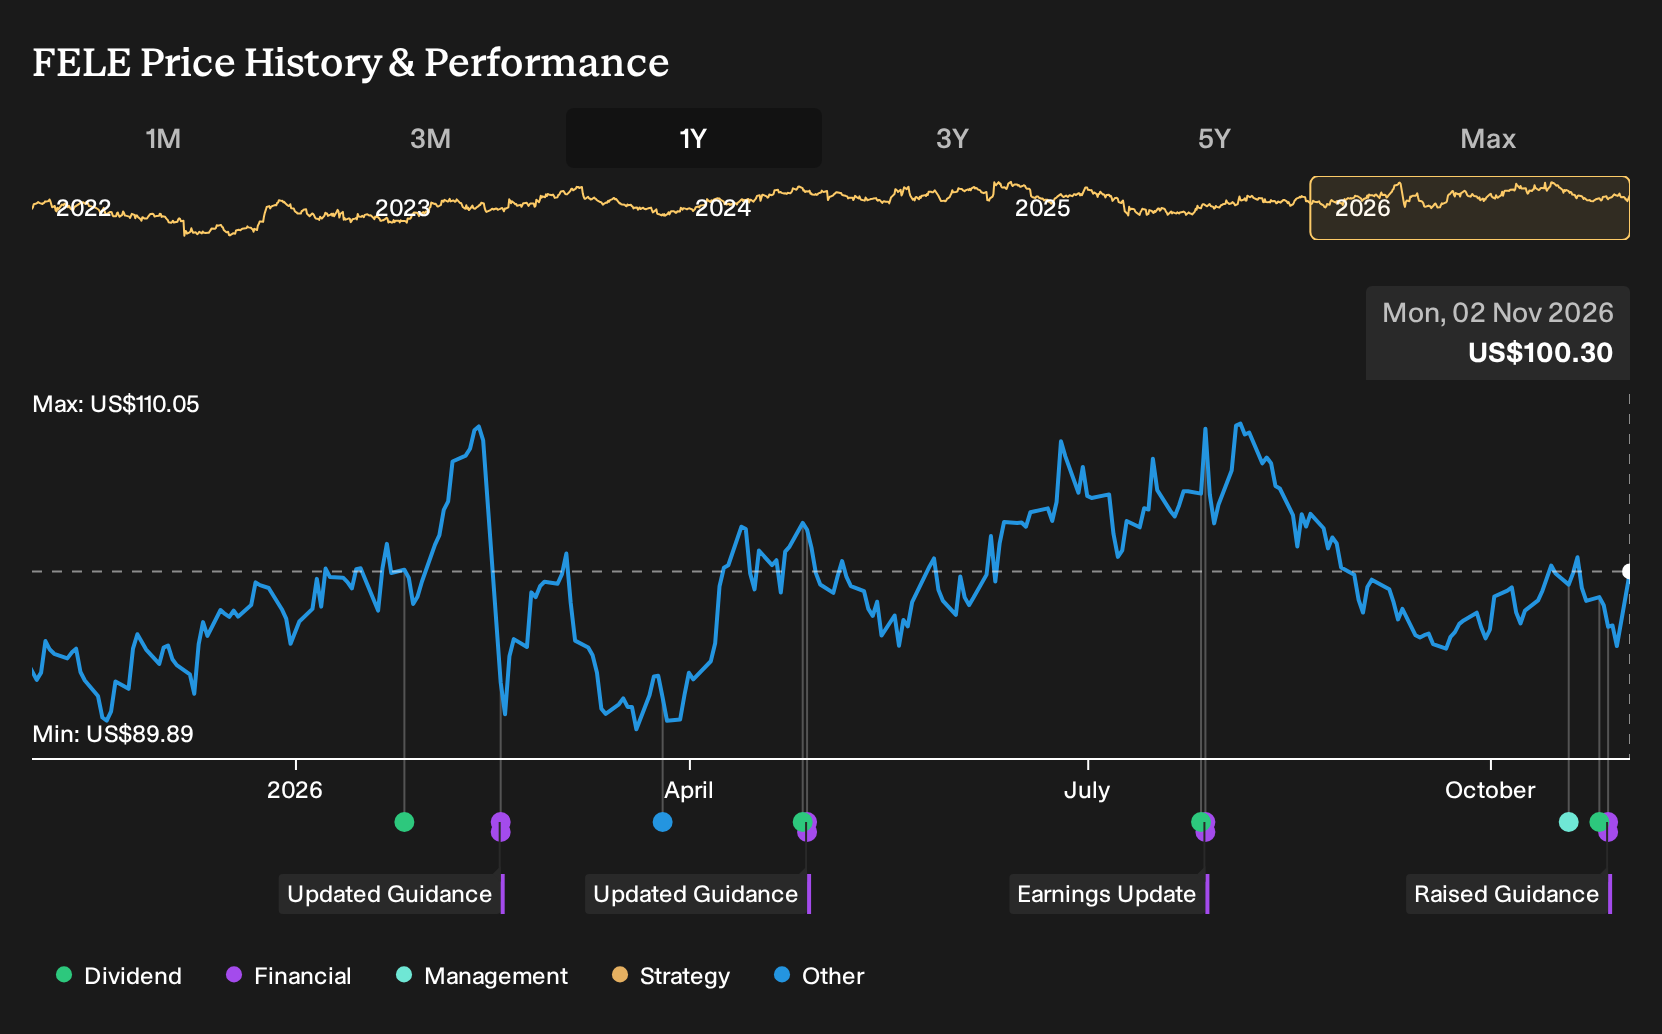
- Franklin Electric reported third quarter 2026 sales of US$633.62 million and net income of US$60.65 million, alongside higher earnings per share and raised full year 2026 net sales guidance to a range of US$2.23 billion to US$2.30 billion.
- The nine month figures show Franklin Electric generated US$1.76 billion in sales and US$160.72 million in net income, which highlights how recent performance is tracking against the upgraded full year sales outlook.
- The next area of focus is how Franklin Electric's raised 2026 sales guidance reshapes the broader investment narrative around the business.
What Is Franklin Electric's Investment Narrative?
To own Franklin Electric, you need to be comfortable with a fairly straightforward thesis. This is an industrial manufacturer that lives or dies by execution, reliable demand for water and fuel systems, and its ability to keep capital spending disciplined while still refreshing products and distribution. The latest quarter, with higher earnings per share and raised 2026 net sales guidance, supports a view that current orders and pricing are holding up well enough to justify a busier production schedule.
In the near term, the key drivers are whether Franklin Electric can sustain this earnings momentum, keep net profit margins around recent levels, and continue to use its balance sheet sensibly while paying that US$0.28 quarterly dividend. Raised guidance and solid nine month numbers help the bullish side of the story, yet they also raise the bar. Execution risk, end market exposure and capital allocation choices now matter even more to the next leg of the Franklin Electric narrative.
Yet there is still one pressure point that could unsettle this seemingly clean setup if ...
There's only one way to know the right time to buy, sell or hold Franklin Electric. Head to Simply Wall St's company report for the latest analysis of Franklin Electric's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community range from roughly US$127.50 to US$151.10. This already shows how far apart views on Franklin Electric can sit, even before the latest earnings and guidance. Use that spread as a prompt to test your own assumptions and explore several alternative viewpoints.
Explore another Franklin Electric fair value estimate, including one that suggests as much as 51% upside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Franklin Electric research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Franklin Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Franklin Electric's overall financial health at a glance.
Looking For More Investment Ideas Beyond Franklin Electric?
If Franklin Electric has helped sharpen your thinking about quality and guidance, you can apply that same lens across the wider market. The Simply Wall St Screener can help you quickly spot other companies that fit different objectives, from value hunting to income focus to financial resilience.
- For investors looking for potentially mispriced quality, review a curated 34 high quality undervalued stocks that combines strong fundamentals with more modest expectations reflected in current prices.
- If resilience and balance sheet strength are your priority, compare Franklin Electric with a broader 29 resilient stocks with low risk scores that filters for businesses with lower overall risk scores.
- Income driven readers who want yield supported by fundamentals can scan a focused 4 dividend fortresses built around higher payout levels and durable profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com