
DHT Holdings (DHT) Gains Attention After Strait Of Hormuz Disruption, Is It Below Fair Value?
Recent strikes involving the US, Israel, and Iran that have disrupted the Strait of Hormuz put DHT Holdings (DHT) in sharper focus, since crude tanker earnings and dividend capacity often move with freight rates and route risk.
DHT Holdings has felt that shift in risk perception in the share price, with the stock down 4.6% on a 1-day share price return and 3.0% over 7 days, even though the 90-day share price return of 31.5% and year-to-date share price gain of 103.2% point to strong recent momentum and a 1-year total shareholder return of 110.2% that extends into a very large 5-year total shareholder return of roughly 4.8 times the initial investment.
Scan how DHT Holdings compares with other shipping and energy plays reacting to the same Middle East flashpoints by reviewing the hand picked 34 high quality undervalued stocks.
Bulls see DHT Holdings as a high earning tanker operator briefly knocked back by headlines. Bears see a cyclical spike already priced in. Which side do the current valuation markers actually support?
Most Popular Narrative: 20.5% Undervalued
DHT Holdings closed at $23.86 against a widely followed narrative fair value of $30.00, so the current quote prices in a clear discount while analysts still model shrinking revenue and earnings over the coming years.
Extended crude trade routes driven by regional conflict and Red Sea disruptions are increasing global ton miles. This can keep VLCC utilization high and support day rates, with potential benefits for revenue and earnings if these trade patterns persist.
See why 1 investors see DHT Holdings as 20% undervalued.
Result: Fair Value of $30.00 (UNDERVALUED)
Still, if conflict driven rerouting fades, or if secondhand VLCC prices stay high, DHT Holdings could see both future earnings power and fleet renewal options pressured.
Find out about the key risks to this DHT Holdings narrative.
Another View: Cash Flows Point A Different Way
The first narrative for DHT Holdings leans on a $30.00 fair value built from earnings and multiples. Our DCF model tells a very different story, with an estimated future cash flow value of $13.33 that sits well below the current $23.86 share price. Which picture fits better with the risks you see?
Look into how the SWS DCF model arrives at its fair value.
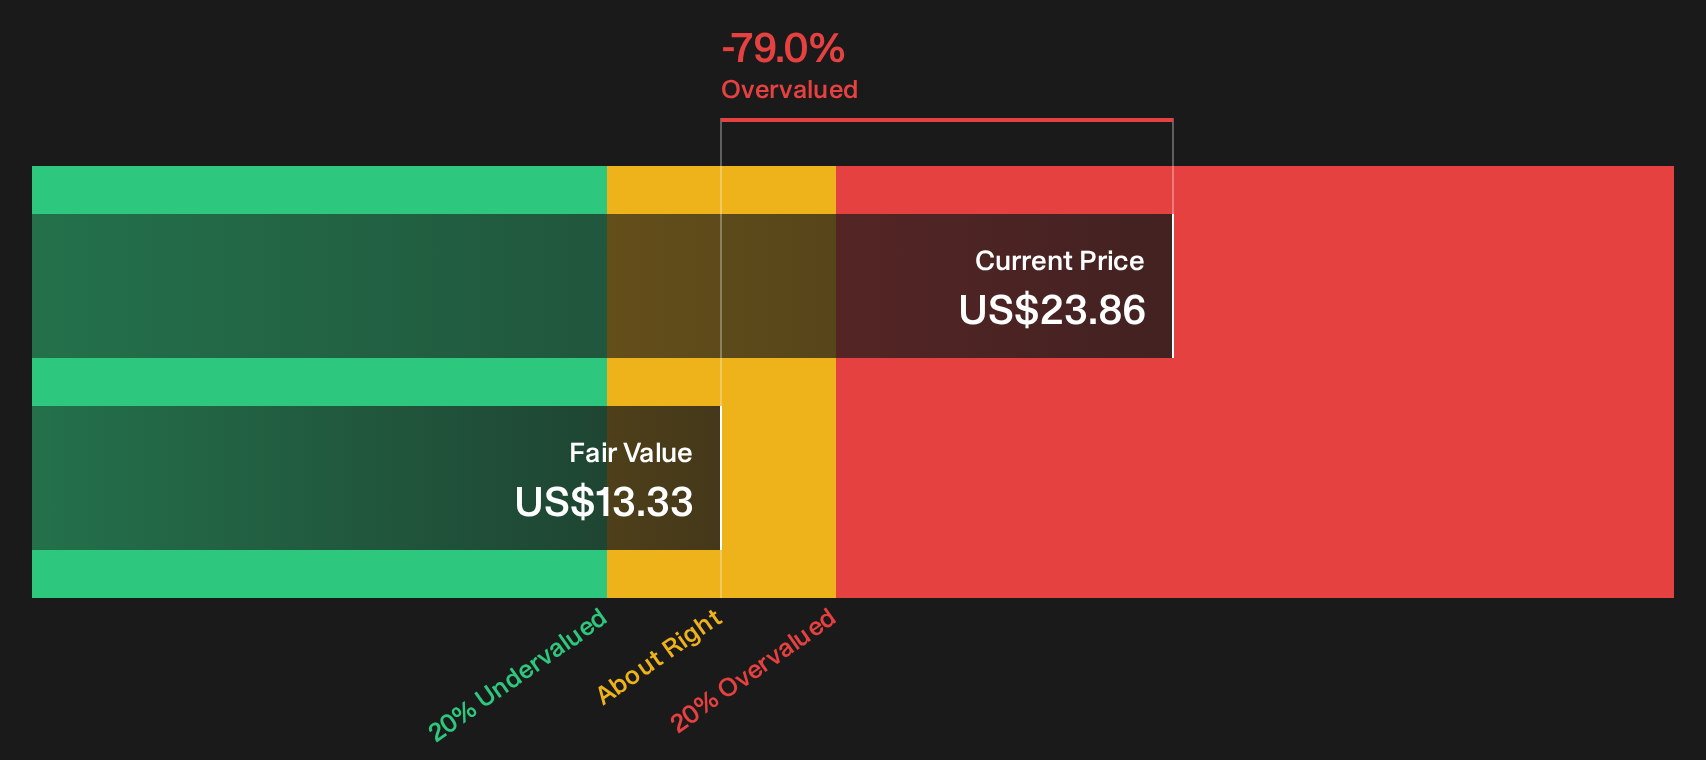
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DHT Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on DHT Holdings is clearly split, and that is exactly when doing your own homework matters most. Act while the data is fresh and pressure test both the upside and downside using the 2 key rewards and 4 important warning signs.
Looking for more ideas beyond DHT Holdings?
If you only stop at DHT Holdings, you risk missing out on other setups that fit your style, risk tolerance, and income goals in a tighter way.
- Target punchier upside potential with the 9 elite penny stocks with strong financials that already clear strict financial strength filters.
- Prioritise resilience and sleep at night by scanning the 29 resilient stocks with low risk scores that score well on balance sheet and risk metrics.
- Hunt for quality that has not yet drawn the crowd by working through the 19 high quality undiscovered gems before the wider market catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com