
Vossloh (XTRA:VOS) Reaffirms 2026 Outlook On Rising Sales And Margin Pressure კითხვ
Why Vossloh stock is back in focus
Vossloh (XTRA:VOS) reaffirmed its 2026 guidance and paired that with fresh nine month figures, signaling solid sales but weaker profitability. This combination puts the stock's recent performance and valuation back under the microscope for investors.
Recent trading tells a mixed story. Vossloh shares have slipped sharply over the year, with the year to date share price return down 36.58%. However, the 3 year total shareholder return of 37.63% and 5 year gain of 15.63% show that longer term holders have still come out ahead despite the more recent loss of momentum.
Spot opportunities alongside Vossloh by scanning a hand-picked 193 high quality undervalued stocks that combine solid cash generation with balance sheet strength.Vossloh now trades after a sharp reset, yet the business reports higher nine month sales alongside squeezed earnings. Is the share price reacting to weaker fundamentals, or to sentiment that has swung too far?
Price-to-Earnings of 34.9x: Is Vossloh's premium justified?
Valuation now hinges on one key fact. Vossloh trades on a P/E of 34.9x while its own fair ratio is marked at 31.4x and the German Machinery industry sits at 17.1x.
The P/E ratio links what you pay for each share to the earnings that the business generates today. For an infrastructure supplier like Vossloh, this figure often reflects how confident the market feels about the durability of its profit stream and the trajectory of future earnings.
Here, the picture is mixed. On one side, Vossloh scores as trading at 51.8% below an internal estimate of fair value and our DCF work flags the share price of €49.66 as below an estimated future cash flow value of €103. On the other side, net profit margins have compressed from 4.5% to 1.8%, return on equity sits at a low 5.5%, and the dividend yield of 2.32% is not well covered by free cash flow.
Compared to peers, the market is paying a materially richer earnings multiple. Vossloh at 34.9x is priced slightly above the peer average of 34.3x and at roughly double the German Machinery industry on 17.1x. The estimated fair P/E of 31.4x suggests a level the multiple could reasonably move towards if expectations cool or earnings catch up.
Explore the SWS fair ratio for Vossloh.
Result: Preferred multiple of price-to-earnings of 34.9x (OVERVALUED)
Still, Vossloh faces pressure if compressed net margins persist or free cash flow continues to fall short of its dividend, particularly following a sharp share price reset.
Find out about the key risks to this Vossloh narrative.
Another view on Vossloh's value
The P/E discussion portrays Vossloh as expensive compared with peers, yet the SWS DCF model suggests the opposite. On that cash flow view, a share price of €49.66 is set against an estimated value of €103, which may indicate undervaluation. Which lens should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
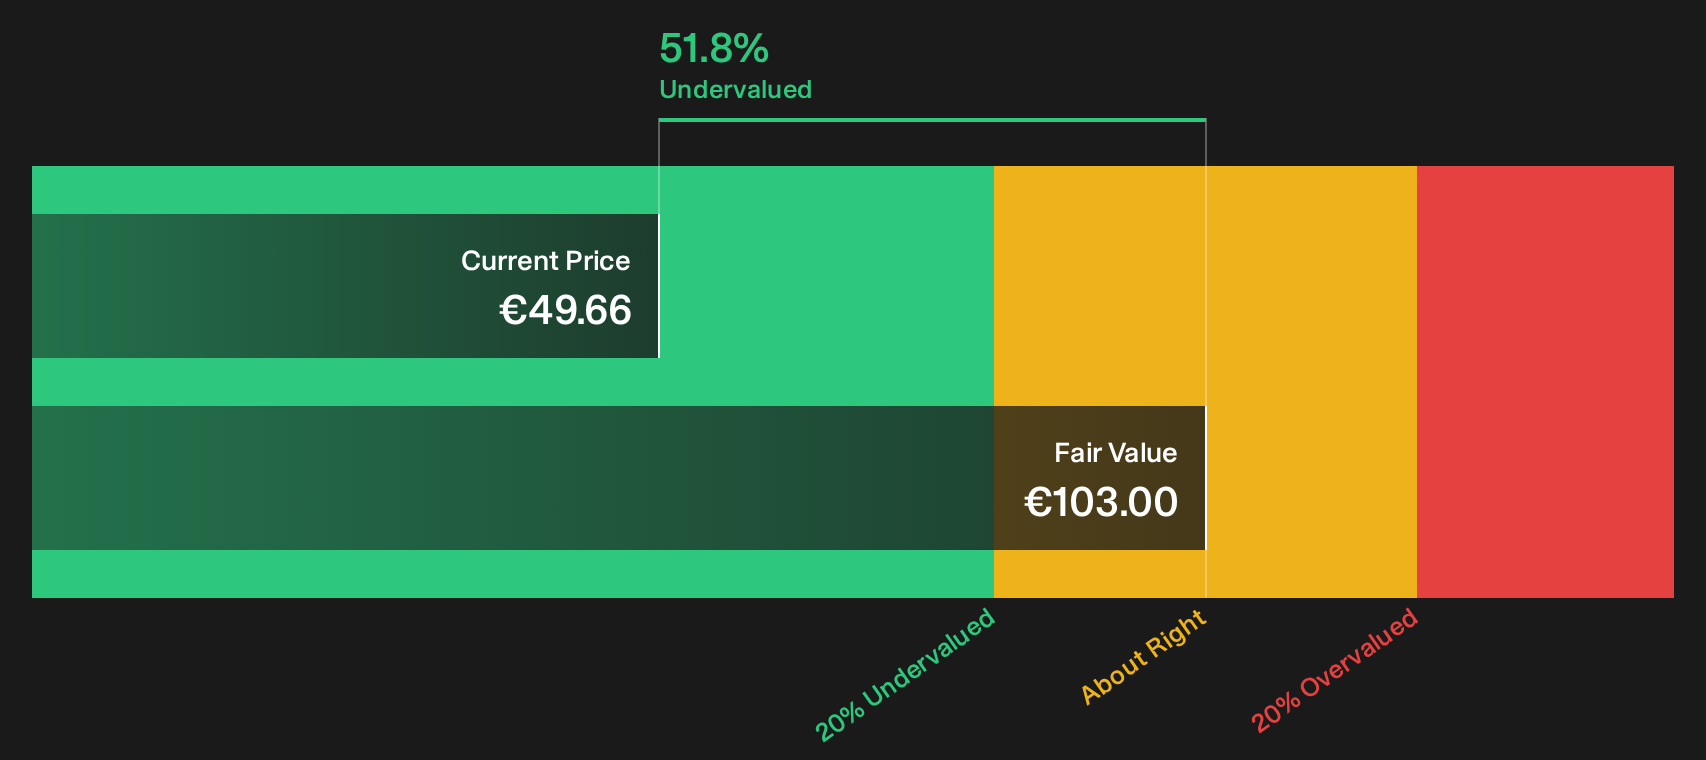
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Vossloh for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Vossloh can leave the picture feeling blurred, so it helps to check the underlying data quickly and weigh the risks against the upside potential for yourself. To see that balance set out clearly, take a look at the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Vossloh?
If you stop with Vossloh, you risk missing other setups that match your style. Broaden the view and hunt for fresh candidates now.
- Target potential mispricing early by scanning a curated pool of quality businesses trading below internal estimates of value through the 193 high quality undervalued stocks.
- Prioritise resilience by focusing on companies with strong finances and sturdy balance sheets using the list of solid balance sheet and fundamentals (197 results).
- Spot lesser known opportunities with robust fundamentals before they hit the spotlight by screening through the 603 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com