
Record Mine Cash Flow Could Be A Game Changer For DPM Metals Stock (TSX:DPM)
- DPM Metals highlighted record quarterly free cash flow from the Vareš mine, which recently reached commercial production and is targeting an 850,000 tonne per year run rate.
- The focus on whether this new low cost operation can sustain strong cash generation while cost and pricing pressures evolve is now central to assessing the operating strength of DPM Metals.
- We will now look at how DPM Metals' record free cash flow from Vareš could reshape the broader investment narrative around the business.
Scan how DPM Metals compares to other cash generative miners by reviewing our curated list of 34 elite gold producer stocks in one place.
DPM Metals Investment Narrative Recap
DPM Metals appeals to shareholders who want exposure to producing gold assets backed by strong recent cash generation. To stay comfortable in the stock, you need to believe management can keep Vareš, Ada Tepe and Chelopech running efficiently while cost pressures from labor, currencies, royalties and energy are managed without eroding margins.
The record free cash flow from Vareš sharpens the near term focus on whether this mine can maintain low all in sustaining costs as it ramps toward the 850,000 tonne per year run rate. The biggest current risk remains cost inflation and any production disruption, especially if commodity prices soften at the same time.
The most relevant recent development is the ramp up of the Vareš silver gold mine, which has reached commercial production with an all in sustaining cost of US$563 per gold equivalent ounce in Q2 2026 and is targeting 850,000 tonnes per year. This new operation gives DPM Metals another low cost source of cash that can support the wider portfolio.
That cash flow adds to an already strong financial position, including US$761 million of cash, about US$1.2b of total liquidity and no debt at Q2 2026. For catalysts, investors will likely watch how Vareš performs at steady state and how that supports funding of Čoka Rakita and ongoing exploration without heavy reliance on external financing.
DPM Metals' current analyst narrative points to revenue of $1.3 billion and earnings of $833.1 million by 2029, based on forecasts that assume revenue stays broadly flat over the next few years. This implies earnings would rise by about $183.8 million from $649.3 million today.
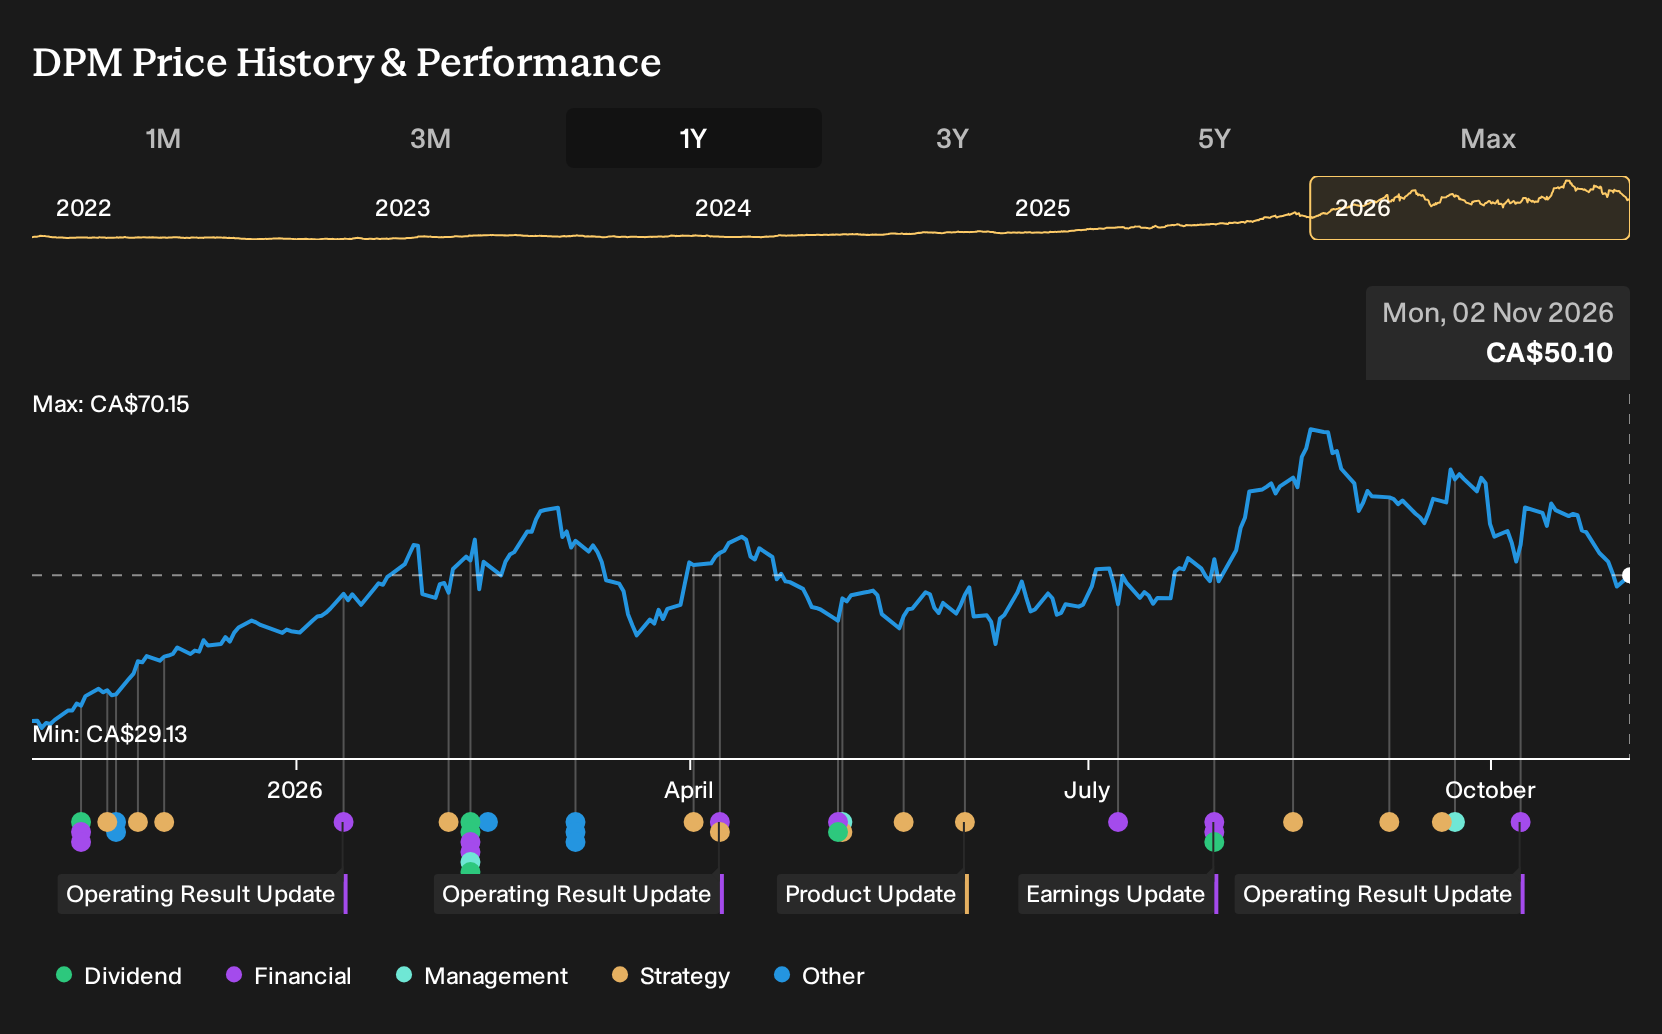
Uncover how DPM Metals' fair value indicates a 36% potential upside to its current price, a discount that could close faster than investors expect.
Exploring Other Perspectives
You can read the same Vareš ramp up as a warning light. The most pessimistic analysts were already modeling revenue drifting toward about $1.0b and earnings easing to roughly $572.7 million by 2029. That is a very different story compared with the baseline. The latest cash flow news could nudge those views in either direction, so compare both narratives for yourself.
Explore 4 other DPM Metals fair value estimates, including one that suggests it could be worth just CA$59.74.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DPM Metals research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for DPM Metals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DPM Metals' overall financial health at a glance.
Looking For More Investment Ideas Beyond DPM Metals?
If you like the cash generation profile at DPM Metals but want a wider watchlist, the Simply Wall St Screener can help you quickly surface other opportunities that fit your approach without trawling through endless tickers.
- For investors who care most about valuation support, scan a curated set of 5 high quality undervalued stocks that combine quality fundamentals with pricing that may appeal to value focused portfolios.
- If balance sheet strength is non negotiable for you, filter for companies in our list of solid balance sheet and fundamentals (6 results) that can potentially handle tougher operating conditions without stressing their finances.
- When you want ideas that the broader market might be overlooking, broaden your research with a focused 8 high quality undiscovered gems that highlights robust fundamentals in less crowded stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com