
Is Lamb Weston Holdings (LW) Expensive On Its Rebound And Conference Spotlight?
Lamb Weston Holdings (LW) is back on investor watchlists after a sharp share price rebound collided with antitrust litigation concerns, questions over a paused ERP program, and fresh visibility from two upcoming November investor conferences.
The recent 1 month share price return of 29.8% at a last close of US$56.58 has reversed some of Lamb Weston Holdings' longer slide, even though the 1 year total shareholder return is still down 7.6% and the 3 year total shareholder return has fallen 35.7%.
That sharp rebound, alongside a 4.6% 1 day share price return and 5.4% 7 day share price return, appears to align with investors reassessing near term risks around the antitrust litigation, ERP pause, and upcoming conference commentary, rather than indicating any clear shift in the long run record of total shareholder returns.
Spot fresh momentum stories and compare Lamb Weston Holdings to a hand picked 34 high quality undervalued stocks that may offer a different balance between price, earnings and legal or execution risk.Lamb Weston looks like a solid frozen potato player on paper, yet the recent rebound and a reported P/E of about 29.2x raise a sharper question: Are investors paying up too much for that quality?
Most Popular Narrative: 18% Overvalued
The current Lamb Weston Holdings share price of $56.58 sits above the most followed fair value narrative of $48.06. This frames the recent rebound as bumping into valuation discipline rather than resetting it.
The international segment is where the framing has moved the most. Mike Smith attributed EMEA weakness to a slowdown in demand and said the company was “controlling the controllables” while it worked through the Netherlands closures. The call now places the cause on supply. Mike Smith calls the European crop “a tale of two years,” argues that raw potato quality and yield “is likely going to be the limiter,” and says “not all open industry capacity will be used.”
See why 2 investors see Lamb Weston Holdings as 18% overvalued.
Result: Fair Value of $48.06 (OVERVALUED)
Still, the paused ERP rollout and the shifting story around international EBITDA leave live pressure points that could quickly challenge the narrative of Lamb Weston’s current overvaluation.
Find out about the key risks to this Lamb Weston Holdings narrative.
Another View: Cash Flow Signals For Lamb Weston
The most followed narrative pegs Lamb Weston at $48.06 and calls the stock overvalued, yet the SWS DCF model points in the opposite direction. On that measure, the current $56.58 price sits below an estimated future cash flow value of $138.49, which frames Lamb Weston as materially undervalued. Which story feels more convincing to you as an investor sizing position risk?
Look into how the SWS DCF model arrives at its fair value.
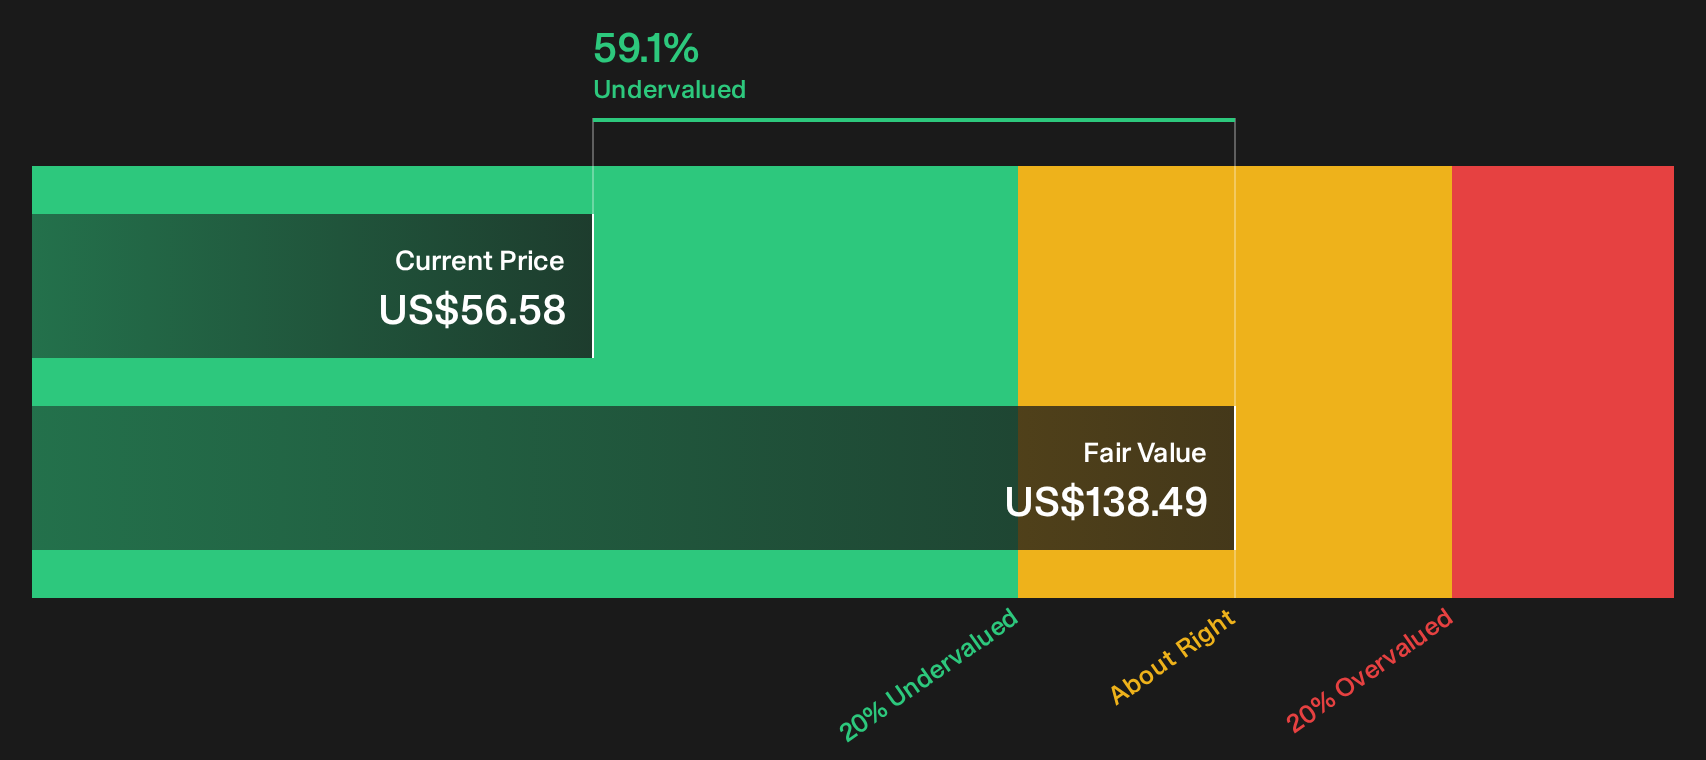
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lamb Weston Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Lamb Weston Holdings can feel confusing. Move quickly from headlines to hard numbers and pressure test your own thesis with the full breakdown of 3 key rewards and 2 important warning signs.
Looking for more Lamb Weston investment ideas?
If Lamb Weston Holdings has sharpened your focus, do not stop here. Broader watchlists often reveal mispriced opportunities that single stock research can miss.
- Zero in on quality at a discount and scan a focused set of value driven opportunities with the 34 high quality undervalued stocks.
- Prioritise resilience and stress test your downside by reviewing companies in the 29 resilient stocks with low risk scores.
- Hunt for future leaders early and see which under the radar businesses surface in the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com