
Tower Semiconductor (TSEM) Stock Looks Fully Priced Despite Its Very Large Run
Tower Semiconductor has delivered a very large 3 year share price gain, yet recent sharp pullbacks now have investors asking whether the current price still lines up with the earnings that support it. With the story shifting from momentum to justification, the focus turns squarely to what the profit line says about valuation today.
- Over the past 3 years, Tower Semiconductor has produced a very large return, which now puts real pressure on its earnings to carry a much bigger share price.
- Recent record profitability and management's push to expand manufacturing capacity under long-term customer contracts may support expectations for stronger earnings over time, which is central to how the stock is being priced.
- Your read on Tower Semiconductor is one view; the desks covering it have another. See what analysts think Tower Semiconductor's shares could be worth.
The stock's next move may depend on whether Tower Semiconductor's current earnings justify the valuation investors are being asked to pay today.
If you want to test the same earnings driven valuation question beyond Tower Semiconductor, line it up against a wider field using the 34 high quality undervalued stocks.
Does Tower Semiconductor Look Pricey on Earnings?
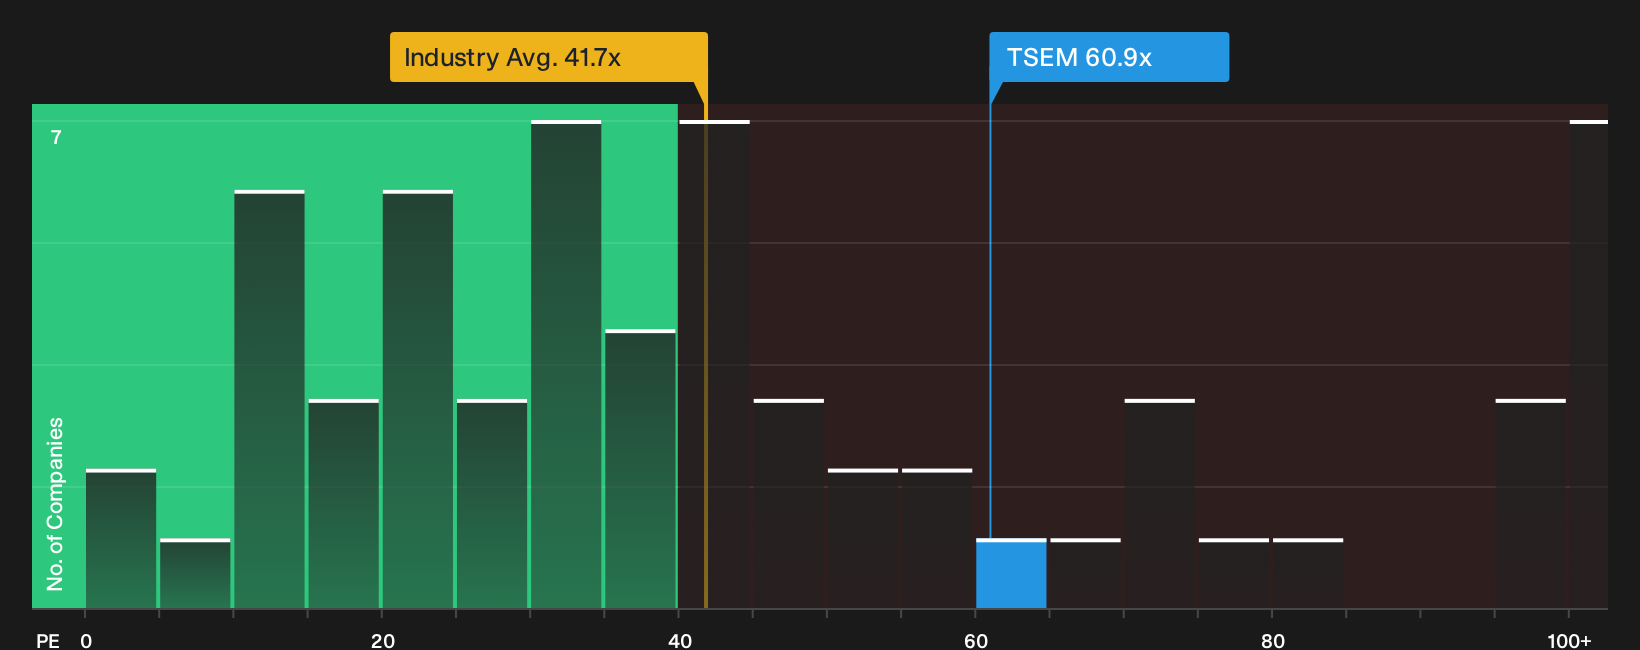
The P/E ratio is a useful lens for Tower Semiconductor because earnings have become a key reference point for how the business is being priced. On this measure, the stock trades at about 60.9x earnings, compared with roughly 41.7x for the broader semiconductor industry. That also sits above a peer group average of around 46.8x, which means buyers today are paying a steeper price for each dollar of Tower Semiconductor profit than for many comparable chip manufacturers.
A tailored fair value multiple for the company sits below the current 60.9x level, so the shares screen as overvalued on this framework. Because management is reporting record quarterly results and stronger visibility on long term customer contracts, the market appears willing to keep that premium in place despite the richer P/E tag relative to industry and peers. Explore the numbers behind Tower Semiconductor's P/E valuation.
The Tower Semiconductor Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St extend the Tower Semiconductor valuation question by spelling out the specific future paths for growth, margins and earnings that would need to play out for the stock to be worth meaningfully more or less than it is today, and they sit on the Community page. Instead of leaving you with a single ratio or model output, they unpack what future that number assumes so you can monitor whether those conditions actually show up.
One of the top community narratives on Tower Semiconductor: 50% undervalued
"The main thing that has to go right is execution on the multi-year capacity build in Japan and existing fabs so that contracted silicon photonics demand and 300mm RF and power design wins translate into sustained high margin wafer output…"
Discover why this Narrative puts Tower Semiconductor at 50% undervalued.
One more Tower Semiconductor signal to check before you decide
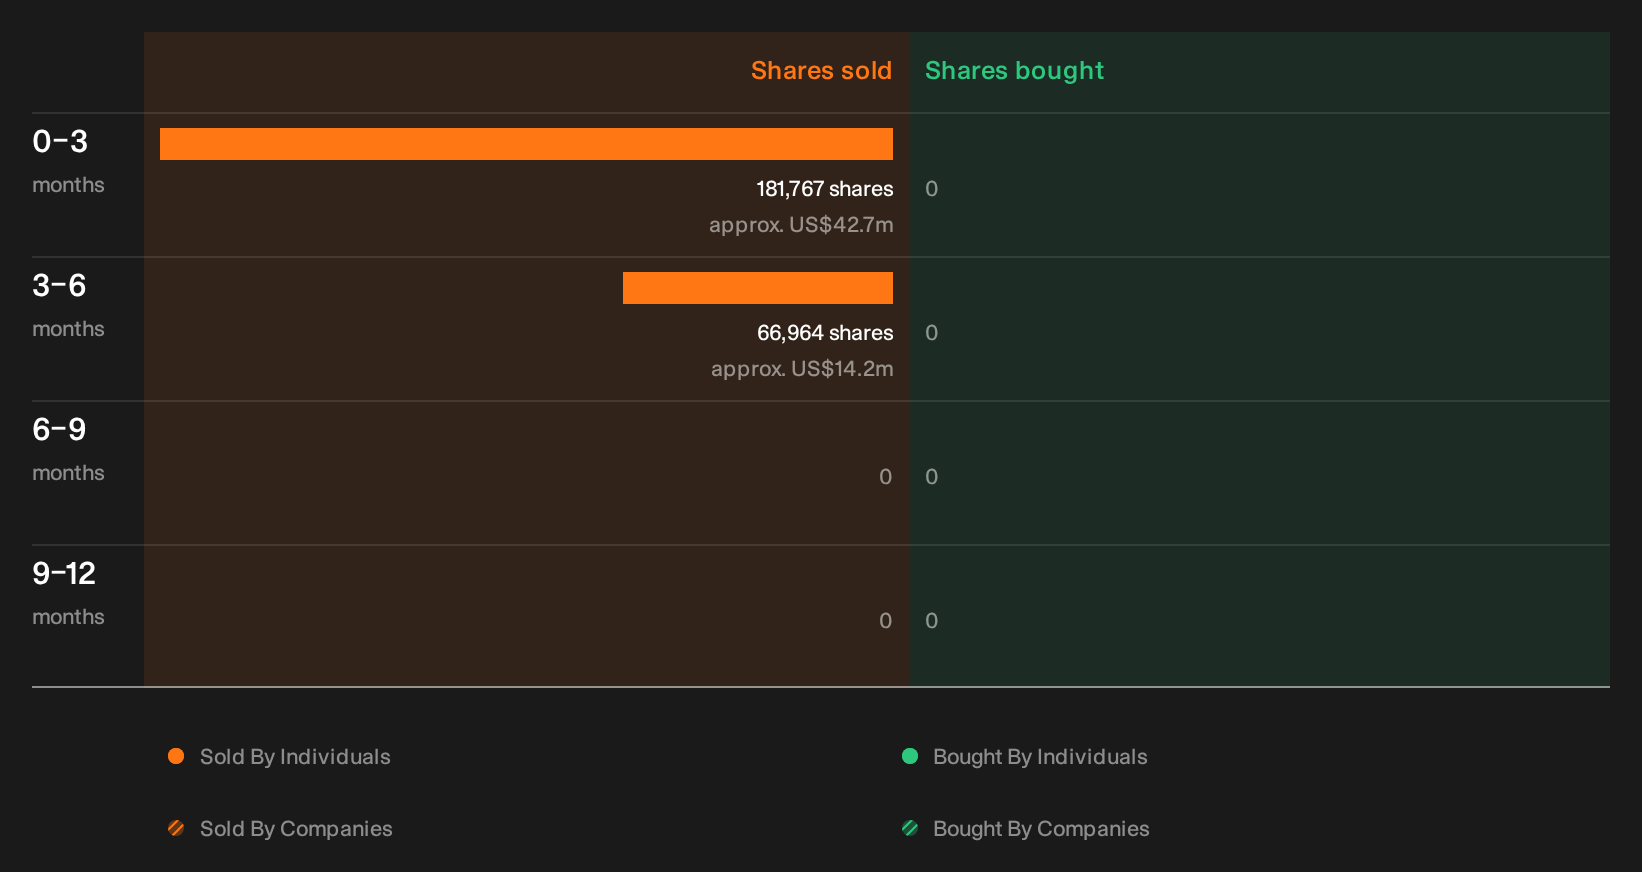
Valuation only tells part of the story, and recent trading by Tower Semiconductor insiders is a separate clue that our checks have picked up. However, the specific sellers, sizes and possible read-throughs are for you to inspect. See the recent insider selling flagged for Tower Semiconductor.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com