
NGK (TSE:5333) Faces An 8% Fair Value Gap On Strong Half Year Earnings
NGK (TSE:5333) just posted half year results that quickly caught investor attention, with sales of ¥371,306 million and net income of ¥60,800 million reported for the period to September 30, 2026.
The share price reaction has been sharp in the short term, with NGK up 10.95% on a 1 day share price return and 11.84% over 7 days. This is despite the 30 day share price return being down 9.00% and the 90 day share price return being down 8.66%, while longer term total shareholder returns of 100.75% over 1 year and 202.64% over 5 years point to momentum that has been building over time.
Scan how NGK’s latest earnings surge compares with peers by reviewing a curated group of 15 high quality undervalued stocks that also pair solid cash generation with balance sheets that investors often watch closely.
After that sharp move and with NGK trading at ¥5,118 against analyst targets near ¥6,798, the gap between price and valuation work is now hard to ignore. Where does fair value really sit within that range?
Preferred P/E of 14.9x for NGK: Is it justified?
On earnings, NGK changes hands at a P/E of 14.9x, which leaves the valuation sitting between a peer premium and an industry discount at the latest close of ¥5,118.
P/E compares the share price to earnings per share, so it reflects how much investors are willing to pay for each unit of current profit. For a business like NGK that operates across Environment, Digital Society, and Energy & Industry segments, this lens links the recent 83% earnings growth with what the market is prepared to pay for that profit stream.
The P/E of 14.9x is below the peer average of 17.3x, which suggests the market is assigning a lower earnings multiple than comparable stocks even though NGK has high quality earnings and profit margins that are currently stronger than a year ago. In contrast, the P/E of 14.9x sits above the JP Machinery industry average of 12.5x. The company is forecast to grow earnings by 3.5% per year with a forecast Return on Equity of 11.3%, so the premium to the sector implies investors are still willing to pay up for this profile. The estimated fair P/E of 16.5x is higher than the current 14.9x, which signals that the valuation multiple could reasonably move closer to that level if the market keeps pricing NGK in line with that fair ratio model.
Explore the SWS fair ratio for NGK.
Result: Price-to-earnings of 14.9x (ABOUT RIGHT)
Still, the narrative around NGK can shift quickly if demand softens across its Environment or Digital Society units, or if analyst targets begin to reset lower.
Find out about the key risks to this NGK narrative.
Another view on NGK’s value
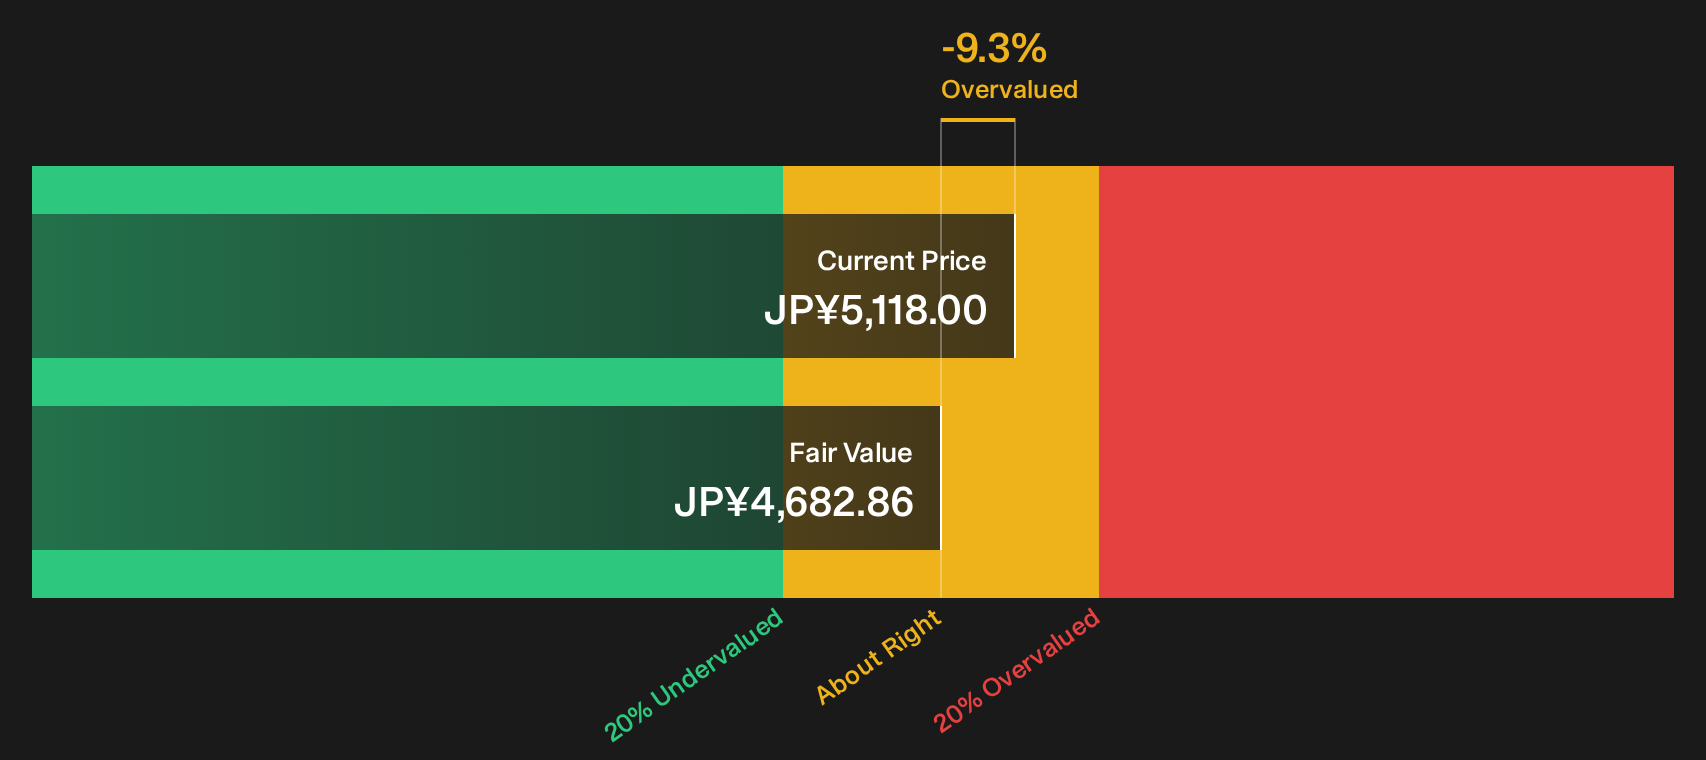
One model says NGK looks reasonably priced on a 14.9x P/E, yet the SWS DCF model tells a different story. On that cash flow view, fair value sits near ¥4,682.86 while the market price is ¥5,118, which points to an overvalued stock. Which lens do you trust more for your own process?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NGK for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With NGK positioned between mixed valuation signals and a punchy share price move, you can step in quickly and stress test the story yourself using 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond NGK?
If NGK has sharpened your focus, do not stop there. Broader research across high quality opportunities can keep your watchlist fresh and your thinking ahead of the crowd.
- Target resilience first and stress test your downside by scanning a 22 resilient stocks with low risk scores that filters for businesses with sturdier profiles.
- Hunt for quality at a sensible entry point by reviewing a 74 high quality undiscovered gems that surfaces underfollowed companies with strong fundamentals.
- Anchor your research on financial strength and check a list of solid balance sheet and fundamentals (22 results) where balance sheets and core performance line up more cleanly.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com