
Moog (MOG.A) As Defense Spending Drives The Narrative, Is The Valuation Still Reasonable?
Moog stock: recent performance snapshot
Moog (MOG.A) has recently drawn investor attention after a strong year to date, with the share price at $356.65 and total return over the past year of 73.4%.
The stock performance has been mixed in the shorter term, with the price up 1.7% over the past day but down over the past week, month and past 3 months.
Recent moves show Moog losing some short term momentum despite a strong long haul, with the share price weakening over the past month even as the 1 year total shareholder return sits at 73.4% and the 5 year figure at 350.35%.
This pattern often points to investors reassessing how much future growth or risk is already reflected in the current US$356.65 share price. This can be especially relevant after a multi year run where total shareholder returns have been very strong and expectations can become more sensitive to new information or sentiment shifts.
Scan for other industrial and aerospace stocks showing similar multi year strength to Moog with the curated 34 high quality undervalued stocks, which still screen well on quality metrics.
Moog looks like a high quality aerospace and industrial controls business with strong recent returns, yet the share price has cooled in the short term. Does that give you a fair entry point, or does it suggest a stretched valuation?
Most Popular Narrative: 20% Undervalued
On the most followed view of Moog, the current $356.65 share price sits below an implied fair value of $446.40 that is built from detailed revenue, margin and discount rate assumptions.
Moog is positioned to benefit from a sustained increase in global defense spending, with significant order backlog and direct exposure to U.S., NATO, and Indo Pacific modernization programs. These factors are likely to drive multi year revenue growth and increased earnings stability.
See why 23 investors see Moog as 20% undervalued.
Result: Fair Value of $446.40 (UNDERVALUED)
Still, the Moog story can break if tariff costs bite harder than expected or if the next phase of efficiency gains proves much tougher to deliver.
Find out about the key risks to this Moog narrative.
Another view on Moog valuation
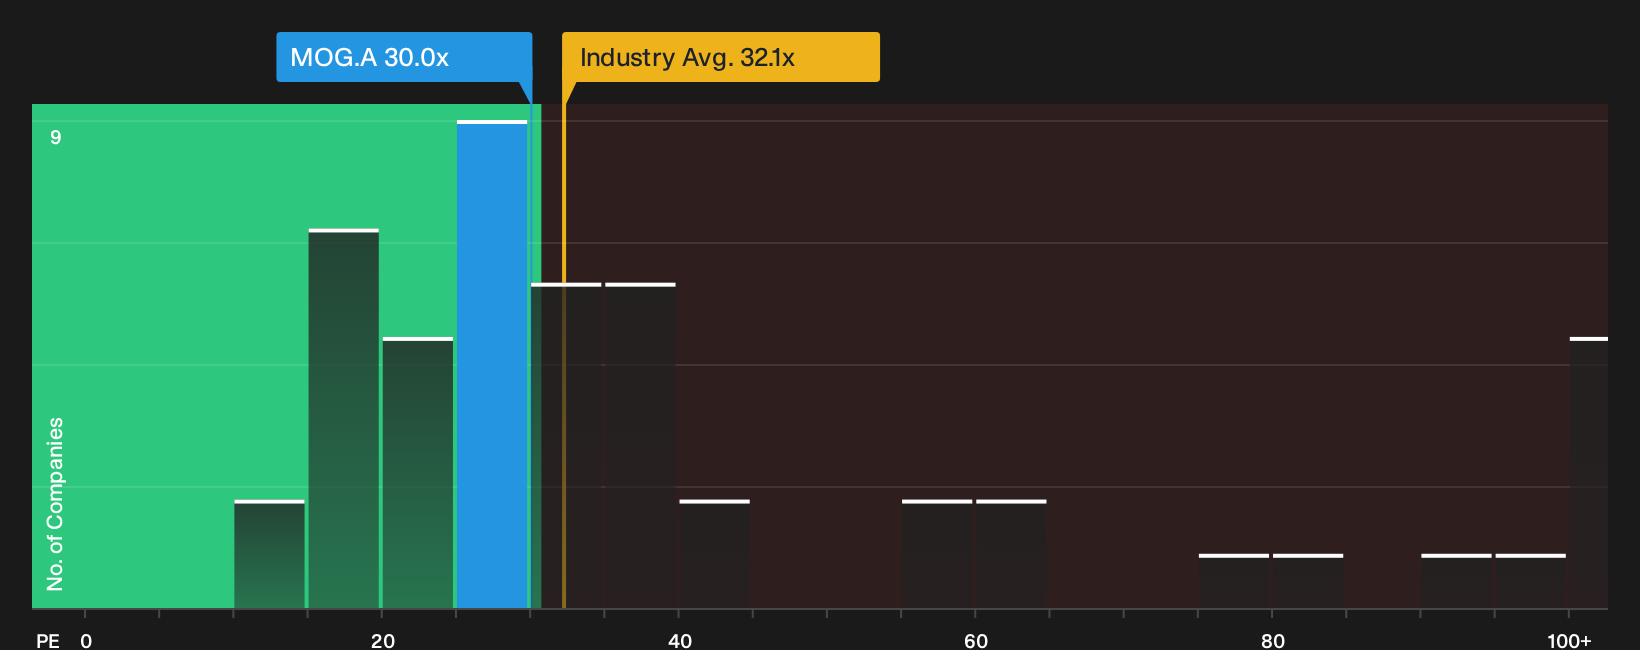
The narrative above leans on cash flow forecasts and a fair value of $446.40. A simple earnings multiple sends a cooler signal. Moog trades on a P/E of 30x, while the fair ratio is 19.3x, the US Aerospace & Defense group averages 32.1x, and close peers sit near 25.7x.
That mix points to a stock that screens expensive versus its own fair ratio and against similar companies, even though it is slightly cheaper than the wider industry. For anyone weighing Moog, the question is whether current quality justifies paying above that 19.3x anchor.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across Moog's recent returns can make sentiment hard to read. It helps to pull up the data yourself and pressure test the bullish points that investors are watching in real time by reviewing the 3 key rewards.
Looking for more Moog sized investment ideas?
If Moog has sharpened your focus, do not stop here. The right watchlist can reshape how you spot opportunities long before they hit headlines.
- Target income first and let price action be the second decision by reviewing a curated pool of 4 dividend fortresses built around resilient cash payouts.
- Hunt for quality at a sensible entry point by scanning a 34 high quality undervalued stocks that combine strong fundamentals with prices that still look reasonable.
- Cut portfolio stress and smooth out the ride by focusing on a 29 resilient stocks with low risk scores that screen well on balance sheet strength and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com