
Archrock (AROC) Reports Q3 2026 Results, Is The 32% Undervalued View Convincing?
Archrock (AROC) just put fresh numbers on the table, reporting third quarter 2026 results that featured US$370.81 million in revenue, US$84.47 million in net income, and earnings of US$0.48 per share from continuing operations.
At a share price of US$30.34, Archrock has given investors a 13.93% year to date share price return. The 1 year total shareholder return of 22.53% and very large 5 year total shareholder return of about 4.4x point to momentum that has cooled in recent months but remains strong over a longer horizon.
Scan how Archrock compares to a curated group of income and infrastructure plays by reviewing the 4 dividend fortresses that currently meet strict payout and balance sheet criteria.
After a flat few months but a strong multiyear run, Archrock now trades well below the average analyst target and at a premium to some intrinsic estimates. So where does fair value really sit in that spread?
Most Popular Narrative: 32% Undervalued
Archrock's most followed narrative pegs fair value around $44.88 a share, well above the recent $30.34 price. As a result, the gap between physics driven compression demand and current trading levels features heavily in how some investors frame the story.
Archrock, Inc. (NYSE: AROC), a leading outsourced natural gas compression service provider in the United States, has built a unique moat to meet this structural demand with its 4.5 million horsepower (HP) capacity, electric motor drive (EMD) vision, and strategic acquisitions. Archrock's compression services and aftermarket maintenance operations have transformed the company into an infrastructure monopoly that isolates itself from commodity price volatility, generating predictable cash flows and protected by contracts spanning decades.
See why 43 investors see Archrock as 32% undervalued.
Result: Fair Value of $44.88 (UNDERVALUED)
Still, Archrock’s story leans heavily on compression equipment supply constraints and long dated contracts, so any easing in engine lead times or contract repricing could weaken that thesis.
Find out about the key risks to this Archrock narrative.
Another View: What Archrock's DCF Signals
While the leading community narrative for Archrock leans on a fair value of $44.88, Simply Wall St's own DCF model lands somewhere very different. On that approach, estimated future cash flows point to a value of $25.58, which is below the current $30.34 share price and frames Archrock as overvalued on that metric. So which story do you trust when the cash flow math and the crowd pull in opposite directions?
For a closer look at the cash flow assumptions that sit behind that result, including discount rates and terminal values, Look into how the SWS DCF model arrives at its fair value.
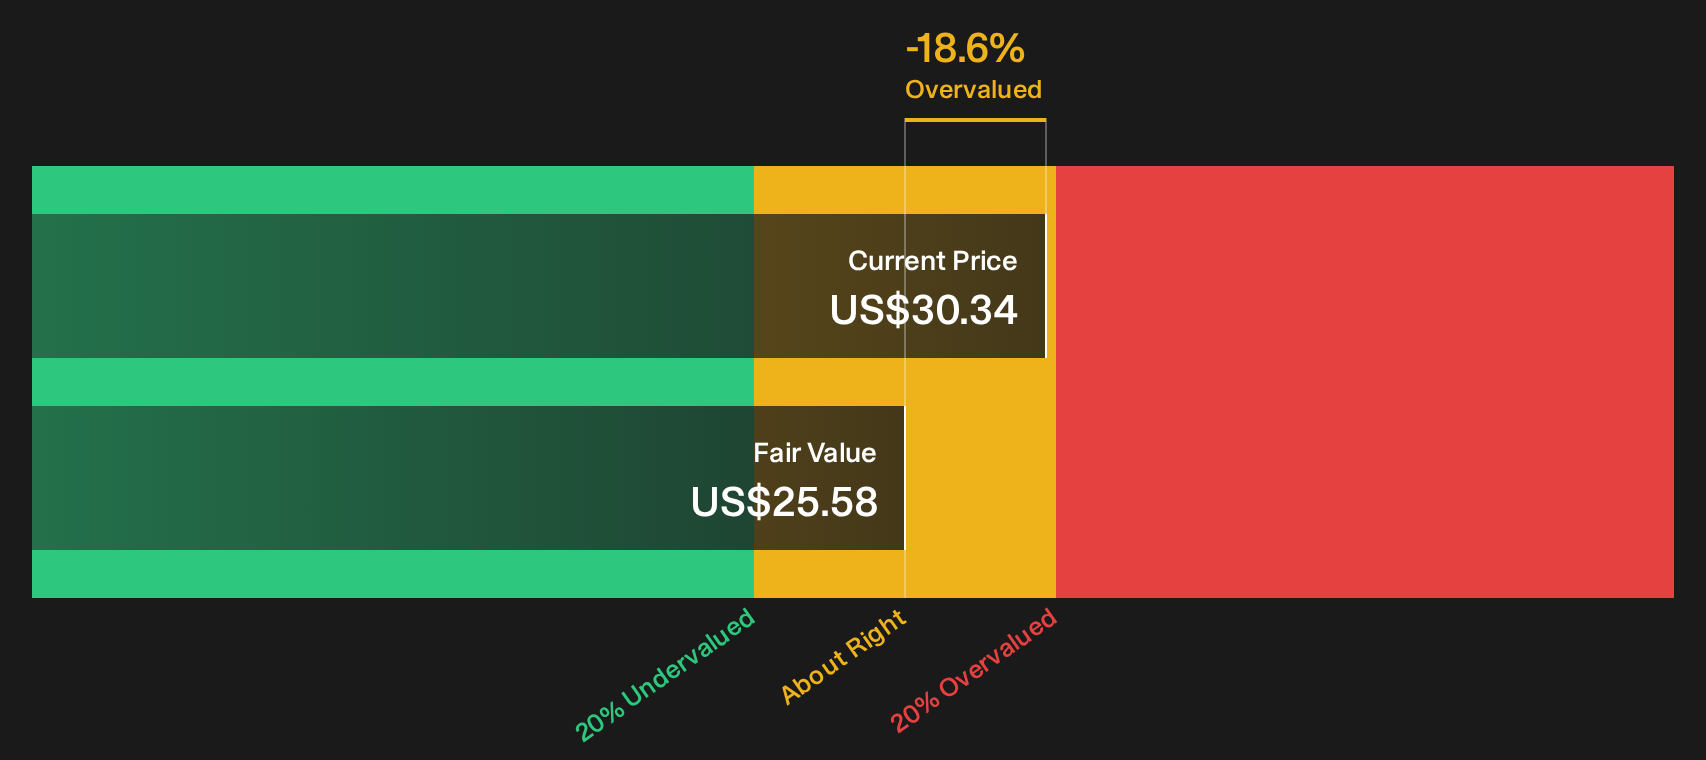
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Archrock for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed on Archrock after all that, or leaning one way already? Move quickly to compare the potential upside and downside and see the 5 key rewards and 2 important warning signs.
Looking for more Archrock sized investment ideas?
If Archrock has sharpened your thinking, do not stop here. Use the Simply Wall Street Screener to spot fresh opportunities before everyone starts talking about them.
- Target resilient compounding potential by reviewing the 34 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect their underlying strength.
- Prioritise capital protection first and scan the 29 resilient stocks with low risk scores to focus on businesses flagged with more defensive risk profiles.
- Hunt for off the radar opportunities by checking the 19 high quality undiscovered gems that pair solid financials with relatively light market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com