
How Mixed Earnings Will Impact Chipotle Stock Investors
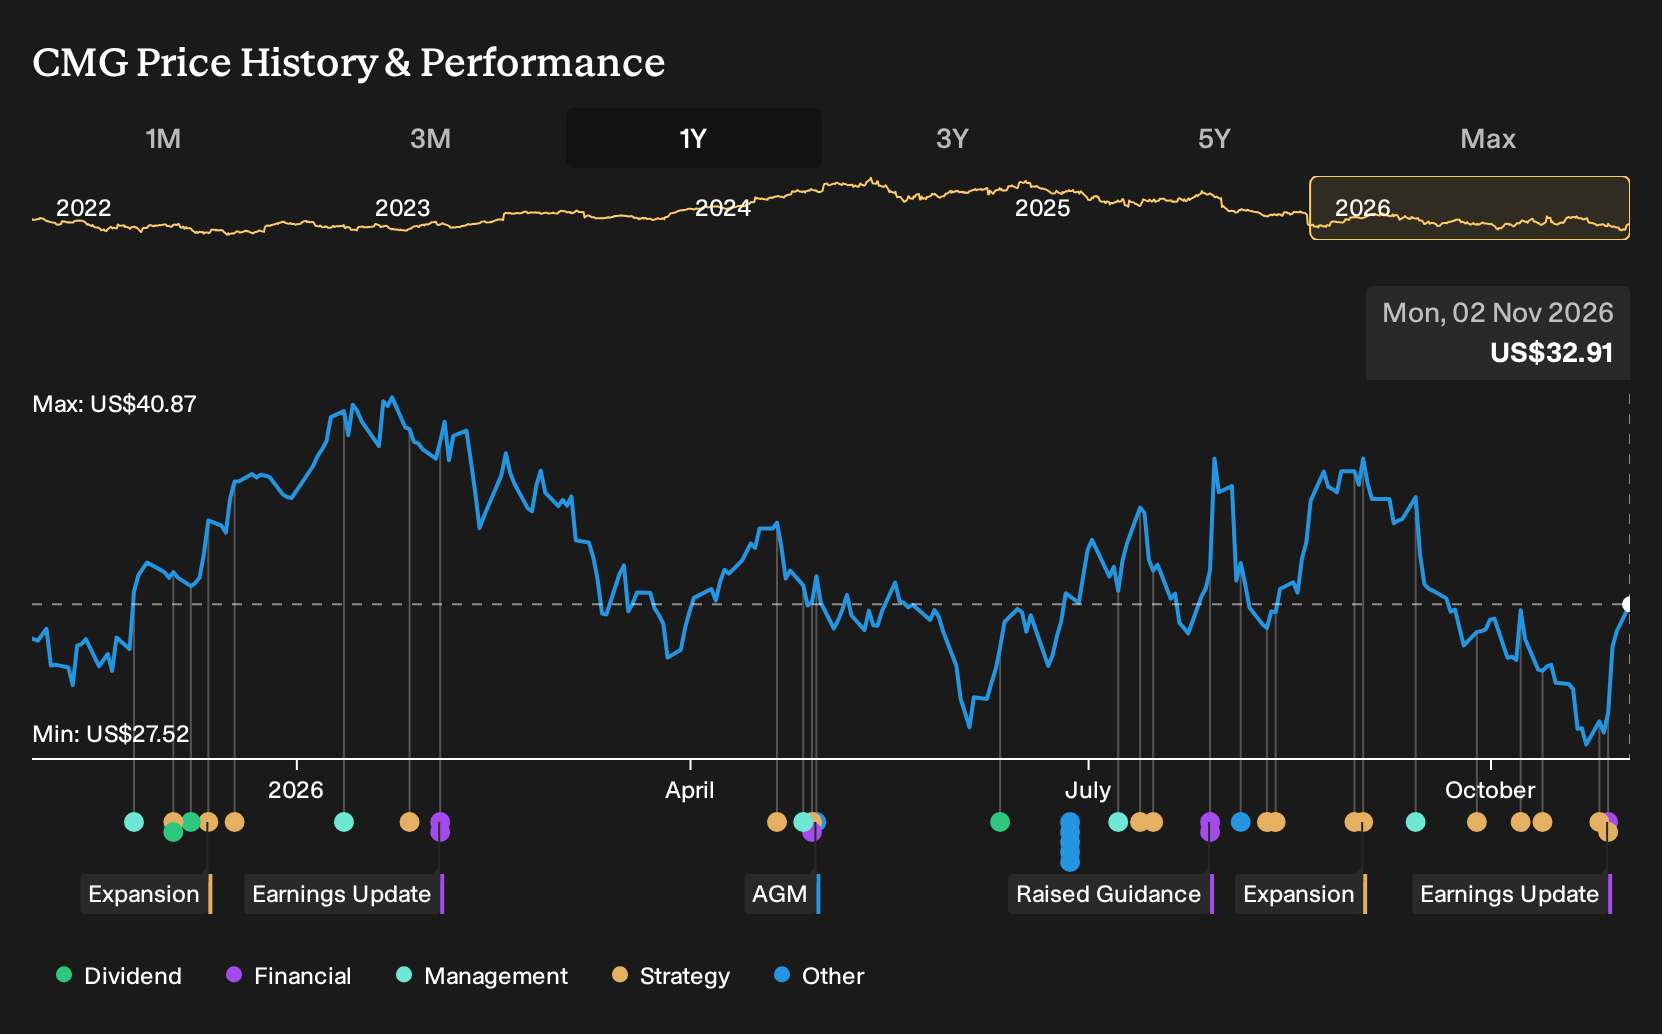
- Chipotle Mexican Grill reported higher third quarter and nine month revenue in 2026 but lower net income and earnings per share compared with 2025, and it also confirmed plans to open hundreds of new restaurants in 2027.
- The business is leaning on its Recipe for Growth plan, which combines aggressive U.S., Canadian and international expansion with limited time items like returning Smoked Brisket to support customer traffic and menu attachment.
- The focus now is on how Chipotle Mexican Grill's investment narrative is shaped by this mix of softer earnings and large scale new openings.
Scan beyond Chipotle Mexican Grill and compare its growth and expansion story with a curated group of restaurant and consumer stocks screened for 19 high quality undiscovered gems.
Chipotle Mexican Grill Investment Narrative Recap
For a shareholder in Chipotle Mexican Grill, the core belief is that consistent restaurant traffic, efficient operations and disciplined unit growth can offset near term pressure on earnings. The latest quarter fits that tension. Revenue reached about US$3.3b for the first nine months of 2026, yet net income and earnings per share moved the other way.
The key short term catalyst is still traffic growth driven by menu news, loyalty and equipment upgrades. Softer earnings and compressed margins keep the biggest risk front and center. If consumer spending stays weak or food safety headlines linger, comparable sales and profit recovery could take longer. The potential impact here is material.
The expansion plan for 2027 is the announcement that really matters in this context. Management is targeting 340 to 360 new restaurants in the U.S. and Canada plus 15 to 25 locations abroad. That is a heavy lift on staffing, supply chain and capital allocation while margins are under pressure.
For you as an investor, the question is whether Chipotle Mexican Grill can execute that build out without letting store level profitability erode further. Upside potential rests on new units, digital ordering and catering gradually supporting earnings. Execution missteps, or slower than expected payback on those 2027 openings, remain a clear risk to that thesis.
Chipotle Mexican Grill's current analyst narrative points to revenues of US$16.5b and earnings of US$2.0b by 2029, built on 10.0% yearly revenue growth and an earnings increase of about US$0.6b from US$1.4b today.
Uncover how Chipotle Mexican Grill's fair value points to a 30% potential upside relative to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view fixates on margin pressure rather than restaurant openings. The lowest analysts were already assuming revenue of about US$16.3b and earnings of roughly US$1.8b by 2029, below the broader Chipotle Mexican Grill consensus. Those forecasts came before this latest earnings and expansion update, so you should expect some opinions to shift and you may want to explore several viewpoints.
Explore 7 other Chipotle Mexican Grill fair value estimates, including one that suggests as much as 15% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Chipotle Mexican Grill research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Chipotle Mexican Grill. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Chipotle Mexican Grill's overall financial health at a glance.
Looking For More Investment Ideas Beyond Chipotle Mexican Grill?
Once you have a view on Chipotle Mexican Grill, it can help to widen the lens and compare it with other businesses that fit different risk, income and quality profiles. The Simply Wall St Screener lets you do that in a structured way so you are not just reacting to one headline or one earnings report.
- If capital preservation sits high on your priority list, start with a group of companies screened as 29 resilient stocks with low risk scores that may better align with a cautious approach.
- For investors who care most about resilient balance sheets and fundamentals, you can filter for businesses in the list of solid balance sheet and fundamentals (24 results) to see which ones merit a closer look.
- If you are hunting for underfollowed opportunities with strong metrics, use the 19 high quality undiscovered gems and see which lesser known stocks justify a spot on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com