
uniQure (QURE) Stock Looks Fully Priced Against Its Book Value
uniQure has seen large swings in its share price in recent years, which puts fresh attention on a simple question for investors who care about balance sheet strength. Is the current US$22.97 stock price sensibly anchored to the value of the assets uniQure carries on its books, or has trading drifted away from what its book value can support?
- Over the past 3 years, uniQure has delivered a very large share price gain of about 2.8x. That puts a lot of weight on whether the underlying equity base can justify that kind of move.
- The business leans heavily on research driven assets and future cash flows. As a result, the quality and durability of those investments can influence how much confidence investors place in the book value figure today.
- There is a second opinion on uniQure worth weighing. See what analysts think uniQure's shares could be worth.
The issue now is whether uniQure's current market value lines up with what investors are effectively paying for on its balance sheet once book value is taken into account.
If you are evaluating whether uniQure's US$22.97 share price aligns with its equity base, it can be useful to compare that question across 34 high quality undervalued stocks.
Is uniQure Getting Expensive on Book Value?
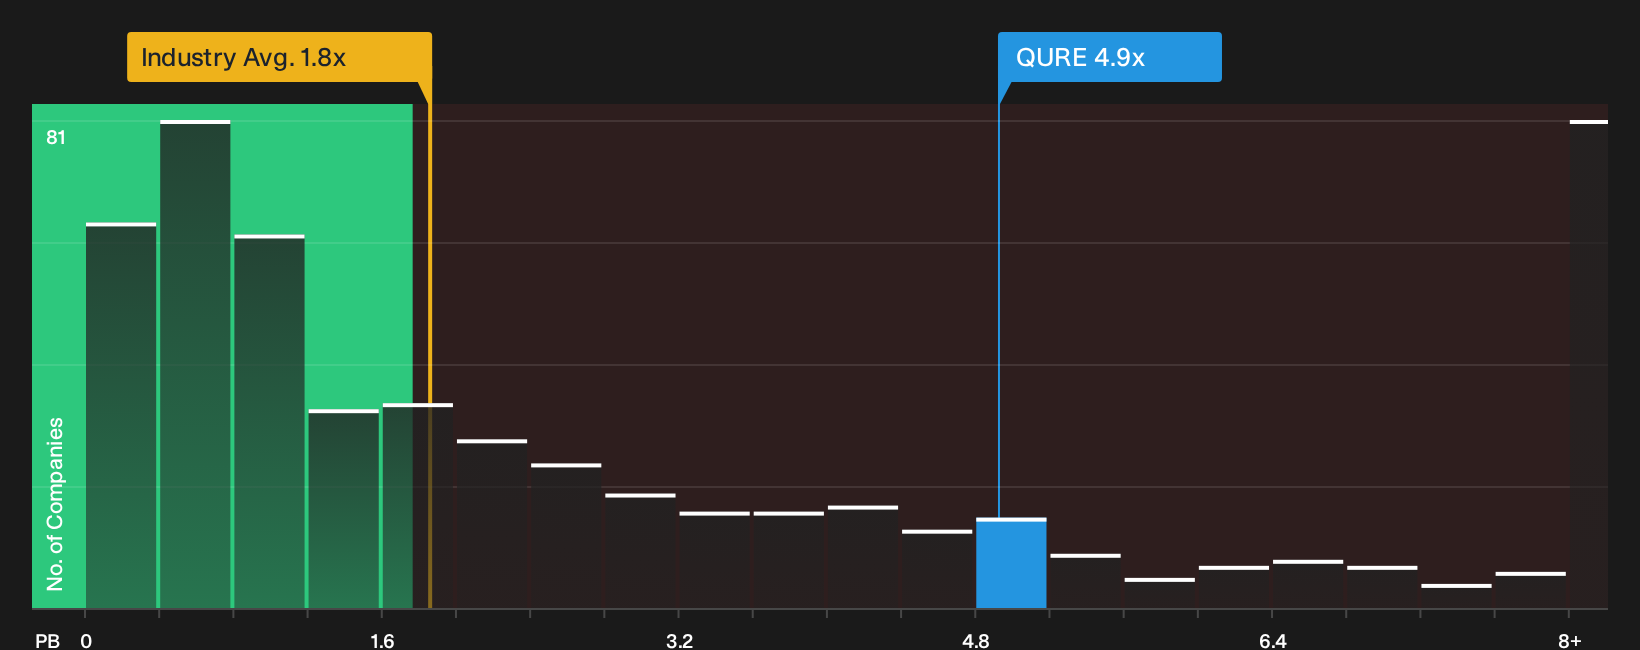
The P/B ratio suits uniQure because the business still leans heavily on its balance sheet rather than on established profits. At the current price, the stock trades on a P/B of about 4.9x, compared with an industry average near 1.8x for biotechs. That is a sizeable premium to the sector’s typical relationship between market value and net assets.
Against that backdrop, the market is asking you to pay a much higher price per dollar of equity for uniQure than for the average biotech peer, which points to the shares appearing overvalued on this simple yardstick. To judge whether that premium feels comfortable, you would need to weigh how much confidence you have in the quality of uniQure’s research portfolio, the sustainability of its funding, and the risks around future cash flows that are not yet reflected cleanly in book value. Explore the numbers behind uniQure's P/B valuation.
The uniQure Narrative: What Would Justify Today's Price?
Narratives pick up where uniQure's price to book puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for today’s valuation to look either stretched or conservative. Each scenario ties a fair value estimate to a clear storyline about uniQure's potential catalysts and key risks, so you can track over time which version of events the business is actually following on Simply Wall St's Community page.
One of the top community narratives on uniQure: 63% undervalued
"The company’s financial moves, including reducing cash burn and strengthening the balance sheet, provide resilience and flexibility to support pipeline advancement..."
Discover why this Narrative puts uniQure at 63% undervalued.
One more uniQure check that sits alongside the book value story
Balance sheet and price ratios only go so far, because there is a separate lens that compares where uniQure trades today with where professional analysts expect the business to be a few years from now. Explore where analysts expect uniQure to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com