
T Mobile (TMUS) Stock May Be A Bargain After Raised Outlook
T-Mobile US has seen its share price move around over the past few years, and that raises a straightforward question for you as an investor: Is the current valuation of T-Mobile US stock properly grounded in the earnings the business is generating today?
- Over the past 5 years the stock has returned 39.4%, which puts quite a bit of weight on whether the current earnings power can support that journey so far.
- Recent reports on cybersecurity upgrades, network performance and new fiber offerings may support expectations around future profitability and the timing of cash flows, which all feed back into how much investors are prepared to pay for each dollar of earnings.
- Your read on T-Mobile US is one view; the desks covering it have another. See what analysts think T-Mobile US's shares could be worth.
The issue now is whether T-Mobile US stock at around US$160 per share is appropriately aligned with what its earnings justify.
If you are weighing T-Mobile US against other telecoms on earnings and cash flow resilience, it can help to line it up next to 29 resilient stocks with low risk scores.
Does T-Mobile US Look Undervalued on Earnings?
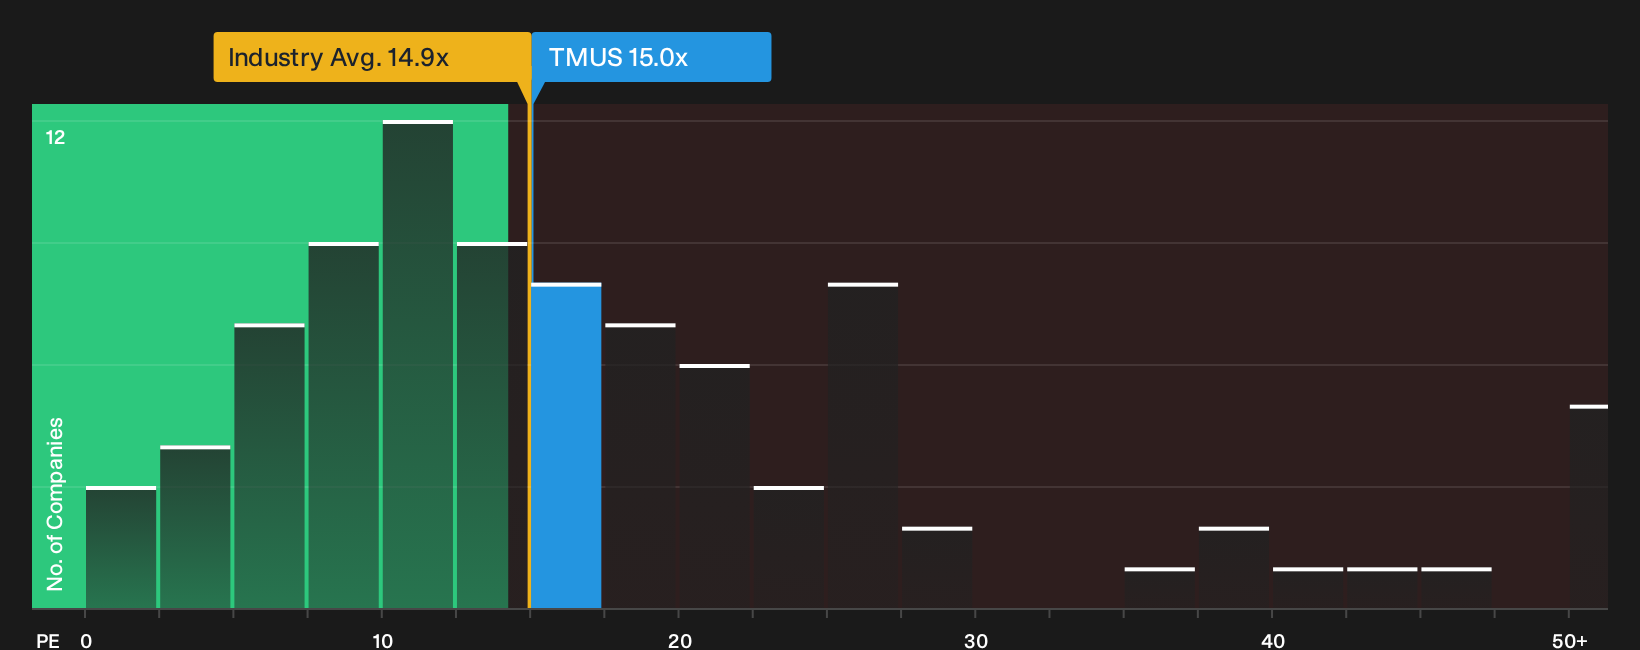
The P/E ratio is a useful shorthand for T-Mobile US because earnings are now a central focus for how investors value large wireless carriers. At around 15.0x earnings, the stock trades very close to the Wireless Telecom industry average of about 14.9x. This frames it as broadly in line with the sector on this single measure.
Against a broader peer set that averages roughly 33.6x, T-Mobile US changes hands at a much lower multiple, so the market is not pricing it like the higher rated telecom and adjacent players. A fair P/E based on a more tailored model that considers T-Mobile US specific growth profile, margins, size and risk comes out above the current ratio. This points to the shares screening undervalued on this framework. Because the company recently reported higher earnings and raised its profitability outlook, that discount on P/E may catch the eye of investors comparing it with other telecom stocks. Explore the numbers behind T-Mobile US's P/E valuation.
The T-Mobile US Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St's Community page pick up where the T-Mobile US valuation puzzle leaves off, by spelling out which future paths for growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than it does today. Each one links its number back to a clear view on how T-Mobile US' growth, profitability and risk profile could evolve, which you can revisit as fresh information comes through.
One of the top community narratives on T-Mobile US: 30% undervalued
"Persistent focus on higher value customers, shown by port-in ARPAs that are around 20% above port-out levels and a majority of new accounts choosing premium plans…"
Discover why this Narrative puts T-Mobile US at 30% undervalued.
T-Mobile US valuation still leaves one crucial angle unexplored
The current price tag on T-Mobile US only tells part of the story, because our broader checks also flag specific concerns that investors may want to weigh carefully before leaning on the earnings multiple. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com