
VICI Properties (VICI) Stock Looks Undervalued After A $2 Billion Buyback
VICI Properties has produced a 5 year return of 11.5%. The real discussion today is whether that track record and the latest newsflow are enough to justify the current earnings multiple around US$25 a share. With the stock experiencing shorter term declines this year, investors are increasingly asking how firmly its price is anchored to the cash it earns from its casino and entertainment leases.
- Over 5 years the stock has returned 11.5%. This puts real weight on the question of whether long term holders are still paying a sensible price for each dollar of profit the real estate investment trust generates.
- Recent headlines around a 55.1% drop in funds from operations tied to expected credit loss charges and the launch of a US$2b share buyback can both affect how sustainable earnings look and how much cash is left to support growth or distributions.
- The analysts covering VICI Properties have run their own numbers. See what analysts think VICI Properties's shares could be worth.
The issue now is whether VICI Properties' current share price is adequately supported by its earnings power once these developments are factored in.
For readers comparing VICI Properties with other income-focused opportunities, it can be useful to evaluate it alongside a curated list of 4 dividend fortresses.
Is VICI Properties Still Cheap on Earnings?
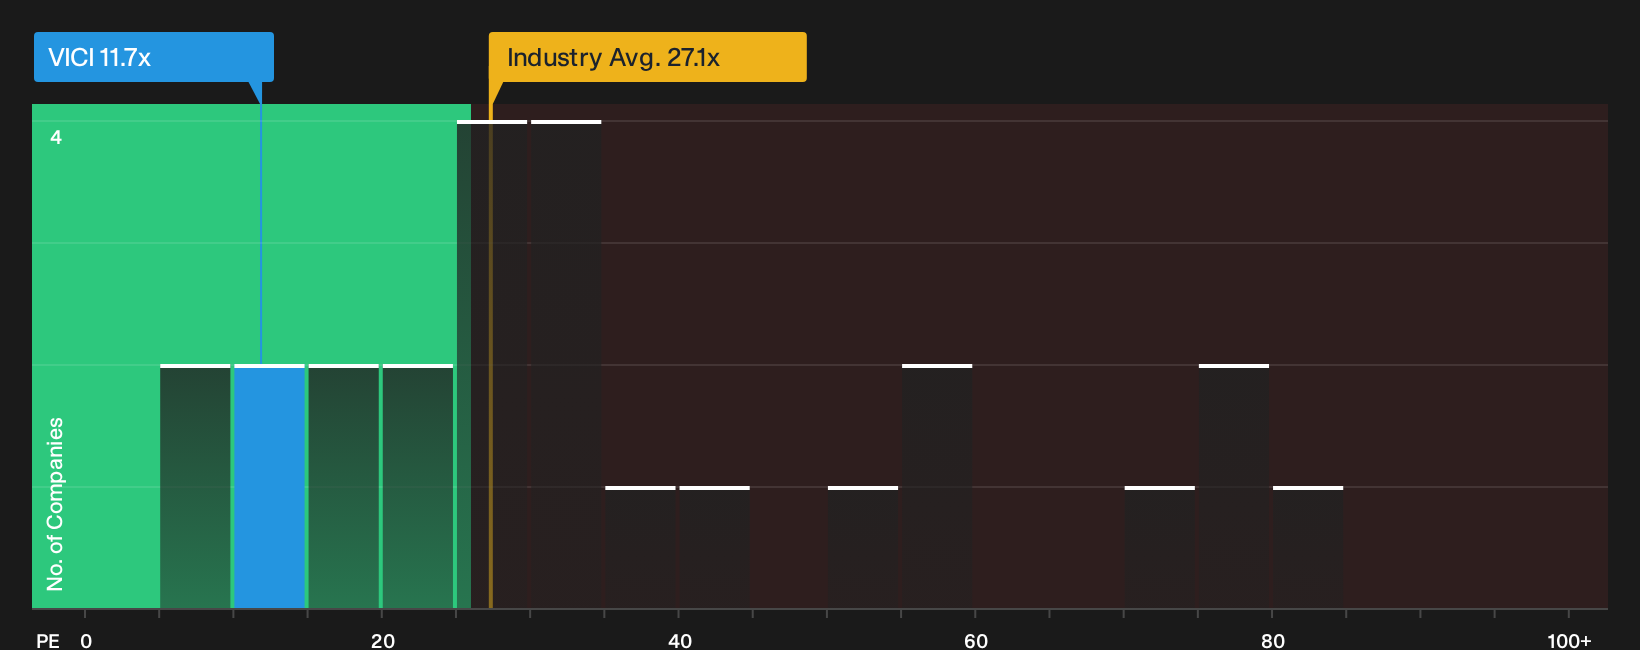
A P/E lens suits VICI Properties because earnings remain a central yardstick for how well its long lease portfolio converts rent into profit. On this measure, the stock trades on a P/E of about 11.7x compared with roughly 16.2x for the wider Specialized REITs group and a peer average near 36.6x. That is a wide gap to both the sector and directly comparable businesses.
The fair P/E that would be expected for VICI Properties, based on its sector, risk profile and cash generation, screens higher than where the shares change hands today, so the model points to the stock being undervalued on earnings. Because the recent 55.1% fall in reported FFO was driven by expected credit loss charges rather than a collapse in rent collection, the current discount persists despite the headlines. For anyone comparing income options, the key question is whether those charges and tenant concentration risks justify such a low earnings tag or whether the present multiple overcompensates for them. Explore the numbers behind VICI Properties's P/E valuation.
The VICI Properties Narrative: What Would Justify Today's Price?
Narratives on VICI Properties pick up where the P/E puzzle leaves off by spelling out which paths for growth, margins and cash generation would need to play out for the stock to look materially cheaper or more expensive than it does now. Each narrative links its number to a clear view on how VICI Properties' earnings profile and risk balance might evolve, giving you something concrete to test as fresh information comes through.
One of the top community narratives on VICI Properties: 40% undervalued
"From these simulations we can extrapolate that there is between ~50-80% probability of VICI being undervalued..."
Discover why this Narrative puts VICI Properties at 40% undervalued.
One more VICI Properties question before you move on
The current numbers tell you what VICI Properties looks like today, but analyst expectations for where rent, profits and cash flows might head over the next few years give you a different lens to compare with today's valuation. Explore where analysts expect VICI Properties to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com