
Adaptive Biotechnologies (ADPT) Stock Looks Close To Fair Value Today
Adaptive Biotechnologies has delivered a very large 3 year share price gain, which puts a spotlight on whether the current US$25.06 level is backed up by the cash the business can generate over time. After that kind of move, the key issue for you is whether the recent price puts too much, too little, or just enough weight on its future cash flows.
- The stock is up about 7x over the past 3 years, which means even small shifts in cash flow expectations can have a big effect on whether this valuation holds up.
- The company’s model, which converts immune system data into recurring testing and software revenue, may support a cash flow profile that is very sensitive to scale and execution on long term contracts.
- Prefer to judge Adaptive Biotechnologies on sales? See why Adaptive Biotechnologies's 13.0x P/S tells a different valuation story.
The issue now is whether Adaptive Biotechnologies’ current share price is adequately supported by the cash flows implied in its intrinsic value estimate.
If you want a wider starting point for ideas built around cash flow and valuation, a focused screen of 34 high quality undervalued stocks can help frame what else is out there.
Where Does Adaptive Biotechnologies Sit on Cash Flow?
The Discounted Cash Flow (DCF) model here is built around where free cash flow can realistically land over the next decade. Adaptive Biotechnologies is currently working from a last twelve month free cash flow loss of $26.74 million, so the whole exercise hinges on the view that cash generation can move into positive territory and then build from there.
Analysts feeding this DCF framework are expecting free cash flow in the $40 million to $260 million range across the coming years, with growth front loaded as the business scales and then easing toward more stable expansion. When those future cash flows are brought back to today and compared with the traded price of $25.06, the model suggests the implied intrinsic value is broadly in line with where the stock is currently changing hands. Find out what Adaptive Biotechnologies could be worth using our Discounted Cash Flow (DCF) estimate.
The Adaptive Biotechnologies Narrative: What Would Justify Today's Price?
Narratives pick up where the valuation puzzle leaves off for Adaptive Biotechnologies' stock and explain which future paths for growth, margins and earnings would need to play out for today’s price to look materially higher or lower on the Community page. Each one connects its number to a specific view of how growth, profitability and risks might evolve, giving you a reference point you can revisit as new information becomes available.
Community views on Adaptive Biotechnologies split between one camp that sees meaningful upside and another that thinks expectations already run hot.
Bull case: 16% undervalued
"Marked improvement in profitability, with the MRD segment now EBITDA positive and company-wide cash burn improving 36% year-over-year, signals the business reaching scale and positions Adaptive for operating leverage and expanding net margins as revenue continues to rise."
Discover why this Narrative puts Adaptive Biotechnologies at 16% undervalued.
Bear case: 19% overvalued
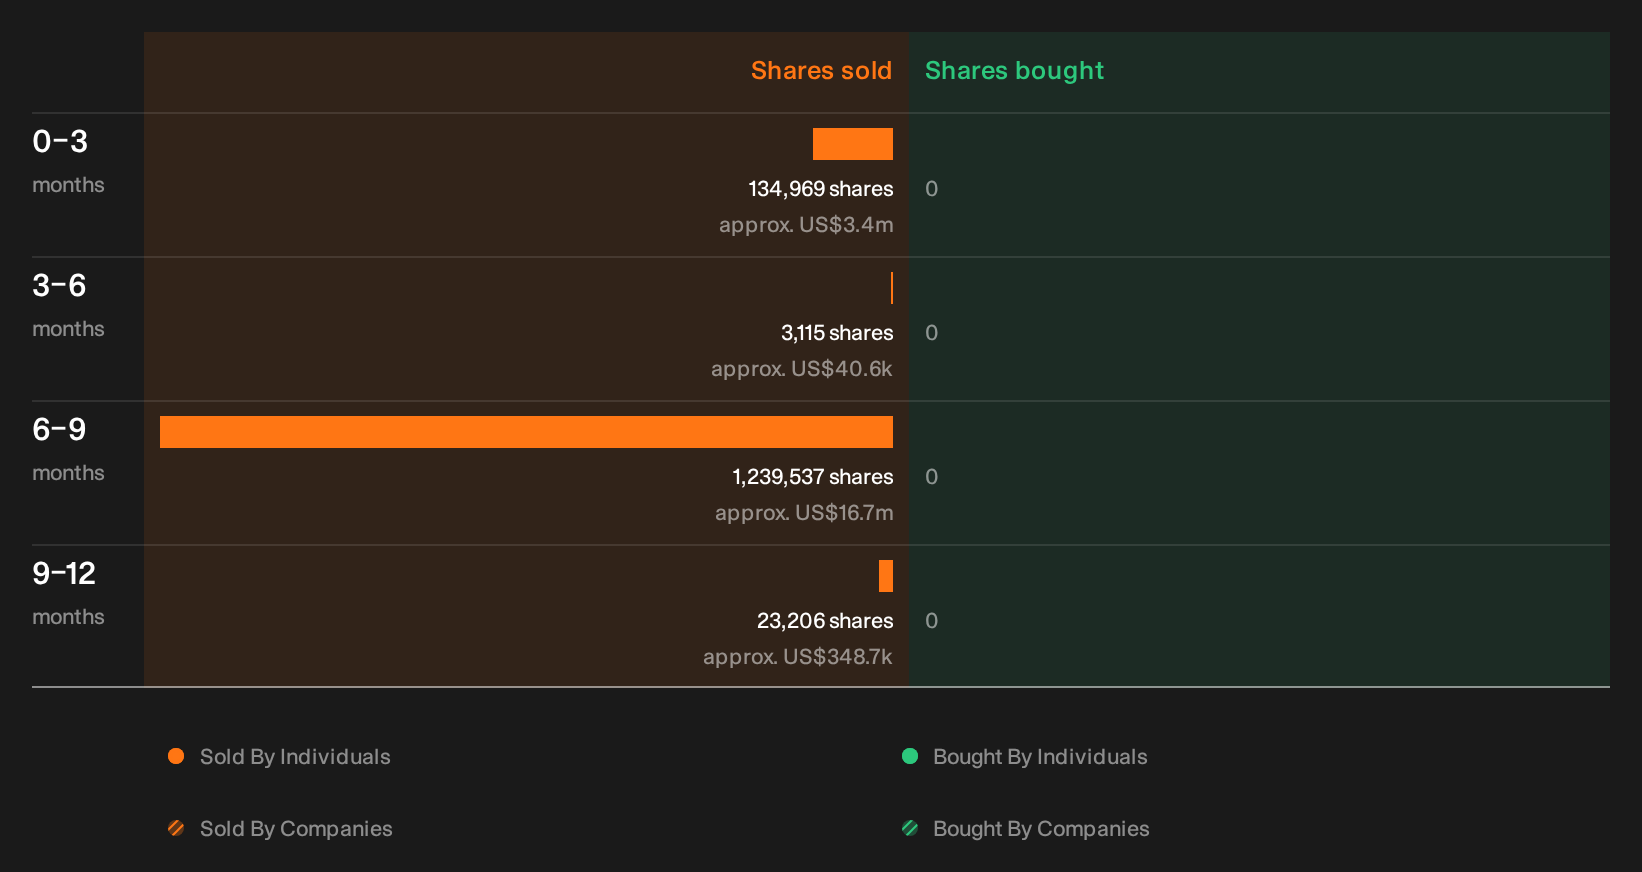
"Although Adaptive Biotechnologies reports strong MRD revenue of US$66.2 million in Q2 2026 with higher clinical volumes and rising sequencing gross margin, large 2026 insider and institutional share sales risk signaling internal caution that the current share price already discounts this momentum."
Explore why this Narrative puts Adaptive Biotechnologies at 19% overvalued.
One more piece of Adaptive Biotechnologies' story to check before you act
Before making any call on Adaptive Biotechnologies based on cash flows and community narratives, it is worth examining what recent insider share activity might be signaling about confidence and risk. See the recent insider selling flagged for Adaptive Biotechnologies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com