
International Seaways (INSW) Stock May Be Below Fair Value On Earnings
International Seaways has been on a remarkable multi year run, yet its recent pullback raises a straightforward question for investors who care about earnings. Is the current US$105.68 share price still grounded in what the business is actually earning, or has the stock moved ahead of itself?
- Over the past 5 years the stock has delivered a very large total return. That puts extra pressure on the earnings profile to justify where the shares trade today.
- The company’s ability to convert shipping income into consistent profits and cash flows can shape how durable its current earnings base looks and how much investors are prepared to pay for each dollar of that performance.
- The analysts covering International Seaways have run their own numbers. See what analysts think International Seaways's shares could be worth.
For investors, the debate is whether International Seaways’ earnings are strong and reliable enough to make today’s price look sensible on an earnings based lens.
If you are questioning whether International Seaways’ earnings still justify that strong multi year share run, it can help to compare it with other companies screened for 34 high quality undervalued stocks
Is International Seaways Still Cheap on Earnings?
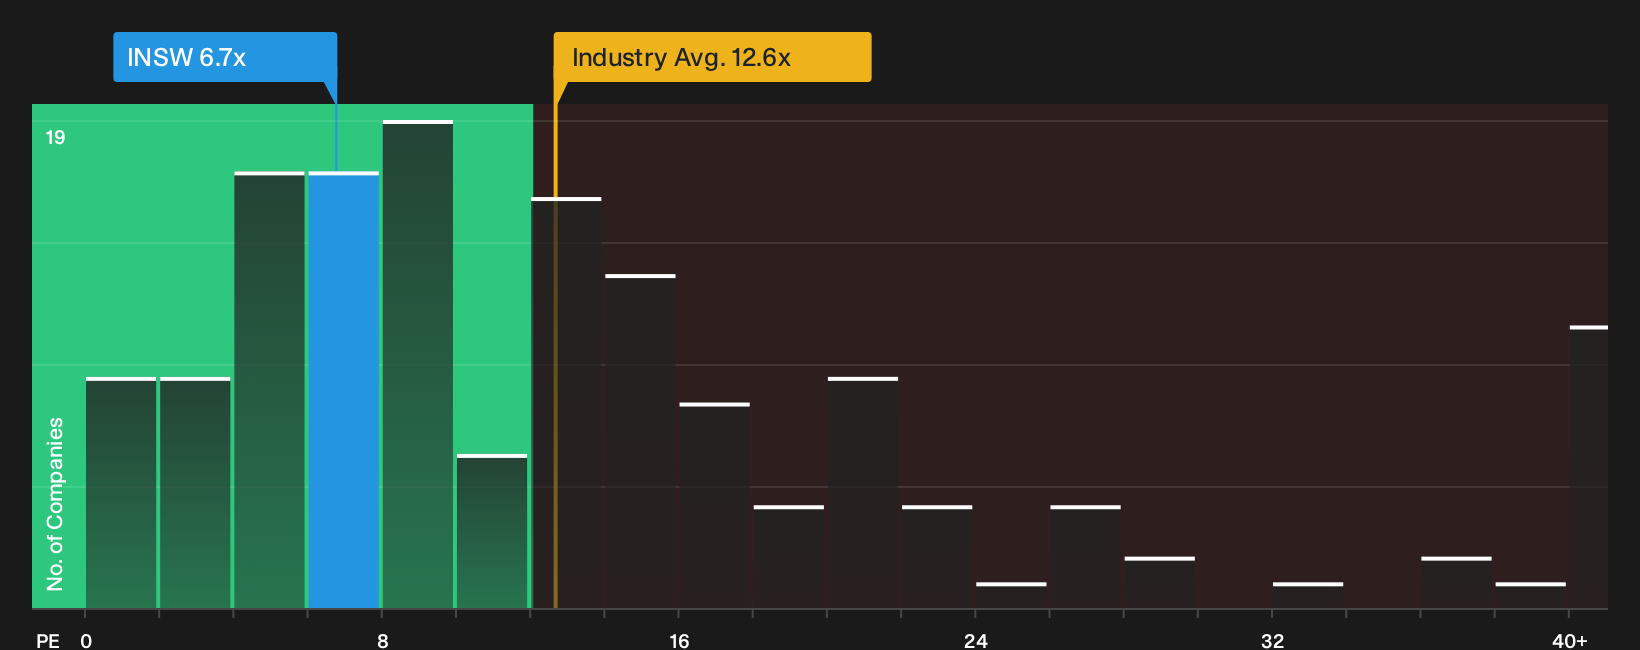
The P/E ratio is a useful lens for International Seaways because earnings power sits at the center of how investors frame shipping cycles. On this metric, the stock trades on about 6.7x earnings, which is meaningfully below both the Oil and Gas industry average of roughly 12.6x and a peer set closer to 11.6x. That gap indicates the market is applying a lower earnings multiple to this business than to many comparable operators.
The Fair Ratio model, which looks at factors like profitability, growth expectations, size and sector risk for International Seaways, suggests a higher P/E would be typical for this kind of earnings profile. The current 6.7x sits below that tailored reference point, so the valuation reflects a discount that investors need to weigh against the quality and durability of those profits. To see how wide that gap is and what it might imply for your own return expectations, you can run the numbers in more detail using the earnings lens. Explore the numbers behind International Seaways's P/E valuation.
The International Seaways Narrative: What Would Justify Today's Price?
Narratives for International Seaways pick up from the valuation puzzle by spelling out which earnings, growth and margin paths would need to hold for the stock to be worth meaningfully more or less than today’s price. Each one treats fair value as a specific, testable idea about how International Seaways' business could play out over time so you can see how that view holds up as new information arrives.
One of the top community narratives on International Seaways: 16% undervalued
"The company’s commitment to return at least 85% of adjusted net income through dividends, combined with additional discretionary payouts, channels a large share of cash generation to shareholders..."
Discover why this Narrative puts International Seaways at 16% undervalued.
Why the people running International Seaways still deserve your attention
The share price and earnings multiple only tell part of the story, because who steers International Seaways and how they are rewarded can heavily shape future decisions and risk. See who runs International Seaways and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com