
Kosmos Energy (KOS) Stock Could Still Look Undervalued On Debt Reduction News
Kosmos Energy has had a striking year in the market, and with the share price up sharply, the question now is whether that move is supported by the revenue the business is generating. With attention firmly on its recent operational updates and balance sheet progress, investors are increasingly asking how the current valuation lines up with the stock's sales profile.
- Year to date, Kosmos Energy has gained 176.7%, which raises a clear question about whether the current share price can be grounded in its underlying sales power.
- Recent reports that Kosmos Energy has reduced net debt by more than US$500m while increasing production may support different assumptions about future cash generation and how much investors are willing to pay for each dollar of revenue.
- The analysts covering Kosmos Energy have run their own numbers. See what analysts think Kosmos Energy's shares could be worth.
The issue now is whether the current share price of Kosmos Energy is justified by the level and quality of its sales.
After a year where Kosmos Energy has surged 176.7% year to date on the back of higher reported production, debt reduction and fresh news flow, it can help to cross check this kind of story against a wider group of companies that also meet clear, pre-set criteria using 34 high quality undervalued stocks.
Does Kosmos Energy Look Undervalued on Sales?
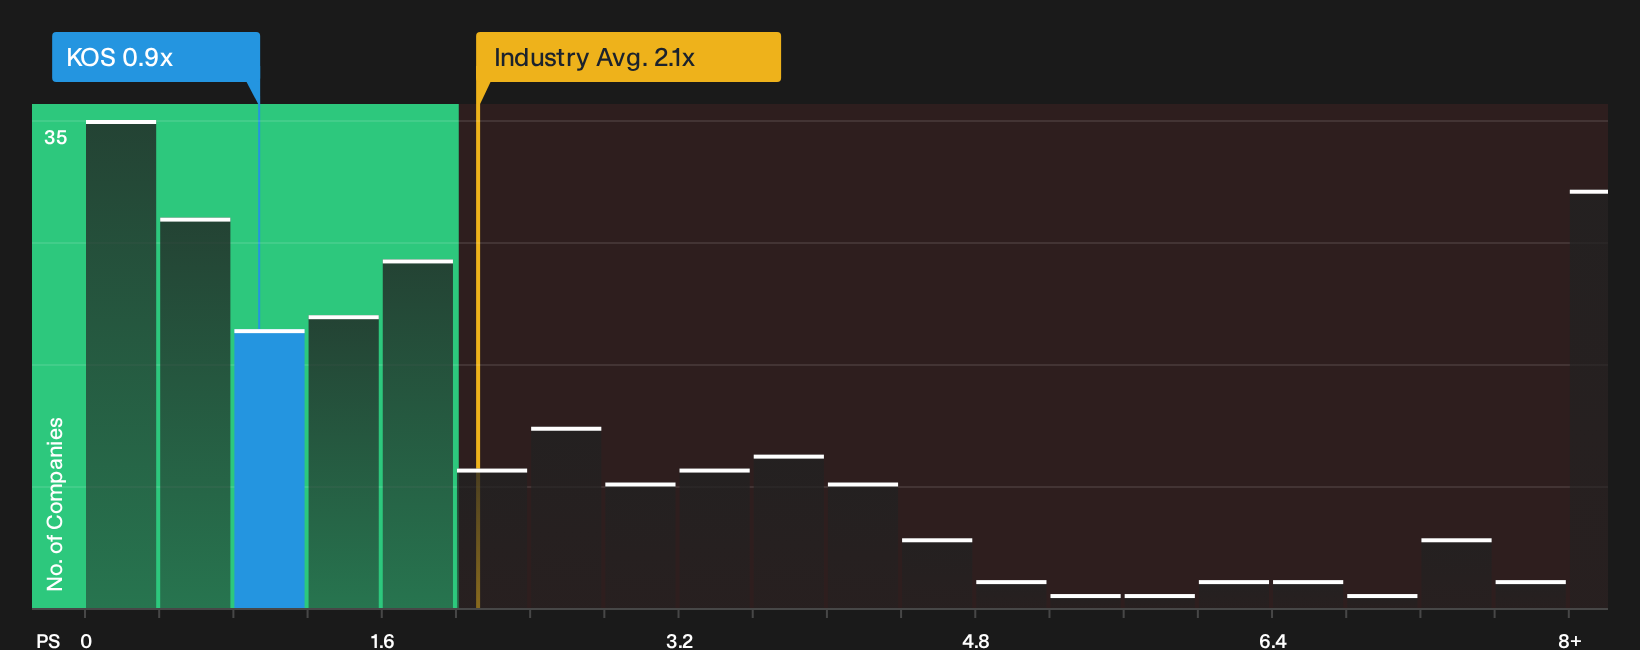
P/S works well for Kosmos Energy because investors are weighing how much they are paying for each dollar of sales in a sector where earnings can swing sharply. On that measure, the stock trades on a P/S of about 0.9x, which is well below the Oil and Gas industry average of roughly 2.1x and also below the broader peer group at about 3.6x. The tailored fair multiple that blends Kosmos Energy’s growth profile, margins, market size and risk points to a higher ratio than where the shares change hands today. This implies the stock screens as undervalued on this sales yardstick.
Because the latest quarterly updates highlight debt falling by more than US$500m and production running higher, the current discount on the P/S ratio comes despite improving operational metrics feeding into revenue. For anyone assessing Kosmos Energy, the key question is whether that sub 1x sales multiple reflects lingering concern about balance sheet risk and future profitability, or an opportunity if those issues continue to ease. Explore the numbers behind Kosmos Energy's P/S valuation.
The Kosmos Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Kosmos Energy pick up where that P/S puzzle leaves off and spell out which combinations of future revenue trends, margin profiles and earnings paths would need to play out for the shares to end up worth materially more or materially less than today’s level. Instead of a single output from a ratio or model, these scenario threads sit on Kosmos Energy's Community page and describe the future that number rests on so you can watch how reality compares over time.
Community views on Kosmos Energy split between a clean up story that still has room to run and a balance sheet that already looks fully priced.
Bull case: 42% undervalued
"When a leveraged E&P starts doing the right things at once, growing output, lowering costs, selling non-core assets, and paying down debt..."
Discover why this Narrative puts Kosmos Energy at 42% undervalued.
Bear case: 30% overvalued
"Despite the exit from high cost Equatorial Guinea barrels and the focus on high graded production, management and several analysts still describe leverage as elevated..."
Explore why this Narrative puts Kosmos Energy at 30% overvalued.
One more Kosmos Energy check that sits outside the share price math
Before you stop at ratios and scenarios, it is worth asking who is actually steering Kosmos Energy and how their pay packets line up with your interests. See who runs Kosmos Energy and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com