
Earnings Beat Might Change The Case For Investing In Graphic Packaging Stock (GPK)
- Graphic Packaging Holding recently reported that the last quarter's revenue of US$2.19b was in line with the prior year and above analyst expectations, while full year EBITDA guidance was set above consensus.
- The upcoming earnings release follows that outperformance and comes with analysts expecting a 1.6% year on year revenue decline, which puts execution on costs, pricing, and cash generation in sharper focus than headline sales.
- We will now explore how Graphic Packaging Holding's recent earnings beat and upcoming results could shape the existing investment narrative.
Scan beyond Graphic Packaging Holding and line up potential peers or alternatives using our curated list of 34 high quality undervalued stocks that combine stronger balance sheets with disciplined cash generation.
Graphic Packaging Holding Investment Narrative Recap
For Graphic Packaging Holding, the core belief is that a focused fiber based packaging platform, disciplined capital spending and cost savings can translate steady demand into stronger cash generation over time. The latest quarter, where revenue met expectations and EBITDA guidance sat above prior views, supports the idea that the operating model can cope with flat volumes in the near term.
The key near term catalyst is execution on cost, pricing and cash conversion against an expected 1.6% revenue decline this quarter. That puts inflation, weaker net margins at 2.2% and interest cover under the spotlight. If input costs or capex overruns flare up again, the path to higher free cash flow becomes harder.
The most relevant update here is management setting full year EBITDA guidance above earlier analyst expectations after last quarter’s report. That outcome, tied to US$2.19b of largely unchanged sales, shows the company leaning on cost actions, mix and pricing rather than relying on volume momentum.
For you as a shareholder or potential investor, that guidance sits at the intersection of catalysts and risks. Progress on lower capex, the US$85 million cost savings program and recycled board expansion all feed into EBITDA delivery. Any slip in cost control, or further pressure from inflation and interest expenses, would quickly show up against those earnings targets.
Graphic Packaging Holding Forecasts and Valuation Anchors
Graphic Packaging Holding's story in analyst models leans heavily on gradual improvement rather than dramatic change. Forecasts build on modest top line assumptions and more material earnings expansion, which is where your attention probably belongs.
Consensus projections point to revenue growing by 1.3% a year on average over the next three years. Current profit margins of 2.2% are expected to move toward 4.2% over that same stretch, which effectively asks the business to do more with roughly the same sales base rather than chase aggressive volume gains.
Earnings today are estimated at US$194.0 million, with analysts collectively targeting US$374.5 million by 2029. That profile implies a US$180.5 million earnings uplift over the period, framed by a wide spread of views between the most optimistic forecast of US$472.7 million and the lowest estimate of US$302.8 million.
Graphic Packaging Holding's narrative projects US$9.0b revenue and US$374.5 million earnings by 2029. This requires 1.3% yearly revenue growth and an earnings increase of US$180.5 million from US$194.0 million today.
On the valuation side, the analyst framework ties these future numbers to a P/E multiple that is lower than both today’s level and the broader packaging group. The current P/E of 13.3x is assumed to compress to 11.5x on 2029 earnings, compared with 18.6x for the wider US Packaging industry. This effectively bakes in some caution about execution even if the targets are met.
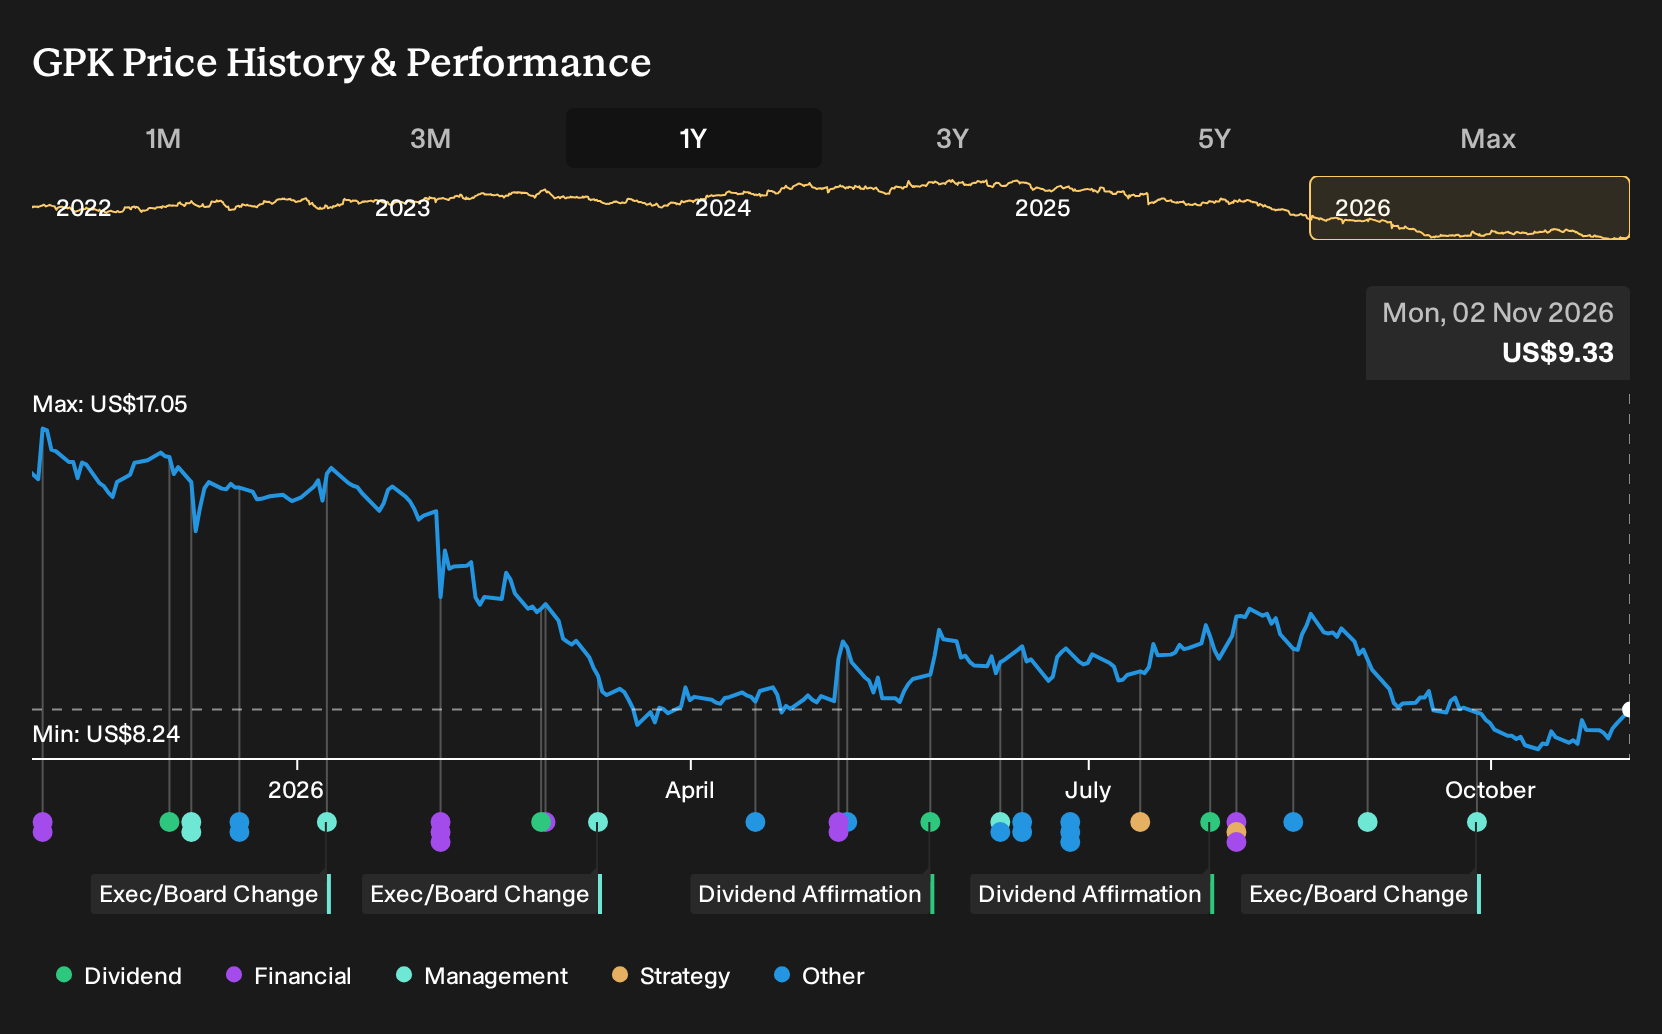
Those earnings and multiple assumptions translate into a consensus price target of US$10.95 per share, compared with a recent price around US$8.73. Price objectives range from US$9.00 to US$18.00, so the spread between the most cautious and the most optimistic analyst reflects real uncertainty around how much of the margin and free cash flow story can be delivered by 2029.
Uncover why Graphic Packaging Holding's fair value indicates a 17% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For Graphic Packaging Holding, the bullish twist is earnings power. The most optimistic analysts were pencilling in US$471.4 million of profit and US$9.6b of revenue by 2029 before this earnings update. That is a much stronger earnings path than consensus, and it could shift again once the latest results land. Explore several viewpoints before deciding what you think.
Explore 3 other Graphic Packaging Holding fair value estimates, including one that suggests as much as 173% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Graphic Packaging Holding research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Graphic Packaging Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Graphic Packaging Holding's overall financial health at a glance.
Looking for more investment ideas beyond Graphic Packaging Holding?
Once you have a view on Graphic Packaging Holding, it can help to line it up against a wider watchlist built around the specific traits you care about most, whether that is value, resilience, or long term income potential.
- If you want potential upside with tighter risk filters, start by scanning a curated set of 29 resilient stocks with low risk scores that aim to balance return potential with more measured volatility.
- For investors who care most about financial strength, broaden your research with a list of solid balance sheet and fundamentals (24 results) so you can compare balance sheet quality across several sectors in one place.
- If you prefer to focus on cash returns, use a hand picked pool of 4 dividend fortresses to spot companies that pair higher yields with fundamentals you can evaluate quickly.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com