
How Investors May Respond To Plexus (PLXS) Strong Earnings Report
- Plexus reported fourth quarter 2026 sales of US$1,426.57 million and net income of US$68.51 million, with full year 2026 sales of US$4,964.96 million and net income of US$202.49 million, alongside detailed earnings per share figures.
- The company paired this earnings release with fresh guidance for early fiscal 2027 and an update on its US$100 million repurchase program, giving investors a clearer view into capital allocation and expected operating margins.
- We will look at how Plexus's investment narrative aligns with this earnings strength, especially the detailed guidance on operating margins.
Scan how Plexus's latest earnings stack up against peers by comparing them with our hand picked list of solid balance sheet and fundamentals (24 results) for context on quality and capital discipline.
Plexus Investment Narrative Recap
Plexus appeals to shareholders who buy into a long runway for complex electronics manufacturing, supported by sectors like aerospace, defense and healthcare. The latest quarter and full year results show the business handling a larger revenue base while keeping earnings positive, which ties directly to that thesis. The near term hinge is management holding operating margins near guided levels in early 2027 as volumes shift.
The largest operational risk right now is a demand slowdown or weaker program conversions from its qualified funnel, which could pressure both sales and profitability. This earnings report does not remove that risk, but the updated margin guidance gives you a clearer yardstick to track execution over the next couple of quarters.
The most relevant announcement for this earnings release is Plexus guiding for operating margins of 5.5% to 5.9% and diluted EPS of US$2.16 to US$2.32 in the first quarter of 2027 on revenue of US$1.41b to US$1.46b. Those ranges frame how management sees the business absorbing new program ramps and any mix shifts in higher complexity work.
For you as an investor, that guidance effectively becomes the near term scorecard for the Plexus story of scaling complex, regulated sector work while keeping returns steady. Any sustained gap between these margin targets and actual results would raise questions about how resilient the manufacturing funnel really is if sector conditions soften or working capital needs rise.
Plexus Consensus Forecasts in Context
Analysts currently build the Plexus story around fairly specific targets. They model annual revenue growth of 14.0% over the next three years and expect earnings to move from US$185.4 million today to US$335.8 million by 2029, with a more optimistic camp pointing to US$393.1 million. That path assumes profit margins rising from 4.0% now to 4.9% in three years and a modest reduction in share count as outstanding shares decline by 0.46% a year.
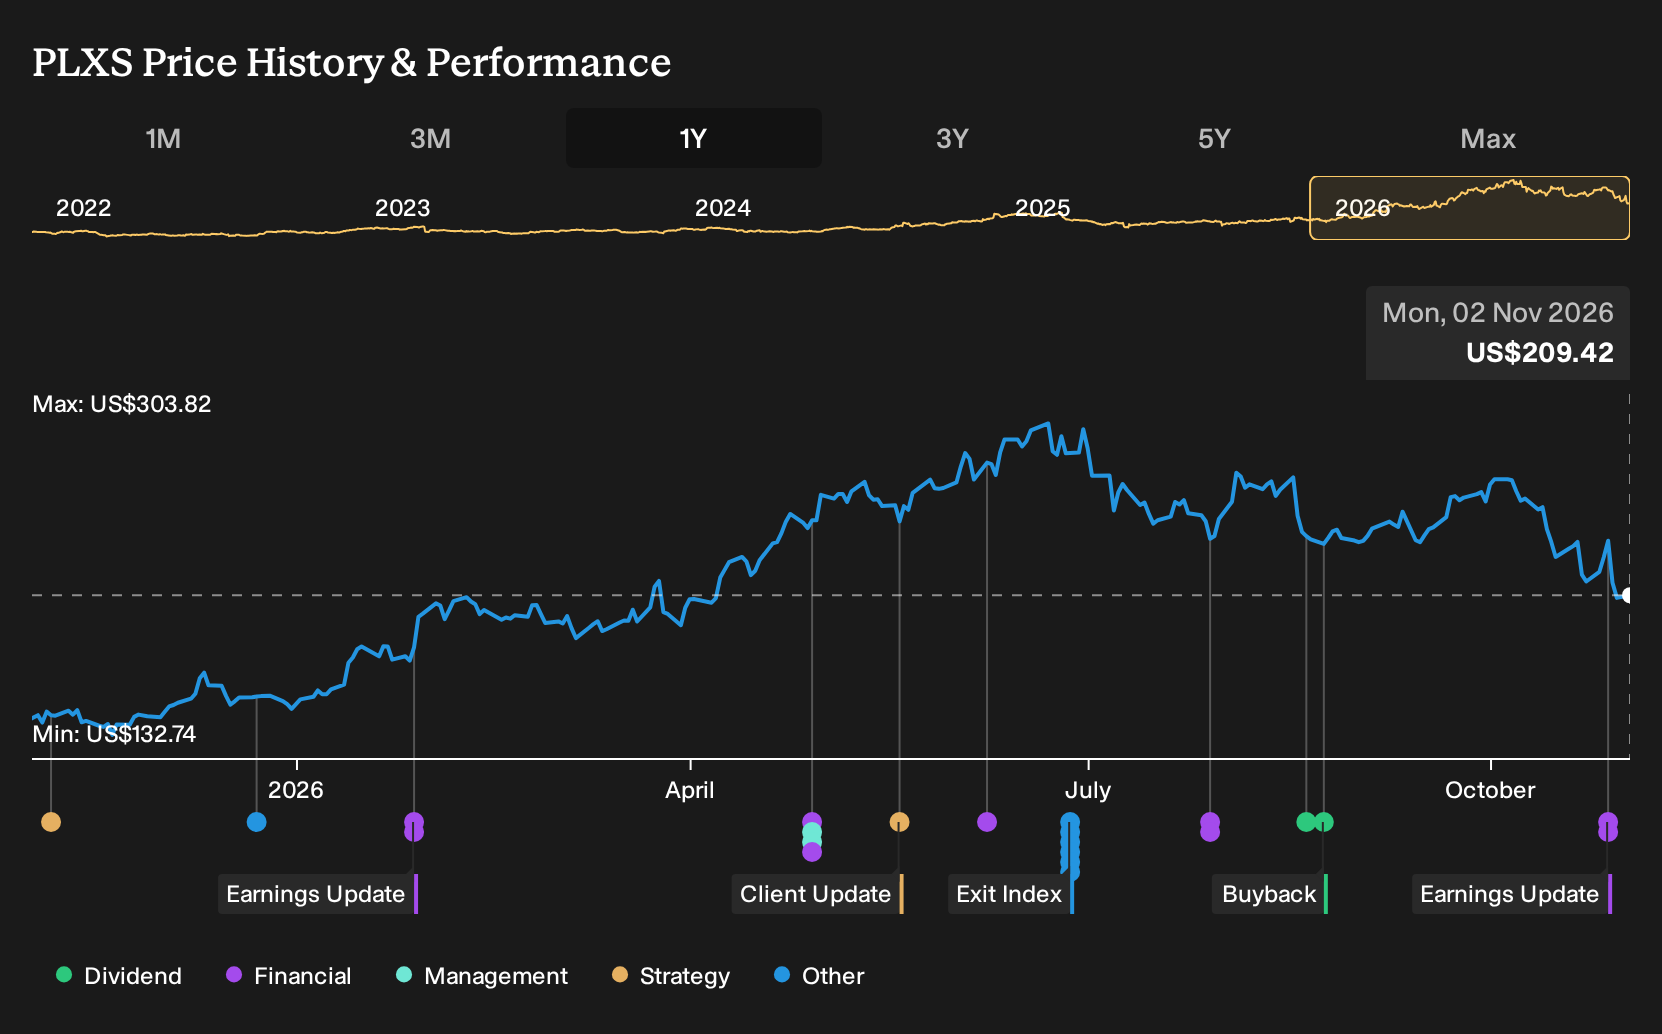
On these estimates, the consensus view ties back to a 2029 revenue figure of US$6.8b and earnings of US$335.8 million, with Plexus trading on a P/E of 30.9x at that point compared with 39.3x today. Against the current US Electronic industry P/E of 30.3x, that would still leave the stock on a slightly richer multiple if the scenario plays out. The implied analyst price target of US$304.60, about 10.3% above the recent US$273.13 share price, rests squarely on this combination of higher sales, wider margins and a still elevated earnings multiple.
For you, the practical use of these numbers is as a checklist rather than a forecast carved in stone. Revenue growth tracking below 14% a year, margins stalling near 4.0%, or the P/E compressing meaningfully below the projected 30.9x would all chip away at the assumptions supporting the current target. In contrast, stronger earnings delivery or better than expected cash generation could support a different valuation framework, especially if the market re rates high complexity manufacturers as a group.
Plexus' narrative projects US$6.8b revenue and US$335.8 million earnings by 2029. This requires 14.0% yearly revenue growth and an earnings increase of about US$150 million from US$185.4 million today.
Uncover why Plexus' fair value indicates a 45% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
One alternative view focuses on capacity risk. If Plexus struggles to keep new aerospace and semicap lines fully loaded, bearish analysts see 3 year revenue growth closer to 12% and 2029 earnings nearer US$315.2 million. That is well below the bullish US$335.8 million path. These lower estimates were set before this earnings and guidance update, so you may want to consider how this latest report could influence both narratives.
Explore another Plexus fair value estimate, including one that suggests as much as 26% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Plexus research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Plexus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Plexus' overall financial health at a glance.
Looking for more Plexus sized investment ideas?
If the Plexus story has sharpened your thinking and you want fresh opportunities with clear fundamentals, the Simply Wall St Screener can help you quickly filter the market to match your own risk and return preferences.
- For investors who care most about balance sheet strength and business quality, a curated list of solid balance sheet and fundamentals (24 results) can surface candidates that might warrant a closer look.
- If your focus is on resilient companies with steadier risk profiles, you may want to review a 29 resilient stocks with low risk scores that filters for more durable characteristics.
- Those hunting for overlooked opportunities with strong underlying metrics can scan a 19 high quality undiscovered gems that highlights less crowded ideas.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com