
How Investors May Respond To Bucher Industries (SWX:BUCN) Softer 2026 Guidance
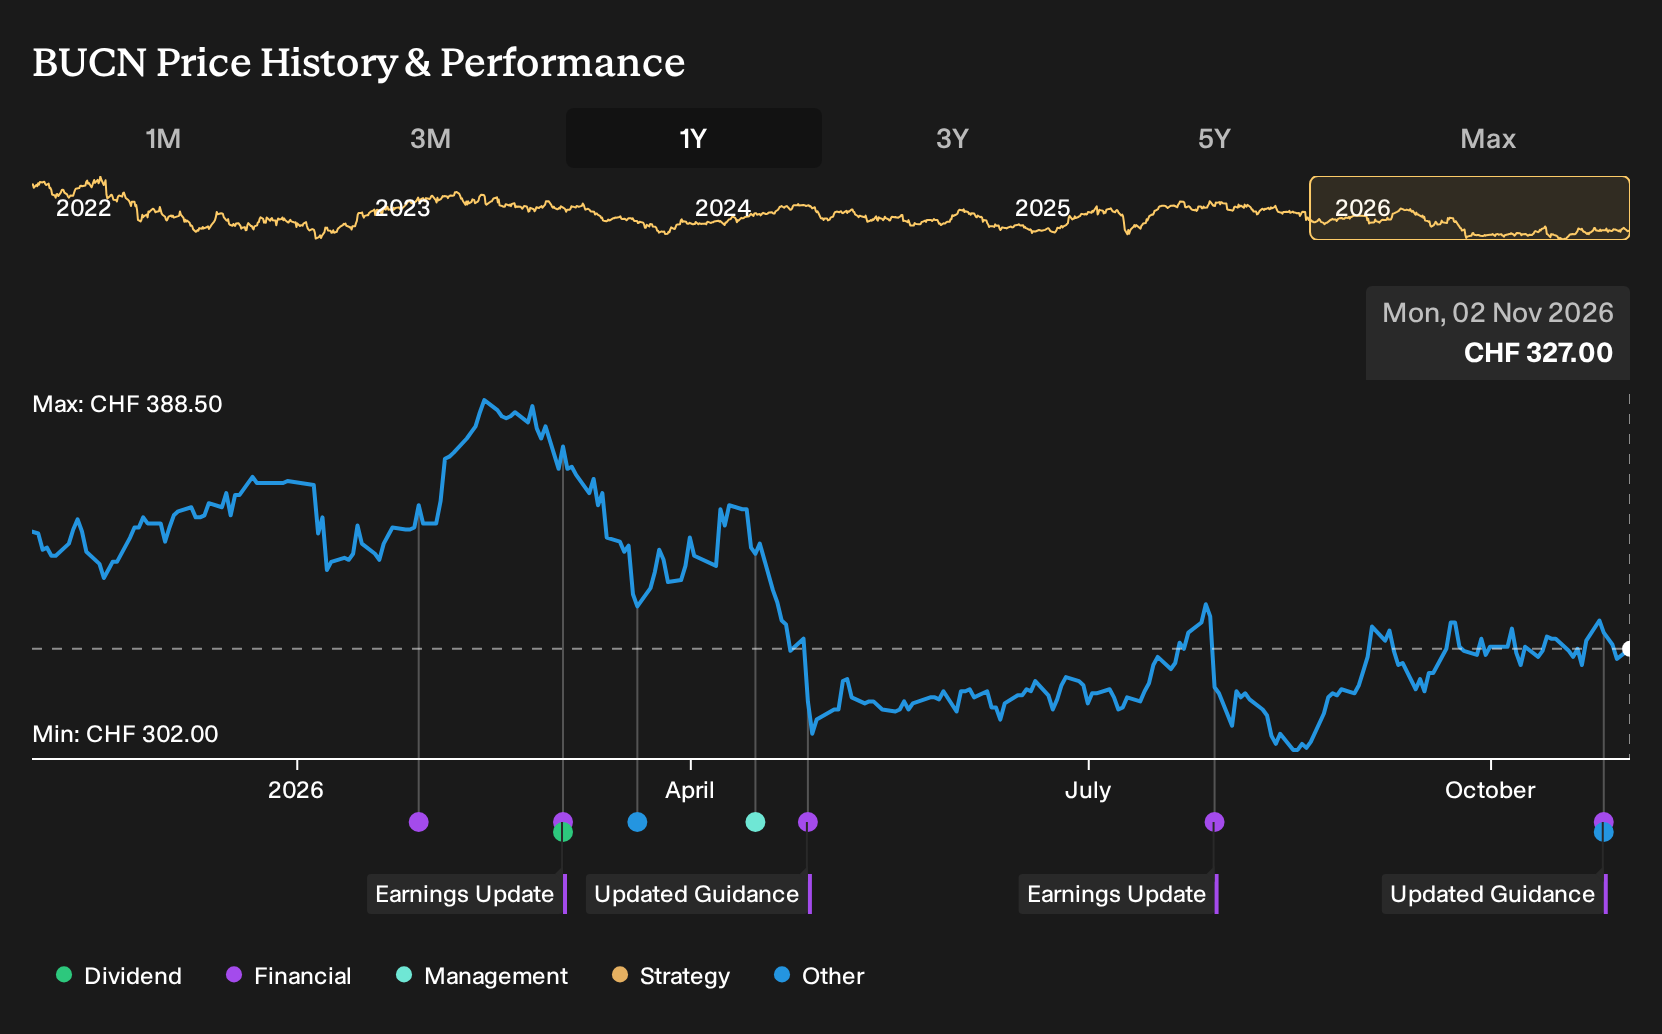
- Bucher Industries announced 2026 guidance indicating that Group sales are expected to be slightly lower on a comparable basis, with the operating profit margin below the prior year level once the CHF 43 million one off property gain in 2025 is excluded.
- The updated outlook highlights pressure on both volumes and profitability, which indicates a tougher operating backdrop for Bucher Industries than the earlier narrative of resilient demand and disciplined execution implied.
- The focus now shifts to how Bucher Industries' investment narrative holds up when management expects slightly softer sales and a lower operating margin.
Compare how Bucher Industries' softer 2026 guidance stacks up against peers by scanning our hand picked 218 resilient stocks with low risk scores that aim to balance earnings pressure with balance sheet strength.
Bucher Industries Investment Narrative Recap
To stay invested in Bucher Industries, you need to be comfortable with a manufacturing group that leans on steady demand for agricultural, municipal and hydraulic equipment, supported by a solid balance sheet. The softer 2026 guidance points to a period of slightly lower volumes and reduced profitability, so in the near term the key question is how well operating discipline can offset that pressure.
The main short term catalyst remains execution on cost control and mix, especially as weaker glass and wine equipment markets linger in the background. The biggest risk is that softer demand combines with ongoing geopolitical issues or trade barriers, which could add further strain to both revenue visibility and margins beyond what management currently signals.
The most relevant recent development is the one off property gain of CHF 43 million booked in 2025, which management explicitly strips out when comparing the 2026 operating margin with the prior year. That adjustment matters for you because it keeps the focus on underlying profitability, not accounting noise, at a time when the guidance already points to some earnings pressure.
Large non recurring items have been a live issue for Bucher Industries, with prior gains affecting reported results and complicating any clean read on cash conversion and return on equity. As you think about catalysts, it becomes important to separate these exceptional effects from core trends in free cash flow, working capital discipline and the group’s ability to fund R&D, acquisitions and dividends from recurring operations.
How Bucher Industries' Guidance Lines Up With Analyst Assumptions
Forecasts for Bucher Industries sketch out a business that, despite softer 2026 guidance, is still modeled on steady expansion in the top line and modest improvement in profitability by the end of the decade. Analysts currently build in 4.5% yearly revenue growth over the next three years, which sits in clear tension with management talking about slightly lower sales on a comparable basis in 2026. That gap between guidance and spreadsheet is where your judgment really matters, because it shapes how you read both the downside risk in a tougher equipment cycle and the potential upside if execution or demand prove more resilient than the near term messaging implies.
On the earnings side, the consensus numbers frame what needs to happen behind the softer narrative. Analysts estimate Bucher Industries is earning CHF 179.7 million today and could be producing CHF 210.0 million of profit by 2029, with margins nudging from 6.3% to 6.5%. That implies an increase of roughly CHF 30 million in earnings over the period, even though management is bracing investors for lower operating profitability in 2026 once the 2025 property gain is stripped out. For you, the core question is whether incremental margin lift over several years feels realistic when the near term guide is for pressure on volumes and returns.
Bucher Industries' narrative projects CHF 3.3b revenue and CHF 210.0 million earnings by 2029. This assumes 4.5% yearly revenue growth and an earnings increase of about CHF 30 million from CHF 179.7 million today.
Those same projections also anchor how the stock is being priced. The current P/E of about 18.0x on today’s earnings would, in the analyst view, ease to 17.8x on those 2029 profits. They see this as consistent with a fair value near CHF 336.33 per share versus a current price of CHF 329.00. Even if you ignore the price target, the mechanics are clear. To accept the consensus, you would need to be comfortable with Bucher Industries lifting earnings from current levels while absorbing a period where management is openly guiding to slightly weaker sales and a lower operating margin once non recurring items are excluded.
In practical terms, the bridge between a softer 2026 and the 2029 snapshot rests heavily on cash generation, capital discipline and mix. Analysts assume revenue grows, margins inch higher, and the share count drifts down about 0.79% a year, which mechanically supports earnings per share even if net profit grows only modestly. That set up puts more weight on the balance sheet and free cash flow story, because it is those elements that give management room to keep funding R&D, selective acquisitions and shareholder returns without stretching the financial profile if the operating backdrop stays tough for longer than expected.
Uncover why Bucher Industries' fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between CHF 336.33 and CHF 345.46, so you are not seeing extreme bargain calls on Bucher Industries or aggressive overvaluation flags. Those community views also pre date the softer 2026 guidance; trade tariffs, glass overcapacity and cash generation resilience could all shift outcomes from here. Opinions clearly vary. It is worth comparing several of these perspectives before deciding how the updated outlook fits your own expectations.
Explore another Bucher Industries fair value estimate, including one that suggests it could be worth just CHF 336.33.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bucher Industries research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bucher Industries. This report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bucher Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Bucher Industries?
If Bucher Industries is on your radar but you want a broader watchlist, using the Simply Wall St Screener can help you line up other stocks that fit your risk, income and quality preferences in a more systematic way.
- If capital preservation matters most, start with a basket of companies that score well on stability and financial resilience through the 218 resilient stocks with low risk scores.
- If value is your main filter, broaden your research with a curated set of quality businesses trading below their estimated worth using the 191 high quality undervalued stocks.
- If you care about income alongside fundamentals, build a shortlist of higher yielding payout profiles by scanning the 220 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com