
Is WD-40 (WDFC) Undervalued On Earnings And 2027 Guidance?
Why WD-40's Latest Earnings Are in Focus
WD-40 (WDFC) has put fresh numbers on the table, with fourth quarter and full year 2026 results that show higher sales alongside lower net income and earnings per share.
The company also issued fiscal 2027 guidance that points to increases in net sales, operating income, and diluted EPS, giving investors a clearer sense of how management currently views the next financial year.
WD-40's latest earnings drop landed alongside a sharp rebound in the share price, with a 1-day share price return of 3.27% and a 30-day share price return of 12.22% lifting the stock to $227.83. Despite that recent momentum, the 90-day share price return declined 3.46%, while the 1-year total shareholder return of 19.27% and 5-year total shareholder return of 6.49% point to steadier gains over longer periods as investors weigh the updated 2027 outlook and the completed buyback program.
Compare WD-40's earnings reaction with a hand picked group of resilient peers by scanning the 29 resilient stocks with low risk scores that have held up well on quality and balance sheet strength.
WD-40 just reminded investors it can grow sales even when earnings tighten, and the share price has bounced hard on that story. The next step is simple: Are you paying a fair tag for that resilience today?
Most Popular Narrative: 10% Undervalued
Against WD-40's last close of $227.83, the most followed narrative pegs fair value at $254, so the story frames the current price as slightly behind where long term assumptions land.
Continued premiumization of WD-40 Multi-Use Product, where Smart Straw and EZ-REACH already account for about half of revenue in this category with 30% to 45% price uplifts and relatively low penetration in many emerging markets, can keep shifting mix toward higher margin products and support gross margin and earnings.
See why 9 investors see WD-40 as 10% undervalued.
Result: Fair Value of $254 (UNDERVALUED)
Still, WD-40’s story can break if petroleum based input costs stay elevated for longer than expected, or if the stock later reprices toward sector level P/E multiples.
Find out about the key risks to this WD-40 narrative.
Another View: What WD-40's High P/E Is Telling You
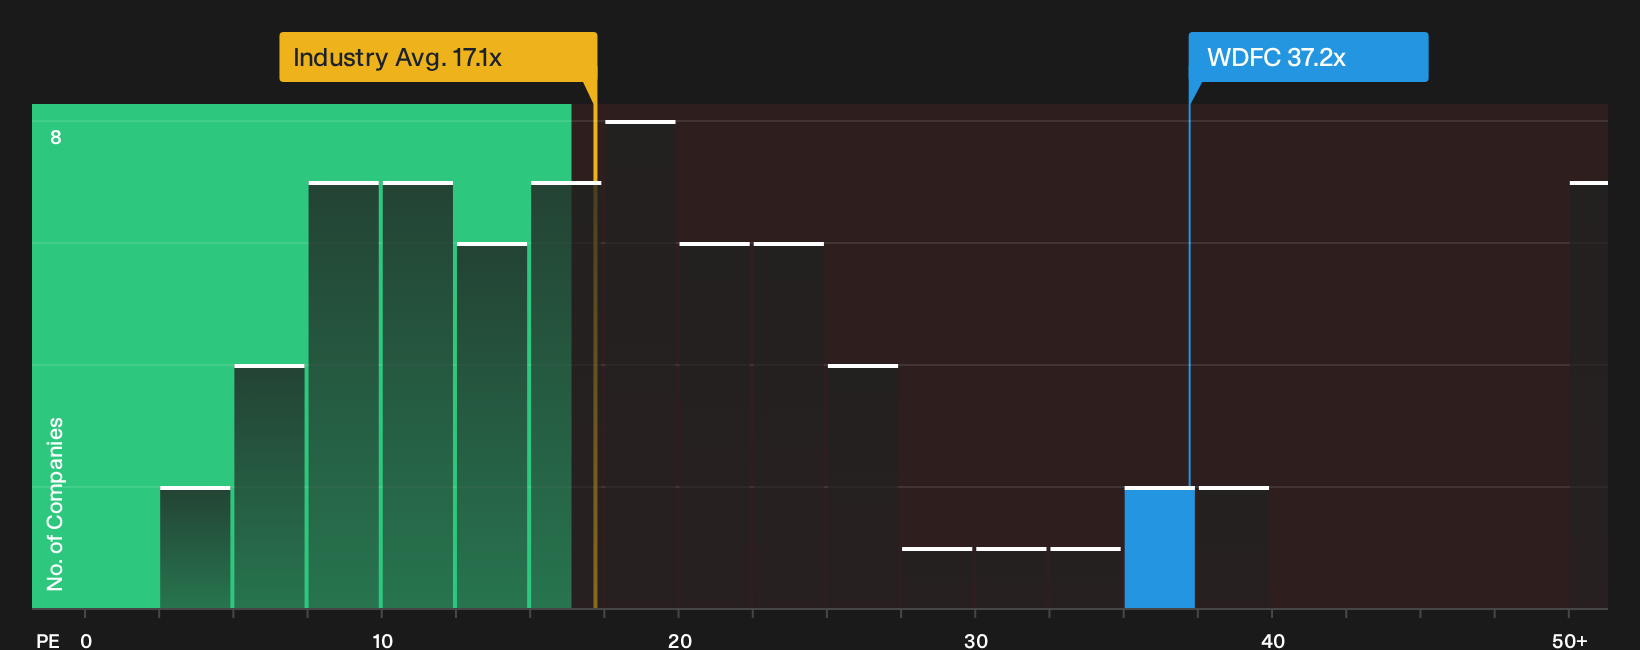
The fair value narrative paints WD-40 as about 10% undervalued at $254. Yet the current P/E of 37.2x is far above a fair ratio of 15.9x, and well ahead of both global household peers at 19.6x and the wider industry at 17.1x. That gap builds in real valuation risk if sentiment cools.
See what the numbers say about this price in more detail with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
All this optimism around WD-40's resilience is only one side of the story, and the data is available for you to stress test that view yourself. To see what has investors upbeat and decide if those positives matter for your own portfolio, take a closer look at the 2 key rewards.
Looking For More Ideas Beyond WD-40?
WD-40 might already be on your radar, but you miss real opportunities if you stop there. Use curated screeners to widen your opportunity set fast.
- Target resilient balance sheets by running your filters through the list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a discount by scanning the 34 high quality undervalued stocks.
- Spot lesser known opportunities with strong fundamentals by reviewing the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com