
Is Riot Platforms (RIOT) Fully Priced After Its $9.1B Lease?
Riot Platforms has seen its share price under pressure, and the question now is whether the current US$11.84 level can be explained by the sales the business generates. With the stock reacting to big contract headlines and sharp multi year losses, the real issue for you is how much revenue the market is effectively paying for today.
- Over the past 5 years the stock has fallen 67.7%, which puts the spotlight squarely on whether the current valuation still lines up with the company’s sales base.
- Riot’s decision to commit 191 megawatts at its Rockdale, Texas site to a single long term data center lease, expected to generate US$9.1b over 20 years, can reshape how reliably future revenue is tied to that power capacity and how investors weigh those contracted sales against the company’s existing balance sheet with US$471.4m cash and US$853.7m debt as of June 30, 2026.
- The analysts covering Riot Platforms have run their own numbers. See what analysts think Riot Platforms's shares could be worth.
The issue now is whether the price investors pay for Riot Platforms today is justified by the sales the business is generating and expects to book from its recent Rockdale lease commitment.
If you want a broader starting point while you weigh Riot Platforms against its contract driven story, a focused screener of 17 cryptocurrency and blockchain stocks can be useful.
Has Riot Platforms Run Too Far on Sales?
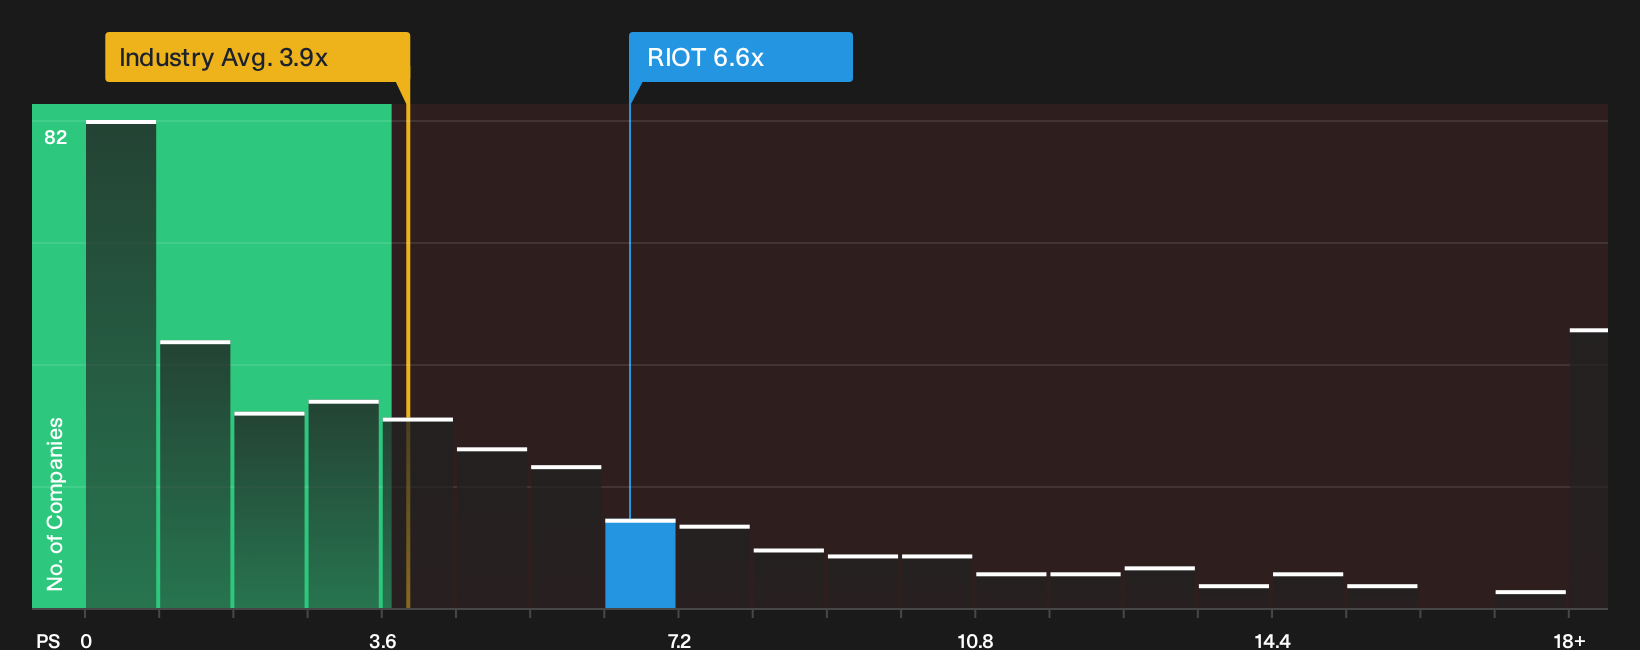
P/S fits Riot Platforms because investors are weighing the stock mainly on revenue and contracts rather than current profits. On that yardstick, the shares trade at about 6.6x trailing sales, compared with a Software industry average near 3.9x and a peer group closer to 16.3x. That leaves the stock priced above the sector as a whole but below more aggressively valued crypto exposed peers.
On a more tailored view that adjusts for Riot Platforms' margins, risk profile and scale, the current 6.6x P/S screens above the level suggested by that model, which points to an overvalued reading on this metric. Because the Rockdale lease announcement in September has been followed by a share price pullback of roughly one third, the market is still assigning a premium for the contracted revenue even as questions remain over pricing terms and funding. To judge whether that premium feels acceptable, you need to weigh how durable those Rockdale cash flows might prove against the balance sheet and the rest of the mining operation. Explore the numbers behind Riot Platforms's P/S valuation.
The Riot Platforms Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle for Riot Platforms leaves off and explain what kind of future growth, profitability and earnings profile would need to occur for the stock to be worth meaningfully more or less than today’s price on the Community page. Each one links its number to a clear view of how Riot Platforms' revenue trajectory, margins and risk profile might evolve, giving you something specific to refer back to as new information becomes available.
One of the top community narratives on Riot Platforms: 61% undervalued
"Riot Platforms is building on its earlier plan to grow a scalable data center business by locking in a 20-year, 191 MW lease with a frontier AI lab..."
Discover why this Narrative puts Riot Platforms at 61% undervalued.
The valuation leaves one more big question about Riot Platforms unanswered
You have a snapshot of what the market is paying for Riot Platforms today, but professional models for where this business might be a few years from now offer a different reference point to measure against. Explore where analysts expect Riot Platforms to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com