
Learn Why The Bull Case For Heritage Financial Stock Could Change Following Buyback Plan
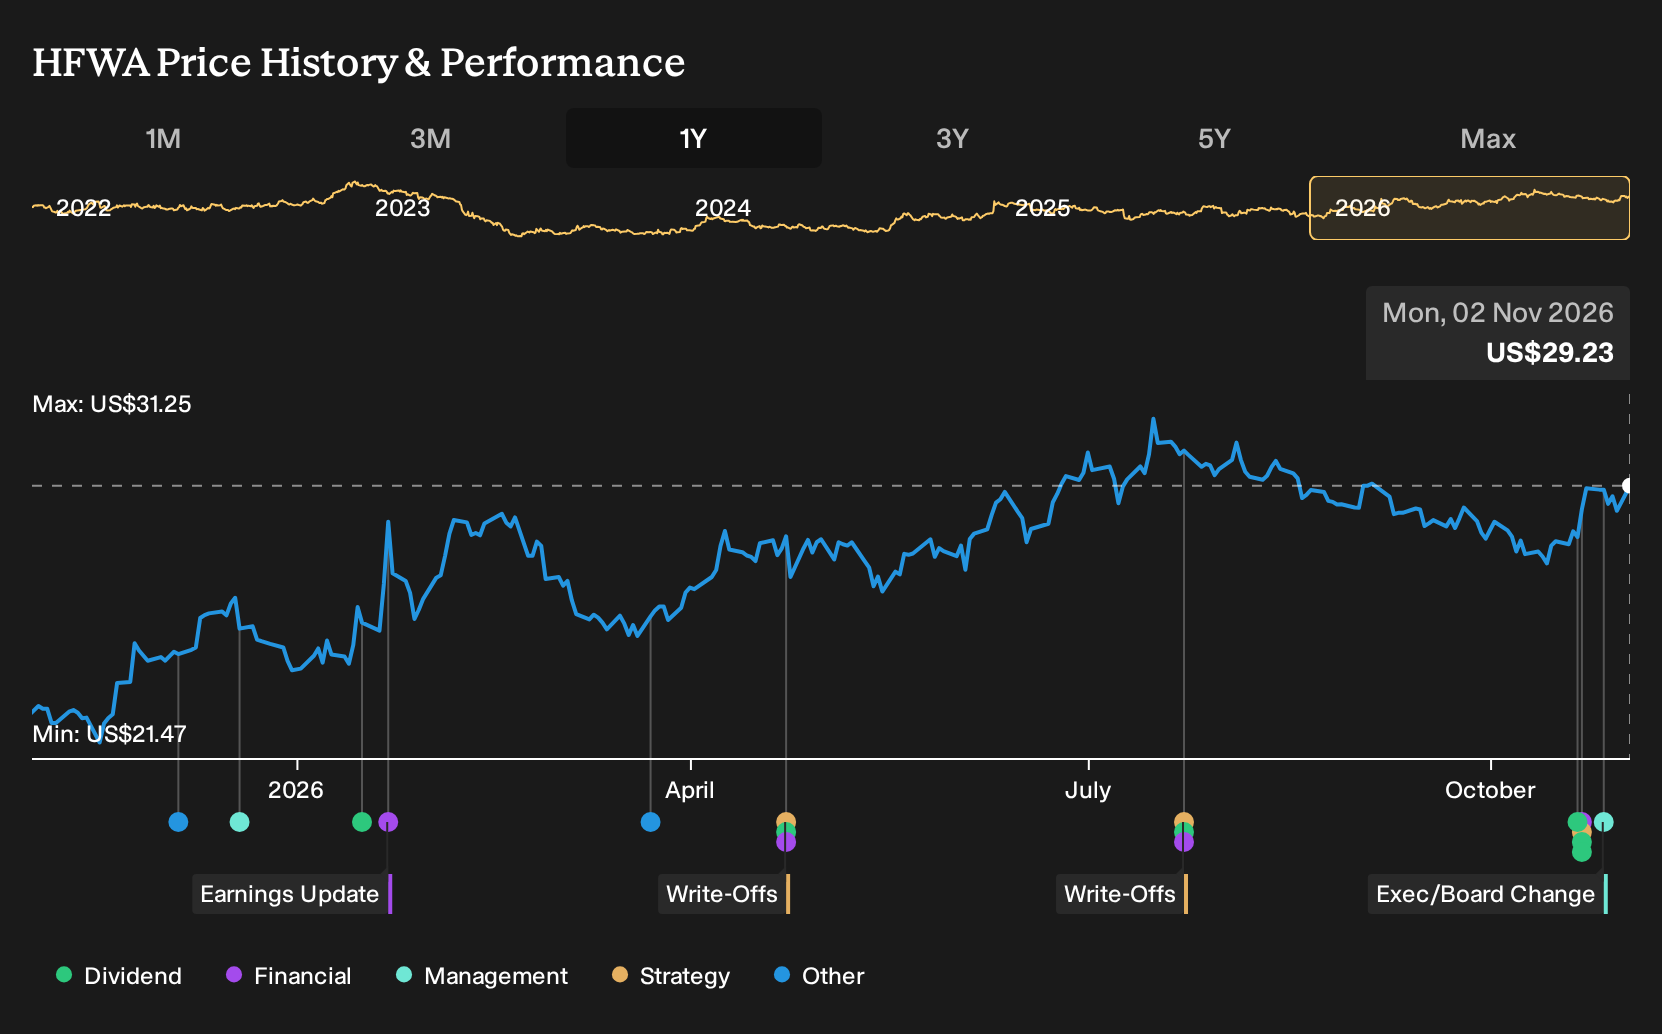
- Heritage Financial reported third quarter 2026 results and nine month figures, affirmed a US$0.25 quarterly dividend, expanded its share repurchase activity and disclosed modestly higher net charge offs, while also naming Pat Casey as Executive Vice President and Chief Information Officer.
- The combination of fresh buyback authorization, ongoing repurchases and a technology focused leadership hire highlights management’s focus on capital return alongside efforts to tighten Heritage Financial’s digital and data infrastructure.
- We will now look at how Heritage Financial's new share repurchase authorization may reshape the existing investment narrative investors have been using.
Heritage Financial Investment Narrative Recap
To own Heritage Financial, you need to be comfortable with a regional bank that is leaning on loan repricing, expense control and balance sheet flexibility while managing credit and funding costs. The latest quarter shows net interest income of US$77.26 million and net income of US$18.72 million, with modestly higher net charge offs at US$381,000. That credit trend is a practical near term risk, alongside deposit competition and loan prepayments that can keep growth in interest earning assets restrained.
The near term swing factor still looks like clean execution on cost efficiency and margin management as integration work seasons and the loan book resets. Recent earnings, share repurchases and the US$0.25 dividend declaration do not radically change that story. They do signal that Heritage Financial is continuing to balance capital returns with incremental credit and funding risks rather than pivoting the business model.
The new share repurchase authorization of up to 2,000,000 shares, on top of the 1,734,492 shares already bought for US$43.1 million, is the announcement that most directly ties into the current catalyst discussion. For an investor, the key question is how this interacts with earnings power, given analysts already expect profit growth and view the stock as trading below some intrinsic value estimates.
Buybacks can tighten the share count while Heritage Financial works through loan repricing, deposit competition and integration related cost actions. They also sit against flagged issues such as prior shareholder dilution, an unstable dividend record and insider selling. Anyone considering the stock will likely want to weigh that capital return against these operational and governance watchpoints, as well as the current P/E that screens above industry averages.
What The Heritage Financial Forecasts Assume
Heritage Financial's narrative projects US$411.6 million revenue and US$133.2 million earnings by 2029. This is based on company and analyst projections provided, which indicate 11.7% yearly revenue growth and an earnings increase of about US$55.3 million from US$77.9 million today.
Uncover how Heritage Financial's fair value indicates an 11% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community bracket Heritage Financial between about US$32.40 and US$44.02, showing how far private views can stretch. Those opinions sit alongside risks around loan prepayments, credit pressure and deposit costs, while new buybacks and the CIO hire add potential catalysts. There is likely to be wide disagreement, so consider exploring several viewpoints before deciding where you stand.
Explore another Heritage Financial fair value estimate, including one that suggests as much as 51% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Heritage Financial research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Heritage Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Heritage Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Heritage Financial?
Once you have a view on Heritage Financial, it often helps to compare it with other companies that share similar qualities in capital discipline, dividend focus or balance sheet strength. The Simply Wall St Screener can help you quickly surface a wider watchlist that fits those themes so you can see where Heritage Financial sits in a broader set of options.
- If you are hunting for resilient balance sheets and steady fundamentals, start with a list of solid balance sheet and fundamentals (24 results) that could complement or contrast what you see at Heritage Financial.
- For readers who care most about dependable income, line up potential alternatives by reviewing a 4 dividend fortresses and compare their yields and payout profiles to Heritage Financial's US$0.25 quarterly dividend.
- If you want to cast a wider net for overlooked quality, widen your research with a 19 high quality undiscovered gems that may share some of Heritage Financial's appeal while sitting off most investors' radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com