
ASML Holding (ENXTAM:ASML), What Is Drawing Fresh Attention Now?
Why ASML Holding Is Back Under The Microscope
ASML Holding (ENXTAM:ASML) is in focus after a sharp sector-wide pullback, sparked by Apple flagging margin pressure from rising chip costs and Intel issuing a weak outlook that hit semiconductor stocks globally.
Over the past month ASML Holding’s share price has fallen 14.8%, easing back from recent highs. However, the year-to-date share price return of 42.8% and the 1-year total shareholder return of 52.9% show that longer-term momentum has still been strong.
Scan beyond ASML Holding's pullback to compare it with hand picked 53 AI infrastructure stocks now shaping the backbone of high demand chip and cloud spending.
Bulls see ASML Holding’s 42.8% year-to-date surge and strong recent figures as evidence that the pullback is just noise. Bears point to sector shocks and a stretched multiyear run. Which case does the current valuation support?
Most Popular Narrative: 21% Undervalued
ASML Holding last closed at €1,408, while the most followed narrative pegs fair value nearer to €1,780. That gap is driving fresh debate about how much risk around China, capacity plans and long term cash generation is already in the price.
Investors have recently been forced to process two very different versions of ASML. The first is a company whose demand outlook is improving fast enough for management to lift 2026 sales guidance to a range of €43 to €45bn and gross-margin guidance to a range of 54% to 56%. The second is a business facing reports that a Chinese state-backed group has begun producing domestic immersion-DUV lithography systems, creating a potential long-term challenge in a market where ASML has historically had little effective competition. The first version supports a premium valuation. The second makes that premium more fragile.
See why 46 investors see ASML Holding as 21% undervalued.
Result: Fair Value of €1,780 (UNDERVALUED)
Still, the narrative could crack quickly if Chinese immersion DUV tools gain real traction, or if export controls tighten further on ASML Holding’s key customers.
Find out about the key risks to this ASML Holding narrative.
Another View: Multiples Put ASML Holding On A Tighter Leash
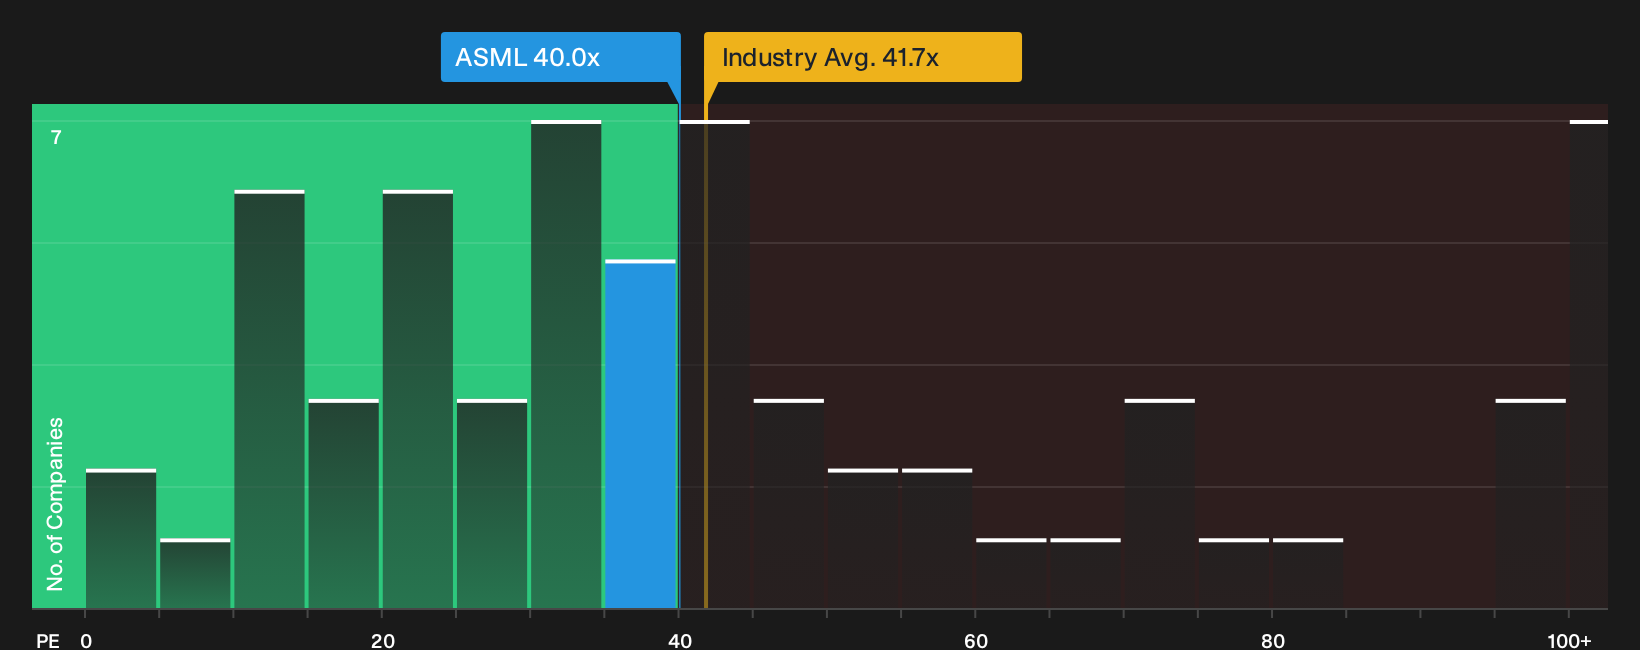
A second lens looks at ASML Holding through its P/E ratio of 40x. That sits above peers at 35.9x, yet only slightly below a fair ratio of 42.1x. Pricing already assumes a lot of good news, which may limit the room left if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on ASML Holding’s upside and risk profile can feel messy, so consider moving quickly, review the key data for yourself, and weigh the 4 key rewards and 1 important warning sign.
Looking For More Ideas Beyond ASML Holding?
If ASML Holding has sharpened your interest, do not stop here. Broader context across other high quality opportunities can really change how this pullback looks.
- Target resilience by reviewing companies screened for sturdy finances and low leverage through a focused list of solid balance sheet and fundamentals (197 results).
- Spot potential mispricing by comparing businesses that score well on quality while trading below estimated worth in the 191 high quality undervalued stocks.
- Hunt for under-the-radar potential by checking a curated 605 high quality undiscovered gems before everyone else starts paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com