
What Northwest Bancshares Stock's Earnings Jump Means For Shareholders
- Northwest Bancshares reported third quarter 2026 net interest income of US$148.95 million and net income of US$50.72 million, with higher basic and diluted earnings per share from continuing operations than the prior year period.
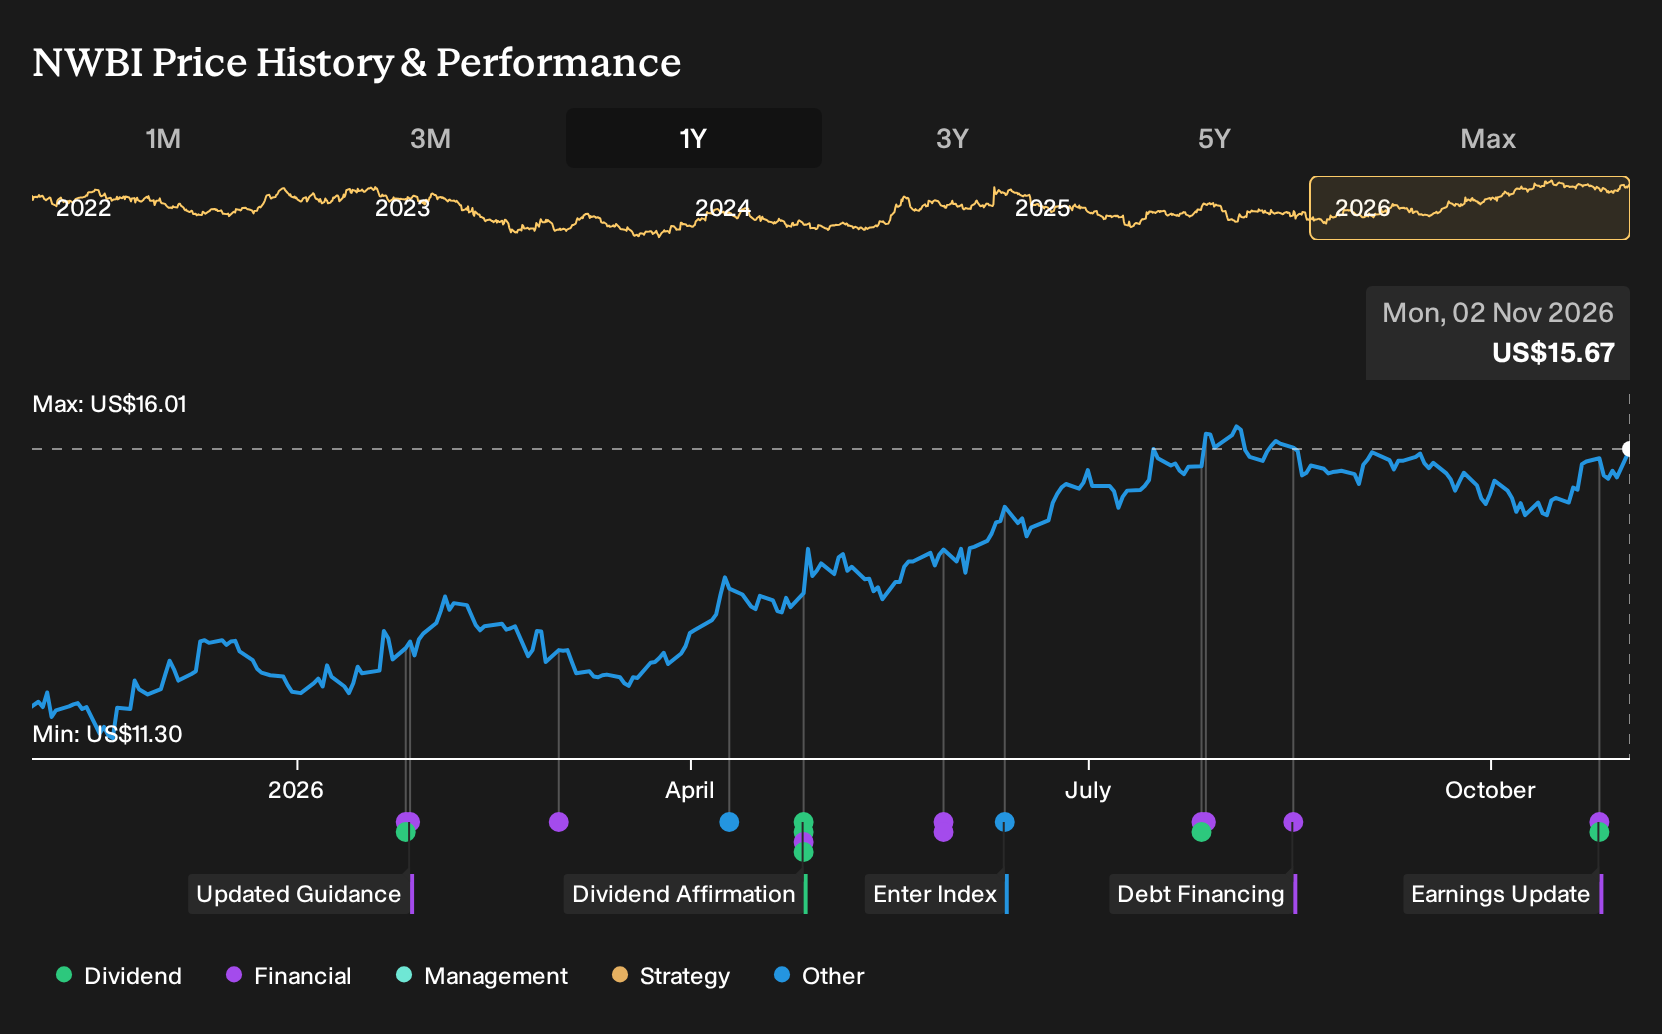
- The bank paired this earnings update with its 128th consecutive quarterly cash dividend, a US$0.20 per share payout that translated to an annualized yield of about 5.4% based on the 30 September 2026 share price.
- Investors may now consider how Northwest Bancshares' stronger earnings per share performance fits into the existing investment narrative.
Scan beyond Northwest Bancshares and line up other income-focused opportunities with strong cash profiles using our hand picked 4 dividend fortresses as a starting shortlist.
Northwest Bancshares Investment Narrative Recap
To own Northwest Bancshares, you need to be comfortable with a community bank leaning into newer commercial and fee based lines while still carrying the cost and complexity of expansion in Columbus and Dublin. The recent jump in quarterly earnings and stronger nine month results support that thesis, but the near term hinge is whether revenue keeps covering higher operating costs.
The main risk is that expenses tied to new branches and headquarters, plus any credit pressure from downgraded healthcare loans and Penns Woods exposures, start to bite into that earnings base. The latest results help the story, although they do not remove those cost and credit concerns.
The dividend affirmation alongside the earnings release looks like the most relevant data point for short term catalysts. Northwest Bancshares declared a US$0.20 per share quarterly payout, its 128th consecutive cash dividend, which worked out to about a 5.4% annualized yield based on the 30 September 2026 share price.
That kind of income stream can matter if you are watching how the bank funds ongoing expansion while managing credit risk. A consistent dividend sets a clear capital return commitment, which puts more focus on management’s ability to sustain current profit levels, protect net interest income, and limit any future drag from higher expenses or weaker loan performance.
Northwest Bancshares' current analyst story points to revenues of US$886.0 million and earnings of US$250.5 million by 2029, based on revenue growth assumptions of 10.6% a year and an earnings increase of about US$97.6 million from the US$152.9 million reported today.
Discover how Northwest Bancshares' fair value indicates a 4% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
Fair value marks on Northwest Bancshares from 2 private investors in the Simply Wall St Community cluster between about US$16.29 and US$27.88, which is a wide span for a single stock. You can compare those to expansion costs and credit questions around healthcare and Penns Woods loans, and decide which narrative feels more convincing.
Explore another Northwest Bancshares fair value estimate, including one that suggests a potential upside of 78% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Northwest Bancshares research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Northwest Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northwest Bancshares' overall financial health at a glance.
Looking For More Ideas Beyond Northwest Bancshares?
If you want to stress test your thesis on Northwest Bancshares, compare it with other opportunities that have clear income, balance sheet strength, or lower risk profiles. The Simply Wall St Screener can help you build that comparison set in minutes.
- For investors who want income to do more of the heavy lifting, scan a curated pool of high yielders through 4 dividend fortresses that prioritize regular cash returns.
- If capital preservation comes first for you, line up companies with sturdier finances using a focused list of solid balance sheet and fundamentals (24 results) to check which balance sheets look most resilient.
- When you are hunting for future leaders before they break into the mainstream, start with a targeted 19 high quality undiscovered gems that filters for quality businesses still off most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com