
nVent Electric (NVT) Stock Looks Reasonably Priced On Cash Flow
nVent Electric has been a strong performer over the past few years, yet its recent pullback has put fresh attention on whether the current share price lines up with the cash the business can generate. With headlines focused on new investments and expansion plans, the key issue for you is whether today's valuation is supported by the cash flows implied in its Discounted Cash Flow (DCF) intrinsic value estimate.
- Over the past 5 years, nVent Electric has delivered a 254.0% share price gain. This raises the question of how much future cash flow strength is now already reflected in the stock.
- Recent results and the planned Arizona manufacturing facility point to management leaning into data center and power utility demand. This can influence both future cash inflows and the upfront capital outlays required to sustain that growth path.
- What if you looked at nVent Electric through its earnings instead? See what nVent Electric's 29.6x P/E says about the price.
The issue now is whether the stock's current valuation is justified by the cash flows implied by its Discounted Cash Flow (DCF) intrinsic value estimate.
To see how nVent Electric compares with other power and grid focused opportunities, line it up against 43 power grid technology and infrastructure stocks.
Is nVent Electric Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) model here aims to match nVent Electric's share price to the cash it can return to shareholders over time. On the cash side, the business has generated last twelve month free cash flow of about $647.2 million, and the model then assumes that annual free cash flow continues to grow from that base through the next decade.
Analyst inputs for the outer years point to higher projected free cash generation by 2030, which helps support a valuation that sits broadly in line with the current $123.70 share price rather than far above or below it. The strong Q3 2026 update and raised full year guidance, driven by data center demand and the Maverick Power deal, help explain why the market is comfortable valuing nVent Electric close to what its projected cash flows suggest. Find out what nVent Electric could be worth using our Discounted Cash Flow (DCF) estimate.
The nVent Electric Narrative: What Would Justify Today's Price?
Narratives on nVent Electric pick up where the DCF puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or meaningfully less than today. Each one treats nVent Electric's implied fair value as a thesis about how the business might develop that you can revisit over time, and they sit together on Simply Wall St's Community page.
One of the top community narratives on nVent Electric: 19% undervalued
"The main thing that has to go right is that nVent Electric converts its expanded AI data center and power utility capacity into sustained high-margin Systems Protection revenue…"
Discover why this Narrative puts nVent Electric at 19% undervalued.
nVent Electric’s price is only one signal, insider actions are another
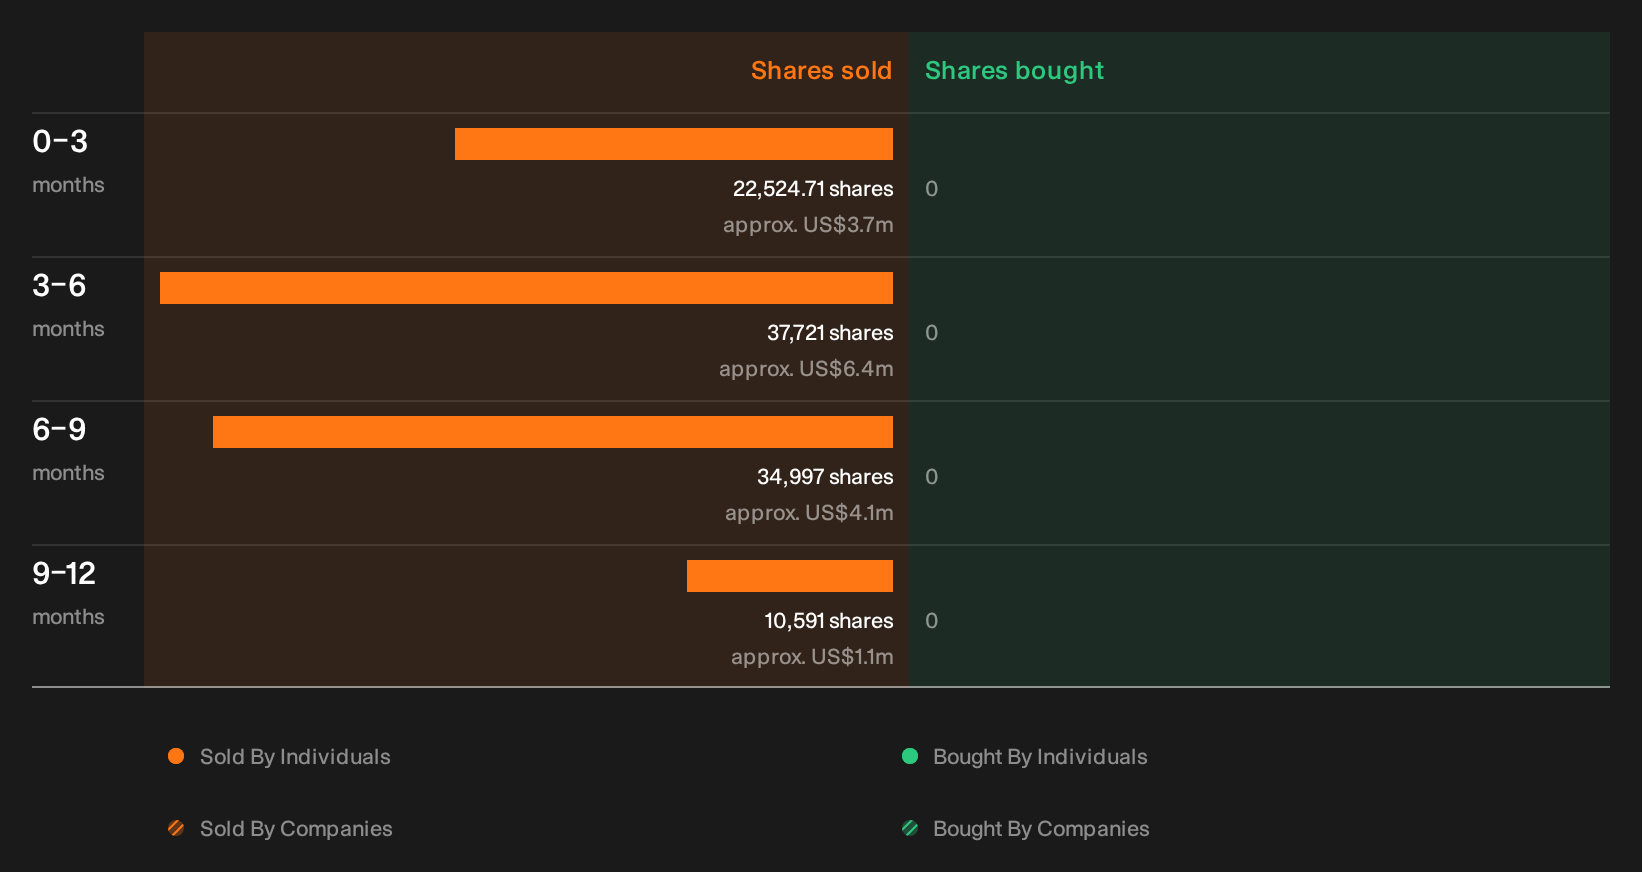
Valuation models tell you what the market is paying, but recent insider transactions can hint at how people inside the business are acting with their own holdings. See the recent insider selling flagged for nVent Electric.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com