
Is Wall Street Bullish or Bearish on Marvell Technology Stock?
Marvell Technology, Inc. (MRVL) is a fabless semiconductor company that designs, develops, and sells data-infrastructure chips for data centers, cloud computing, networking, storage, security, and communications. Headquartered in Wilmington, Delaware, the company has a market capitalization of $154.05 billion.
Marvell’s stock has risen over the past year mainly because investors see it as a major beneficiary of hyperscalers’ spending on AI data centers. Over the past 52 weeks, the stock has gained 82.9%, while it has risen 101.7% year-to-date (YTD). The company’s shares reached a 52-week high of $329.88 on June 18, but are down 48% from that level.
Meanwhile, the broader S&P 500 Index ($SPX) has gained 10.3% and 10.2% over the same periods, respectively, indicating the stock has outperformed the broader market. Next, we compare the stock with its own sector. The State Street Technology Select Sector SPDR ETF (XLK) has increased 15.9% over the past 52 weeks and 21% YTD. As a result, the stock has outperformed its sector.
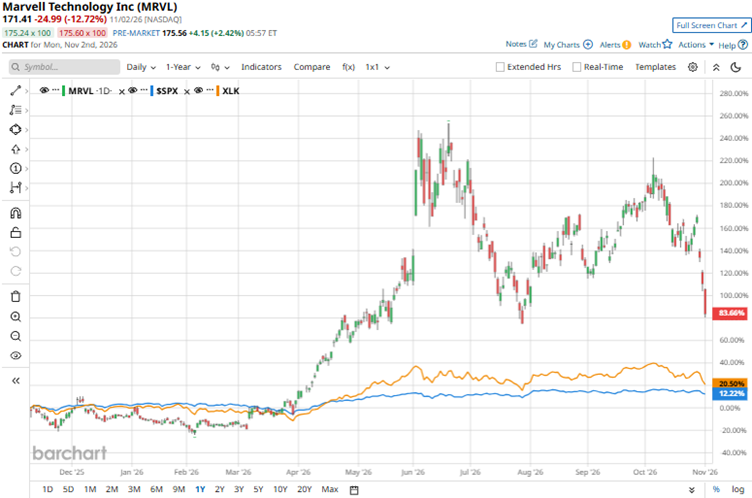
Recently, Marvell announced plans to acquire Lumentum Holdings Inc. (LITE) in an all-stock transaction, aiming to combine Marvell’s custom chips and networking technology with Lumentum’s lasers and optical components for AI infrastructure. However, investors disliked the idea, and the stock fell 12.7% intraday on Nov. 2.
Lumentum holders will receive 4.5 Marvell shares per Lumentum share, leaving them with roughly 33% of the combined company. That is expected to materially increase Marvell’s share count and dilute existing holders. The deal has an enterprise value of $115 billion, including a 23.9% premium to Lumentum’s unaffected share price. Meanwhile, the companies anticipate more than $1 billion in annual run-rate cost savings and higher adjusted EPS for Marvell in the first year after closing.
Marvell reported better-than-expected results for the second quarter of fiscal 2027 (quarter ended Aug. 1). For the third quarter, Wall Street analysts expect Marvell’s EPS to increase 27.4% YOY to $0.79 on a diluted basis. EPS is expected to increase 41.2% annually to $3.05 for fiscal 2027, followed by a 99.7% improvement to $6.09 in fiscal 2028. The company surpassed consensus EPS estimates in two of the four trailing quarters.
Among the 39 Wall Street analysts covering Marvell’s stock, the consensus is a “Strong Buy.” That’s based on 29 “Strong Buy” ratings, three “Moderate Buys,” and seven “Holds.” The rating configuration has become more bullish than a month ago, with 29 “Strong Buy” ratings, up from 28.
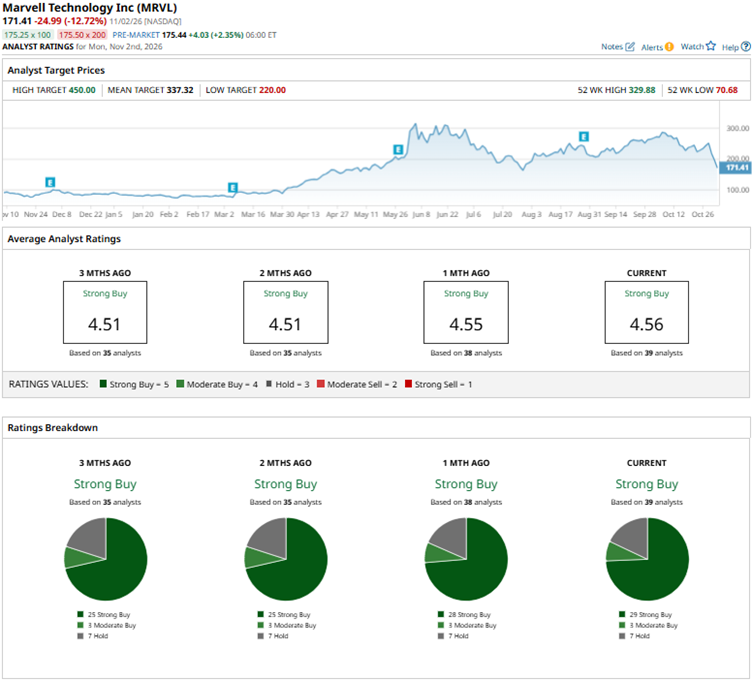
However, following the Lumentum deal announcement, analysts at TD Cowen downgraded Marvell from “Buy” to “Hold” and lowered the price target from $350 to $175. TD Cowen estimates the deal will dilute EPS by a mid-single-digit percentage in 2028. The firm also sees 2027 optical-transceiver consensus of $100 billion as too high versus its $47 billion forecast. If demand disappoints and inventories build, weaker 2028 orders could hurt Lumentum’s margins and EPS, and worsen Marvell’s deal-related EPS dilution.
Marvell’s mean price target of $337.32 implies 96.8% upside from current market prices. Moreover, the Street-high price target of $450 implies a potential upside of 162.5%.
On the date of publication, Anushka Dutta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.