
Dear Arm Stock Fans, Mark Your Calendars for November 4
The artificial intelligence (AI) rally has lost some of its shine in recent weeks, with several of its biggest beneficiaries facing a sharp reversal after an extended run-up. The staggering sums being committed to AI development have come under closer scrutiny, particularly as questions surrounding stretched valuations and the returns on these investments begin to weigh on the sector's growth narrative.
Amid this turbulence, Arm Holdings (ARM) is approaching an important earnings milestone. Its upcoming results should offer a clearer picture of how much traction its technology is gaining from the AI boom, particularly whether customer commitments are translating into actual chip shipments and how royalty income is progressing alongside licensing revenue.
That being said, Arm Holdings is scheduled to release its Q2 FY2027 results on Wednesday, Nov. 4, after the market closes. While the financial figures will naturally take center stage, the company's commentary on AI demand, customer adoption, and its forward outlook could be just as revealing in assessing the sustainability of its recent growth.
About Arm Holdings Stock
Based in Cambridge, United Kingdom, Arm Holdings develops and licenses semiconductor intellectual property (IP), covering a broad range of technologies, including central processing units (CPUs), graphics processing units (GPUs), and AI processors.
With a market cap of nearly $220 billion, its reach extends across smartphones, automotive, robotics, networking, and data centers, giving the company exposure to several fast-evolving technology markets.
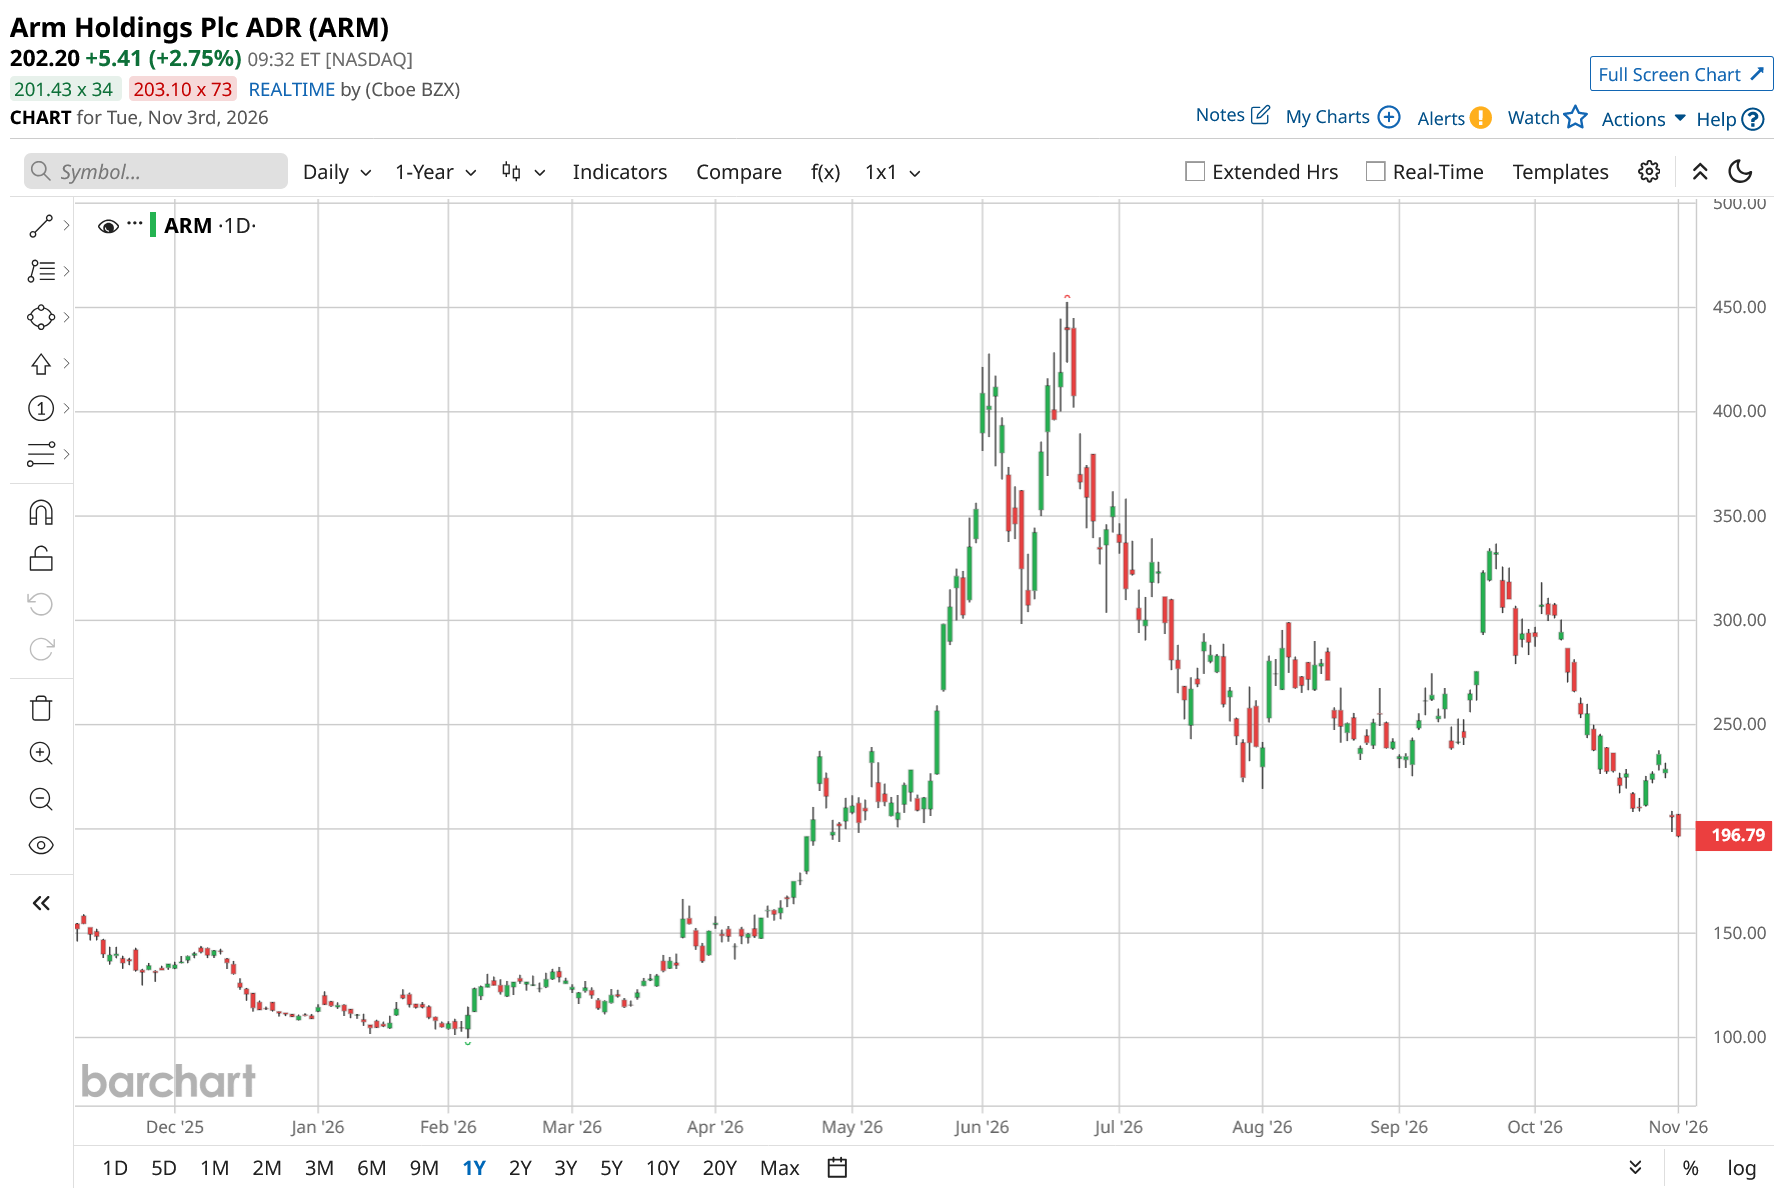
On the price performance front, Arm’s shares have delivered a rather eventful performance. The stock surged 21% over the last 52 weeks and skyrocketed 86% in 2026. However, the recent pullback has been difficult to overlook, with shares plunging 34% over the last month.
The sharp correction has done little to change the stock's premium valuation. ARM stock is currently trading at 92.39 times forward adjusted earnings and 36.31 times sales, with both multiples above their respective industry averages.
Surpasses Q1 Earnings
Arm entered FY2027 with considerable momentum, delivering a strong set of Q1 results on Jul. 29. Both revenue and earnings exceeded analyst estimates, with total revenue reaching $1.29 billion, up 22.4% year-over-year (YoY).
Royalty revenue increased 22.2% from the year-ago value to $715 million, with data center royalties more than doubling as hyperscalers expanded their use of ARM-based servers. The growing adoption of Armv9 architecture and Compute Subsystems (CSS) also contributed to the improvement, as higher royalty rates helped strengthen revenue from the company's existing technology portfolio.
Licensing revenue added to the positive performance, climbing 22.6% from the last year’s quarter to $574 million. Demand for next-generation architectures and multiple high-value customer agreements supported the increase.
For a more consistent view of licensing momentum, annualized contract value (ACV) offers a useful reference point. This measure increased 13% YoY to $1.73 billion, indicating continued progress beyond the impact of large agreements.
Profitability also rose, with non-GAAP operating income up 28.9% YoY to $531 million. The operating margin improved to 41.2% from 39.1%, while non-GAAP EPS climbed 28.6% YoY to $0.45, exceeding the upper end of management's guidance and reflecting stronger operating performance.
The stronger results came alongside higher spending, with operating expenses increasing 18.4% YoY to $733 million. Research and development (R&D) investment rose 20.5% as Arm expanded its engineering teams and continued developing next-generation architectures and its AGI CPU portfolio.
Going ahead, management has projected Q2 revenue of $1.38 billion, plus or minus $50 million, alongside non-GAAP EPS of $0.47, plus or minus $0.04. Operating expenses are expected to reach approximately $780 million, reflecting continued investment in engineering and product development.
On the other hand, analysts expect Q2 FY2027 EPS to increase 46.7% YoY to $0.22. Their full-year FY2027 projections call for EPS growth of 33.7% YoY to $1.15, followed by a much stronger 65.2% increase to $1.90 in FY2028.
What Do Analysts Expect for ARM Stock?
Arm Holdings’ outlook remains broadly positive, with several analysts highlighting the chipmaker's position in the rapidly expanding AI and advanced computing markets. Christopher Rolland of Susquehanna has maintained a “Buy” rating on the stock, accompanied by a price target of $320.
David O’Connor of Piper Sandler has also assigned ARM stock a “Buy” rating and a $320 price target.
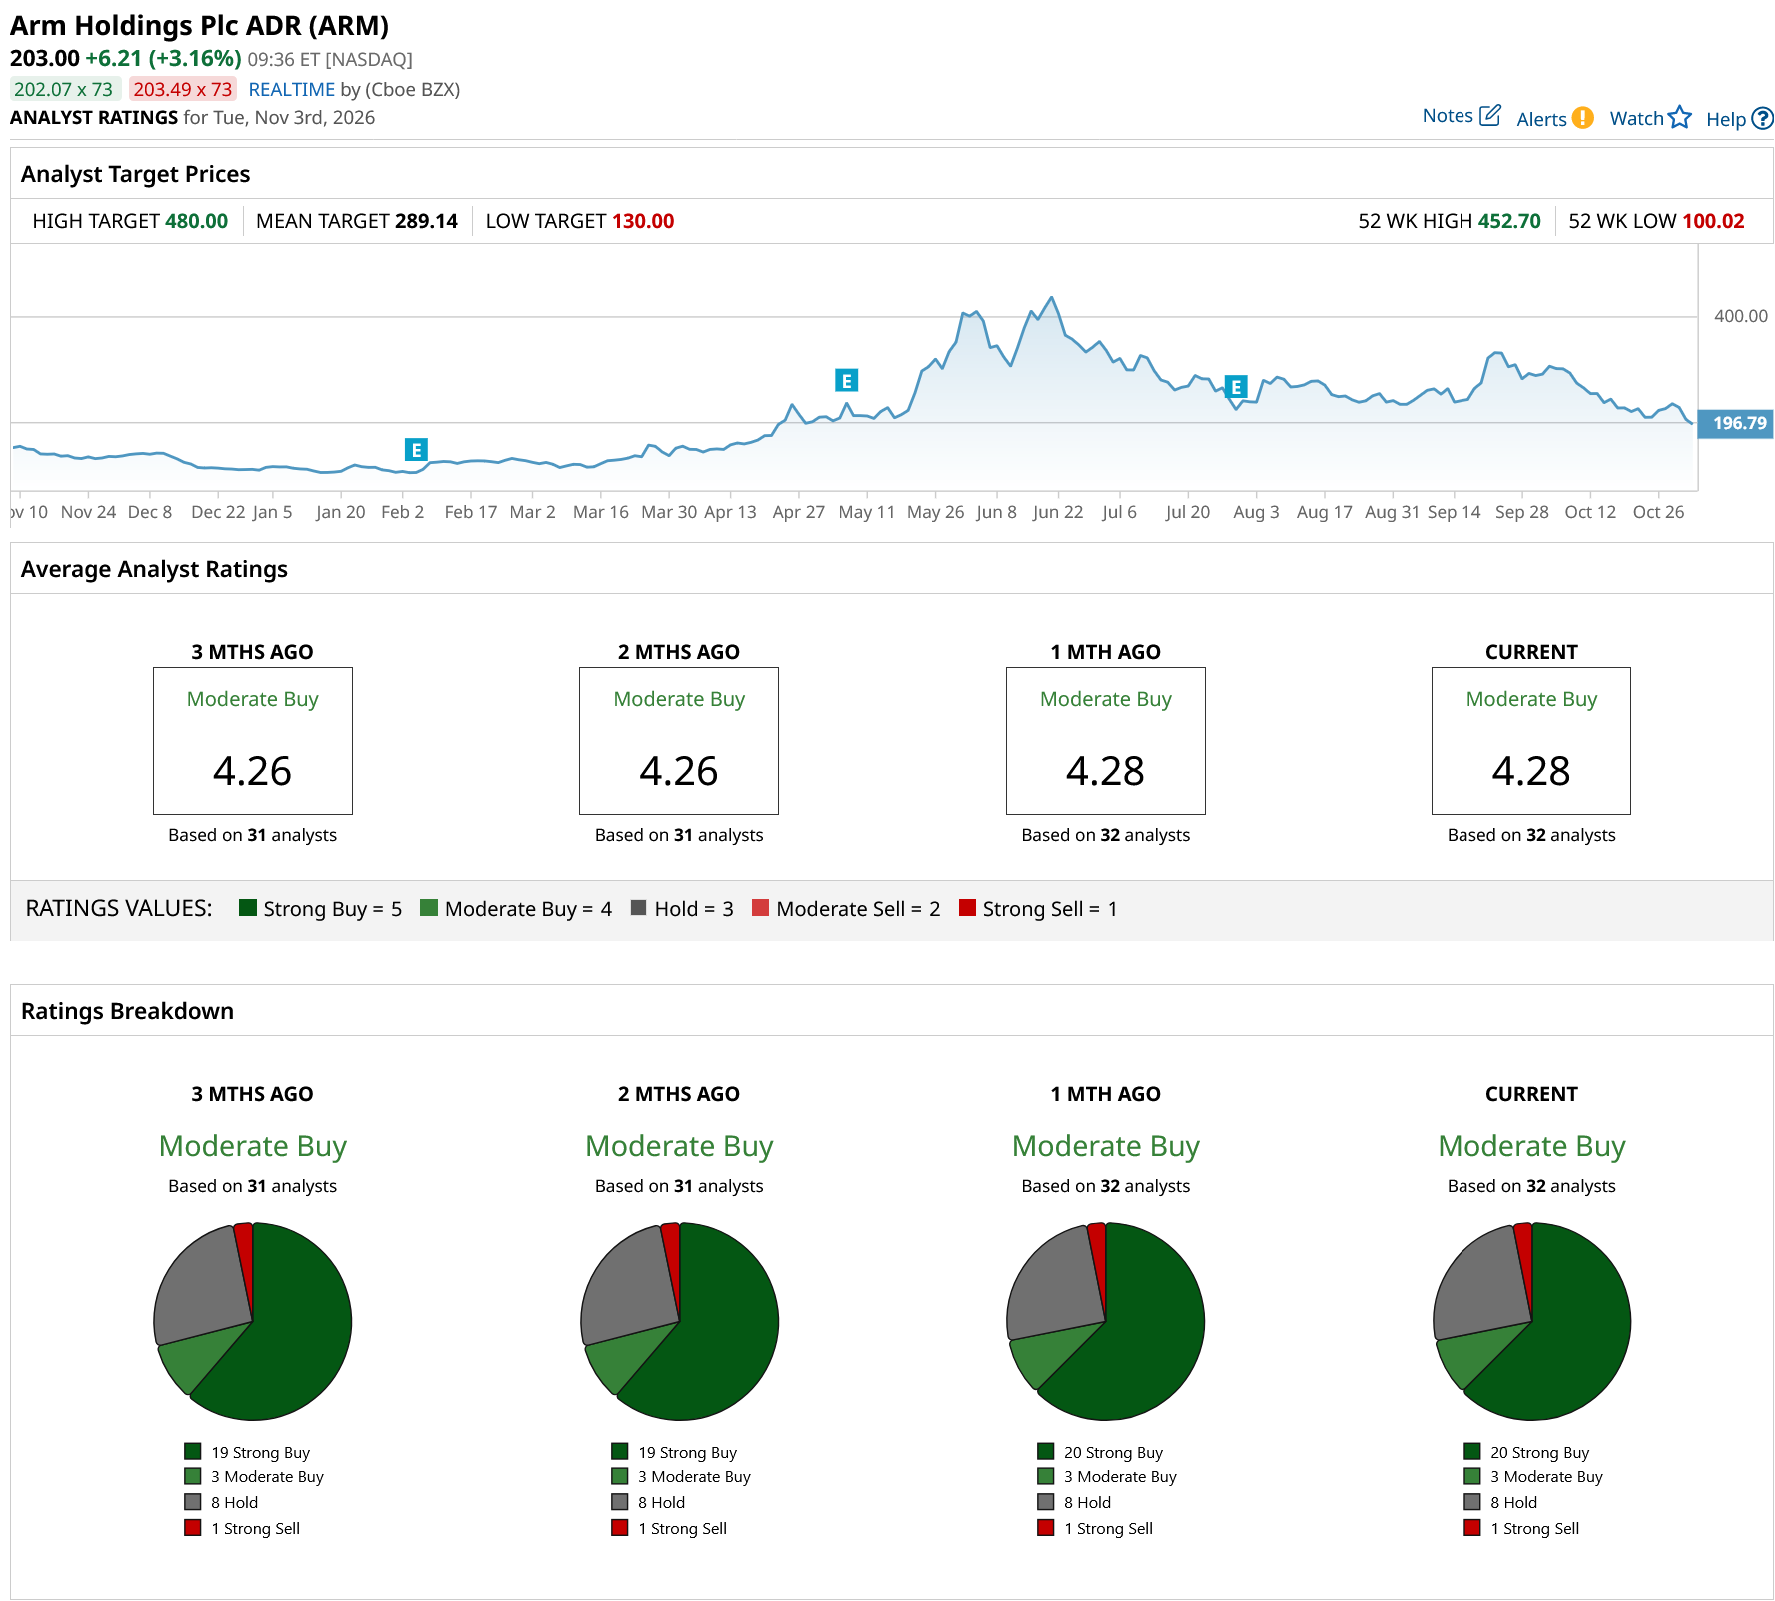
The broader analyst community shares a similarly constructive view, giving ARM stock an overall rating of “Moderate Buy.” Of the 32 analysts covering the name, 20 recommend “Strong Buy,” three assign “Moderate Buy,” eight recommend “Hold,” and one has issued a “Strong Sell” rating.
To that end, the average price target stands at $289.14, implying potential upside of 42%. At the more optimistic end of the spectrum, Bernstein's David Dai CFA has set a Street-high target of $480, pointing to a potential gain of 137% from current levels.
On the date of publication, Aanchal Sugandh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.