
Did Pipeline Intervention Just Shift Chesapeake Utilities (CPK) Investment Narrative?
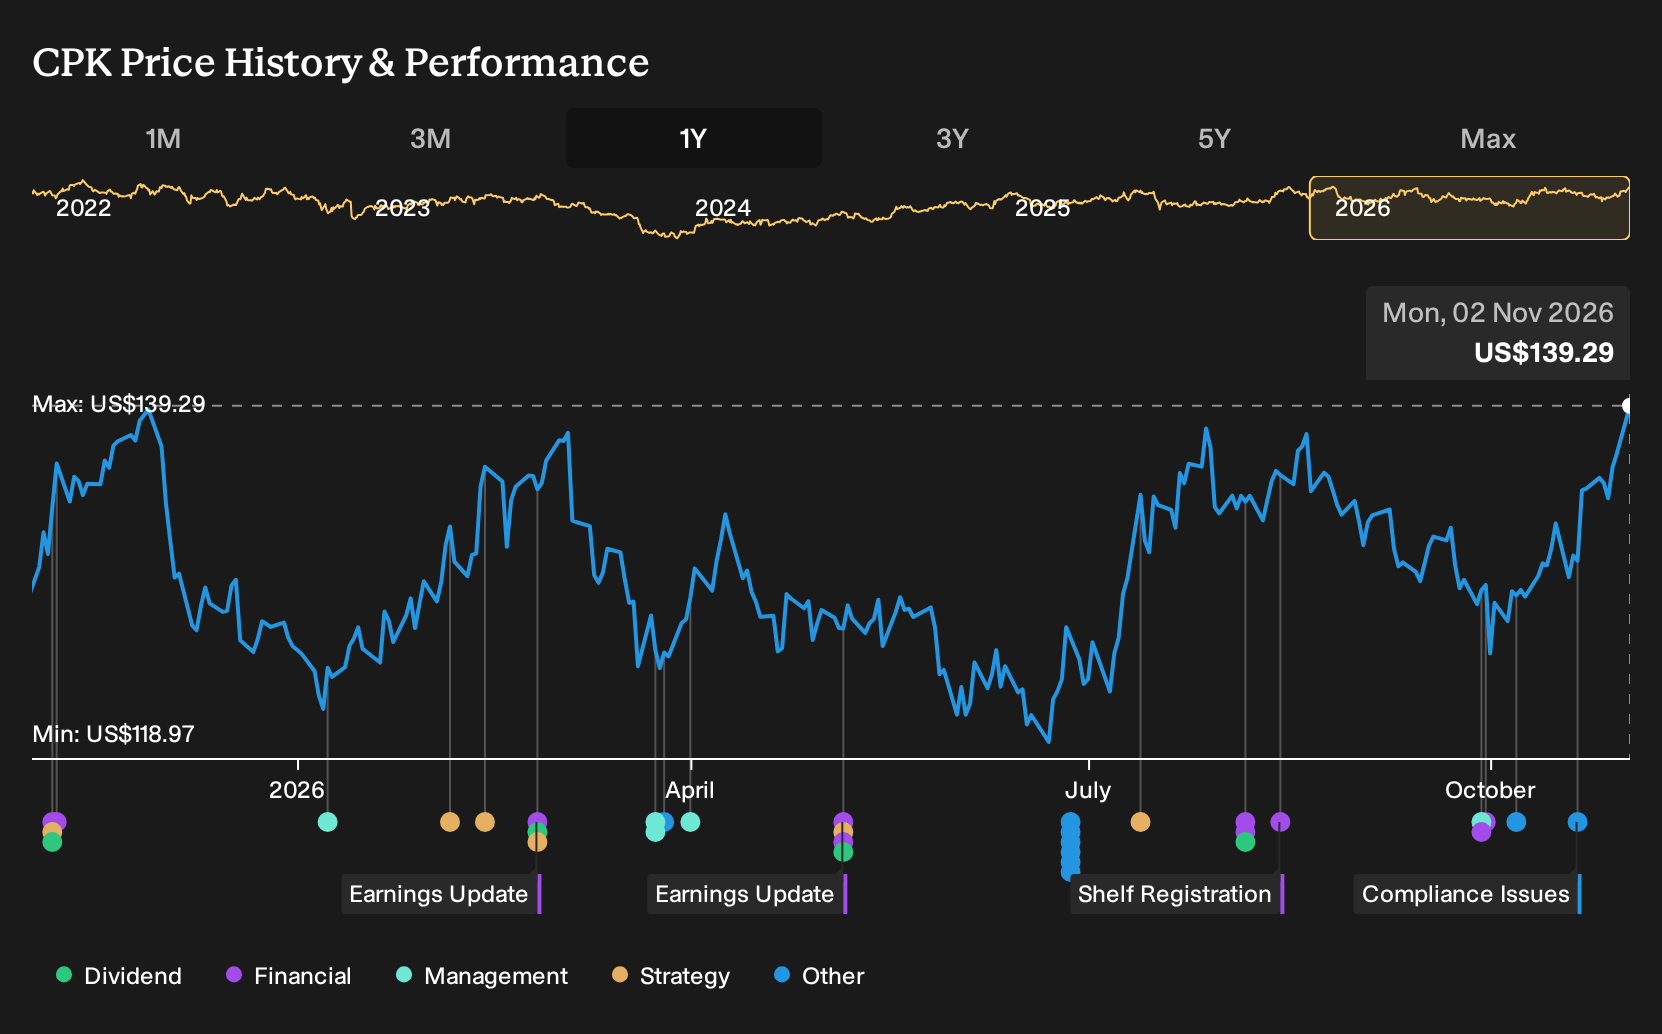
- Chesapeake Utilities’ Delaware division requested permission from the Federal Energy Regulatory Commission to intervene in Docket CP26-585-000, citing its need for transportation service from Eastern Shore Natural Gas’s proposed Delmarva Regional Enhancement Project. This filing, made in October 2026, reflects ongoing infrastructure regulatory activity.
- The motion highlights how Chesapeake Utilities relies on the Delmarva Regional Enhancement pipeline project for long term gas transportation capacity, which directly links regulatory outcomes to the company’s ability to serve customers and support its broader regulated infrastructure investment program.
- The discussion then turns to how Chesapeake Utilities’ investment narrative could be influenced by its bid to intervene in this FERC proceeding.
Scan for other regulated utilities with similar infrastructure stories by jumping into a curated list of list of solid balance sheet and fundamentals (24 results), which may echo Chesapeake Utilities’ risk and capital profile.
Chesapeake Utilities Investment Narrative Recap
To own Chesapeake Utilities, you need to be comfortable with a regulated energy player leaning heavily on a US$2.2b capital plan from 2024 to 2028 and a gas focused footprint in Delmarva and Florida. The near term story revolves around executing large projects and keeping operating costs in check, while customer growth in both regions supports the existing rate base.
The FERC intervention request around the Delmarva Regional Enhancement project looks operationally important but not thesis changing. The more immediate swing factors remain project timing, such as the WRU LNG delay already affecting 2026 EPS expectations, and how much debt or fresh equity is needed to fund US$550 million to US$600 million of 2026 capex.
Among the known projects, the WRU LNG storage facility is the clearest reference point for how execution risk can feed through to Chesapeake Utilities’ earnings profile. A timing setback here has already trimmed 2026 EPS expectations by about US$0.10, which gives a concrete sense of how delays or cost recovery issues on future work could affect returns on the broader capital plan.
Seen against that backdrop, the Delmarva Regional Enhancement proceeding matters because it is part of the same regulated buildout that underpins the long term investment story. If approvals, construction and rate recovery on projects like Delmarva and Florida Energy Pathway track to plan, the large capex budget, current P/E premium and balance sheet stretch risk tied to debt coverage could look more manageable to shareholders focused on multi year regulated earnings growth.
Chesapeake Utilities' current consensus framework points to revenue of US$1.2b and earnings of US$210.0 million by 2029, based on analysts’ assumption of 5.6% yearly revenue growth and an earnings increase of about US$59.8 million from US$150.2 million today.
Discover how Chesapeake Utilities' fair value indicates a 6% potential upside to its current price that may not last much longer.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Chesapeake Utilities research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Chesapeake Utilities. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Chesapeake Utilities' overall financial health at a glance.
Looking for more Chesapeake Utilities style investment ideas?
Chesapeake Utilities may fit your playbook today, but you can round out your watchlist by using the Simply Wall St Screener to hunt for other regulated or resilient businesses that line up with your risk tolerance and return goals.
- If you want potential mispricing with quality in mind, consider a curated set of 34 high quality undervalued stocks that combine fundamental strength with more modest valuations.
- For income focused investing, you can scan for companies built around reliable cash generation and payouts by checking out a selection of 4 dividend fortresses that may suit a yield driven approach.
- When capital preservation matters most, you might prefer businesses with steadier financial profiles, so filter for a group of 29 resilient stocks with low risk scores that aim to keep downside risk contained.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com