
Raised Guidance Could Be A Big Moment For V2X Stock (VVX)
- V2X, Inc. reported third quarter 2026 sales of US$1,271.46 million and net income of US$31.99 million, raised full year 2026 revenue guidance, and filed an omnibus shelf registration covering common stock, preferred stock, debt securities, warrants, and units.
- The mix of higher earnings per share from continuing operations, together with a new universal shelf registration, gives V2X additional flexibility to fund contracts, manage its balance sheet, or pursue acquisitions while its backlog and guidance support operational visibility.
- We will look at how V2X's raised 2026 guidance reshapes the investment narrative that was built around backlog and modernization work.
Scan how V2X's contract wins and raised guidance compare with other contractors by reviewing the hand picked 43 power grid technology and infrastructure stocks shaping long-term defence and infrastructure spending.
V2X Investment Narrative Recap
To stay on board with V2X, you need to believe that record backlog, modernization work and AI enabled programs can keep supporting revenue, margin and earnings progress even as some regions soften. The raised full year 2026 revenue guidance signals management confidence in the near term operating setup rather than a wholesale change in the story.
The most important short term swing factor remains execution on recent contracts and converting awards into higher margin work. Middle East pressure, including a 30% revenue decline in that region in Q3, still looks like the key risk that could cap near term top line progress and offset mix benefits.
The filing of an omnibus shelf registration sits right in the middle of these catalysts. It adds financing flexibility at a time when V2X is leaning into modernization, engineering and AI heavy programs that are supported by a large backlog and raised 2026 revenue guidance in the US$4,950 million to US$5,100 million range.
For you as a shareholder, the shelf is most relevant as a tool that can help fund working capital for large contracts, reduce refinancing risk where interest coverage is a watchpoint, or support acquisitions that deepen exposure to higher margin services. The trade off is that any future equity issuance could dilute returns if execution or contract quality disappoints.
V2X's current analyst story points to revenues of US$5.6b and earnings of US$231.4 million by 2029. This outlook is built on an assumed 4.8% yearly revenue growth rate and an earnings increase of about US$139.6 million from current earnings of US$91.8 million.
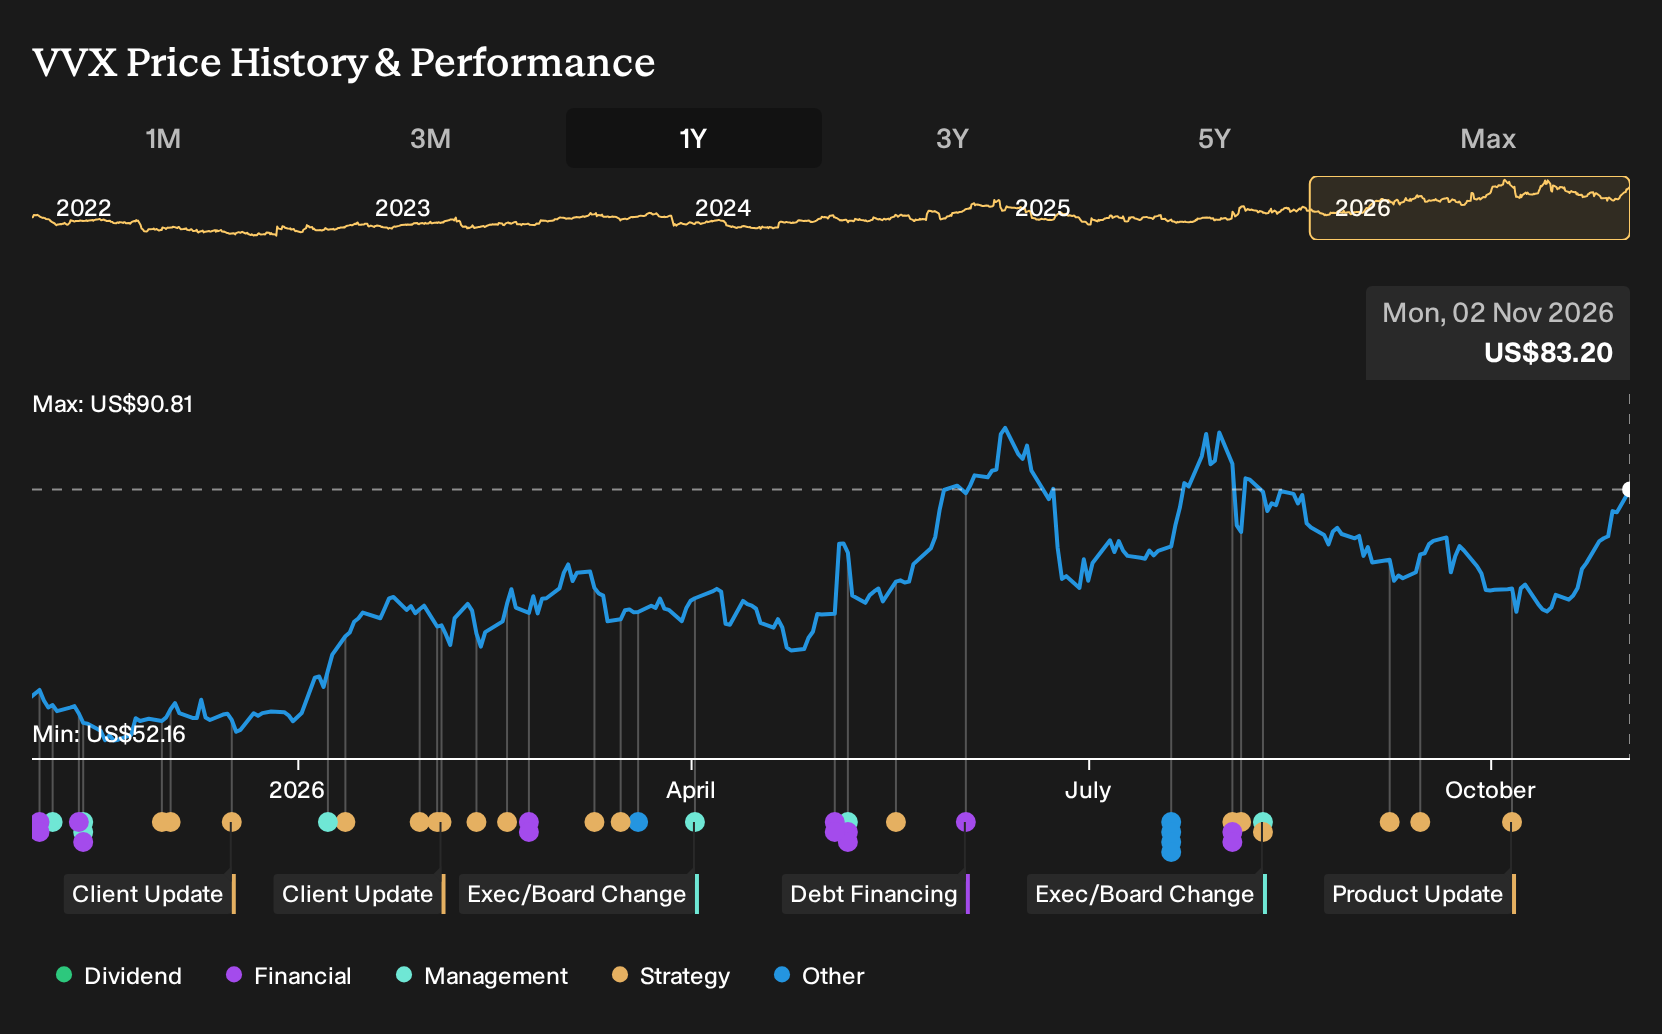
Uncover why V2X's fair value indicates a 7% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on V2X focuses on the AI push as the real swing factor. Bullish analysts were already modeling revenue of about US$6.2b and earnings near US$304.9 million by 2029, well above consensus. Those projections came before this quarter and the new shelf, so you should expect opinions to shift as fresh data lands.
Explore 3 other V2X fair value estimates, including one that suggests as much as 162% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your V2X research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for V2X. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate V2X's overall financial health at a glance.
Looking For More Ideas Beyond V2X?
If V2X has sharpened your thinking about contract driven stories, it can help to line it up against other opportunities using the Simply Wall St Screener. That way you can compare quality, risk and income potential side by side instead of looking at this stock in isolation.
- If you want to focus on financial strength, start with companies that pair clean balance sheets with resilient fundamentals by running the list of solid balance sheet and fundamentals (24 results).
- For value hunters, scan businesses that combine quality metrics with prices that may sit below underlying fundamentals by checking the 34 high quality undervalued stocks.
- If your priority is steadier cash returns, you can filter for robust income payers with higher yields through the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com