
What Hongkong Land Doubters Overlooked
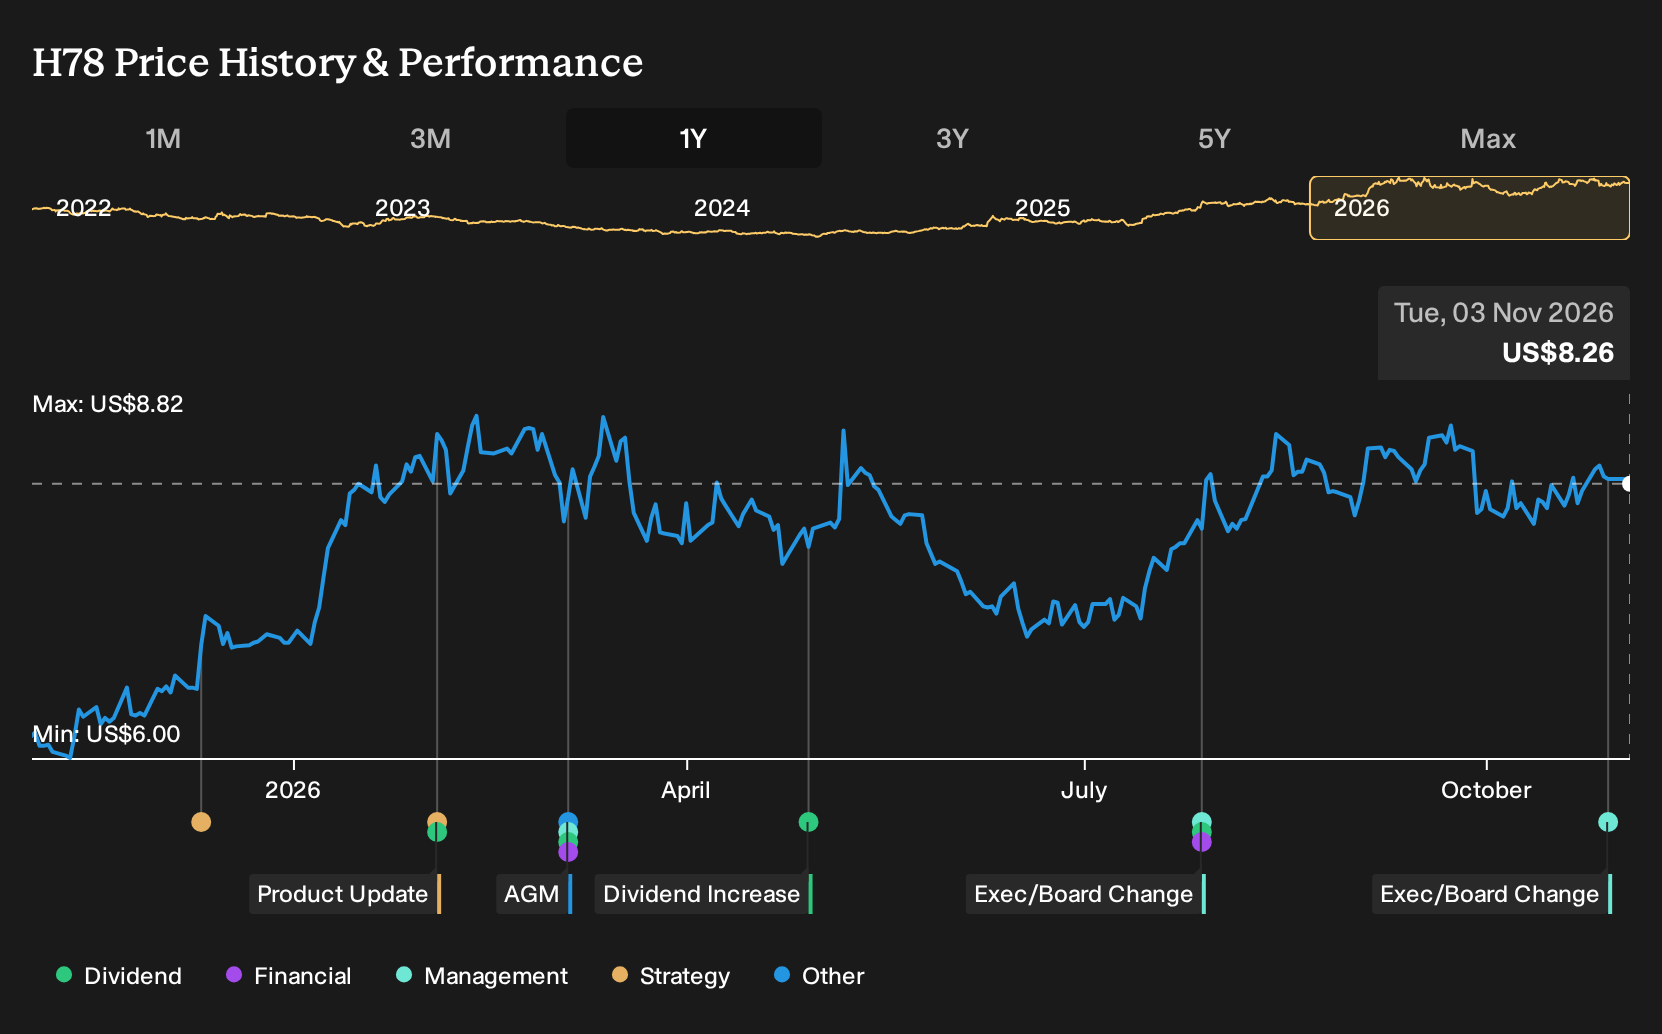
If you only glanced at the headlines around Hongkong Land in late 2025, the loudest disagreement was over what remote work and green capex might do to its towers in Central. Holding Hongkong Land over the past year would have returned 39.8%, including dividends. If you had been weighing those bullish and bearish cases on 3 November 2025, what exactly in the record justified taking that ride on such a divided story?
The easy part of this move is behind Hongkong Land. Zero in on 194 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Hongkong Land Investors Had To Choose Between
The shares cost US$6.21 at the start of the period, and Hongkong Land was being pulled between two very different stories about what its future towers and developments might earn.
On the bullish side, one camp argued that Asian urbanization and green upgrades would keep its prime CBD space in demand. This group pointed to a Fair Value of US$7.42, a price implied by assumptions such as 15.3% annual revenue growth and profit margins rising to 46.7% over three years.
The opposing, more cautious view focused on remote and hybrid work eroding demand for premium offices. This camp saw a Fair Value of US$4.88, based on revenue falling 12.3% a year and concern that capital-heavy projects in Mainland China could weigh on earnings stability.
What The Evidence Around Hongkong Land Actually Tested
Hongkong Land’s mid 2026 numbers gave the bullish camp fresh support on profitability. Net income excluding one offs moved from US$220.9 million in H1 2025 to US$1,259.5 million in H1 2026, while reported revenue shifted from US$751.2 million to US$632.7 million. That mix of higher earnings on a smaller top line meant the evidence cut both ways for the original debate.
The key assumption investors can reuse elsewhere is about how higher returns are achieved. Do not just track headline growth. Compare revenue, profit and the share count to see whether any improvement is coming from stronger operations, financial engineering such as buybacks, or a blend of both.
What Hongkong Land’s One Year Run Now Asks You To Believe
After a 39.8% gain over the past year, Hongkong Land now trades at US$8.26. The selected Narrative argues that its Fair Value still sits above that quote, largely because of a shift in focus from rent on owned towers toward fee income and leaner portfolio wide operations.
The Narrative’s core claim is that today’s price does not fully credit Hongkong Land for growing third party assets under management, expanding fee based earnings, and squeezing recurring savings from a portfolio led model. It also argues that anyone buying now has to judge whether that mix can keep compounding without simply leaning on higher rents.
"Key Takeaways Bullish analysts expect Hongkong Land Holdings to use its fee-based fund management platform and capital recycling programme to grow assets under management and recurring income in a way that the current share price does not fully anticipate. The main condition for this view is that Hongkong Land Holdings continues to recycle balance sheet capital from build-to-sell projects into higher-yielding prime commercial assets and third-party-capital-backed vehicles while keeping gearing low."
The price and this Narrative do not agree. → Uncover what this Narrative says Hongkong Land is actually worth
How Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 41% below our estimate - sells peripherals built around an internal AI platform for work, gaming and collaboration.
- Company 2 - 40% below our estimate - shifts from underwear into broader sports fashion using digital first, multichannel distribution.
- Company 3 - 39% below our estimate - expands AI driven hiring and local services platforms charging businesses for higher intent access.
Three companies from the same screener. Open all 196 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com