
Will Lower Q3 Profit Change Philips' Stock Narrative
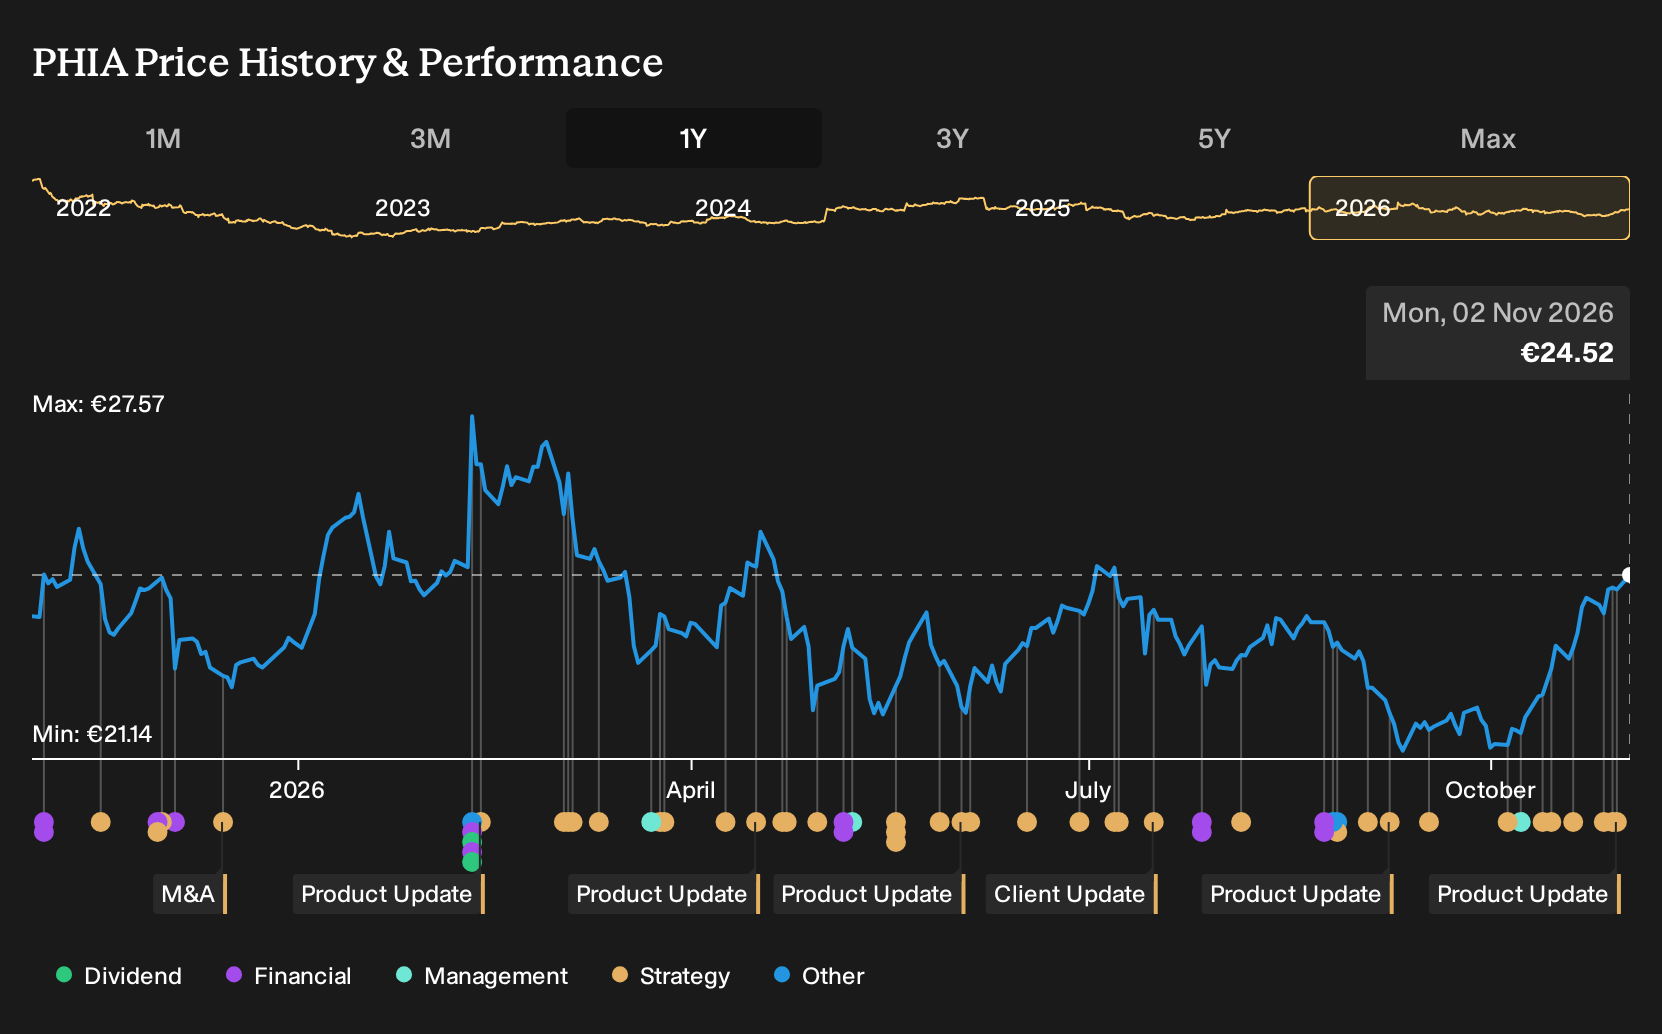
- Koninklijke Philips reported third quarter 2026 sales of €4,393 million, slightly above the prior year, while quarterly net income fell to €27 million and earnings per share from continuing operations were €0.03.
- Over the first nine months of 2026, Philips generated broadly stable sales of €12,658 million but higher net income of €562 million, which points to pressure in the latest quarter rather than across the entire reporting period.
- The next focus is on how Philips' weaker third quarter profitability fits with the existing investment narrative around margin improvement.
Koninklijke Philips Investment Narrative Recap
To stay on board with Koninklijke Philips, you need to believe the health tech portfolio can translate stable sales into cleaner, more consistent earnings. The third quarter results cut against that story in the short term. Net income fell sharply even as sales barely moved, which keeps cost control, product mix and pricing discipline front and center.
The key near term catalyst is execution on higher margin Diagnosis & Treatment and informatics offerings that previously supported better profitability. The big risk is that regulatory spending, hospital budget pressure and tariff or input cost issues keep recurring expenses elevated. This quarter hints that profitability progress is not yet on firm ground.
Against that backdrop, the HyperVue Integrated System with X1 FFR in the U.S. looks closely tied to the Philips earnings debate. It directly targets coronary procedures where clinicians want richer data without extra workflow friction. If uptake is solid, that type of fixed room install can support more recurring disposables, software and service revenue over time.
For you as an investor, the question is whether Philips can scale platforms like HyperVue and UniGuide fast enough to offset softer quarters such as this one. Execution risk is real, since hospital capital budgets and regulatory oversight can slow adoption. The potential benefit, if it materialises, would be a larger share of higher value, AI supported cardiology work.
Koninklijke Philips' current analyst script points to revenue of €20.0b and earnings of €1.7b by 2029, built on forecast yearly top line growth of 4.1% and an earnings step up of about €0.6b from roughly €1.1b today.
Uncover why Koninklijke Philips' fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Koninklijke Philips focuses less on HyperVue or UniGuide traction and more on the risk that tariffs and cost inflation keep earnings under strain. The most cautious analysts were only pencilling in about €19.9b of revenue and €1.6b of earnings by 2029, before this quarter, which reflects a meaningfully more pessimistic path. These expectations sit below consensus and show how far opinions can differ, so it makes sense to compare several narratives and see which assumptions feel closest to your own.
Explore 4 other Koninklijke Philips fair value estimates, including one that suggests up to 14% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Koninklijke Philips research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Koninklijke Philips. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Koninklijke Philips' overall financial health at a glance.
Looking For More Investment Ideas Beyond Koninklijke Philips?
If the Koninklijke Philips story has sharpened your focus on earnings quality and balance sheet strength, it can help to widen the lens and scan for other opportunities with similar traits. The Simply Wall St Screener lets you filter the market using fundamentals so you can build a shortlist that actually matches your risk and return preferences.
- If capital preservation sits high on your list, start with companies that carry lower assessed risk and steadier profiles through the 215 resilient stocks with low risk scores.
- For readers hunting for mispriced quality, look at businesses that combine stronger fundamentals with valuations that screen as potentially cheap by checking the 194 high quality undervalued stocks.
- Income focused investors who care about steady cash flows may prefer businesses with cleaner finances and robust asset backing, which you can filter using the list of solid balance sheet and fundamentals (196 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com