
Allient (ALNT) Following Its Sharp Pullback The Valuation Debate Gets Harder
Allient stock performance after recent moves
Allient (ALNT) has drawn fresh attention after a sharp pullback, with the share price closing at US$84.17 and logging declines over the past week, month, and past 3 months.
That reset in the stock creates a clear tension for investors who are weighing Allient’s recent return profile against its financial scale, including US$574.782 million in revenue and US$28.608 million in net income.
Recent trading tells a mixed story. Short term momentum has clearly faded, with the 30 day share price return down 28.85%. Even so, Allient still sits on a 51.44% year to date share price gain and a very strong 225.08% total shareholder return over three years.
Scan a curated set of motion control and industrial specialists by comparing Allient with 95 robotics and automation stocks, which may also be reacting sharply to recent price swings and earnings momentum.
After a 29% slide over 30 days but a 51% gain year to date, the real puzzle is whether Allient now tilts more toward opportunity or downside as valuation comes into focus next.
Most Popular Narrative: 29% Undervalued
Allient’s most followed narrative pegs fair value at $118 per share, which sits well above the recent $84.17 close and puts the current pullback in a different light for anyone anchoring on long term cash flow assumptions.
The main thing that has to go right is that Allient converts its current record bookings, growing backlog and mix shift toward higher-margin sectors into sustained earnings quality, while managing execution risks from restructuring and the Dothan facility transition.
The numbers imply that Allient’s share price already reflects a bullish view on future cash flows and margin gains, with current valuation work suggesting the stock may be priced above some cash flow models, even though this narrative holds that Allient is fairly valued.
See why 8 investors see Allient as 29% undervalued.
Result: Fair Value of $118 (UNDERVALUED)
Still, this fair value story can break if record margins tied to STAN savings fade, or if restructuring costs around the Dothan transition remain stubbornly high.
Find out about the key risks to this Allient narrative.
Another View on Allient’s valuation
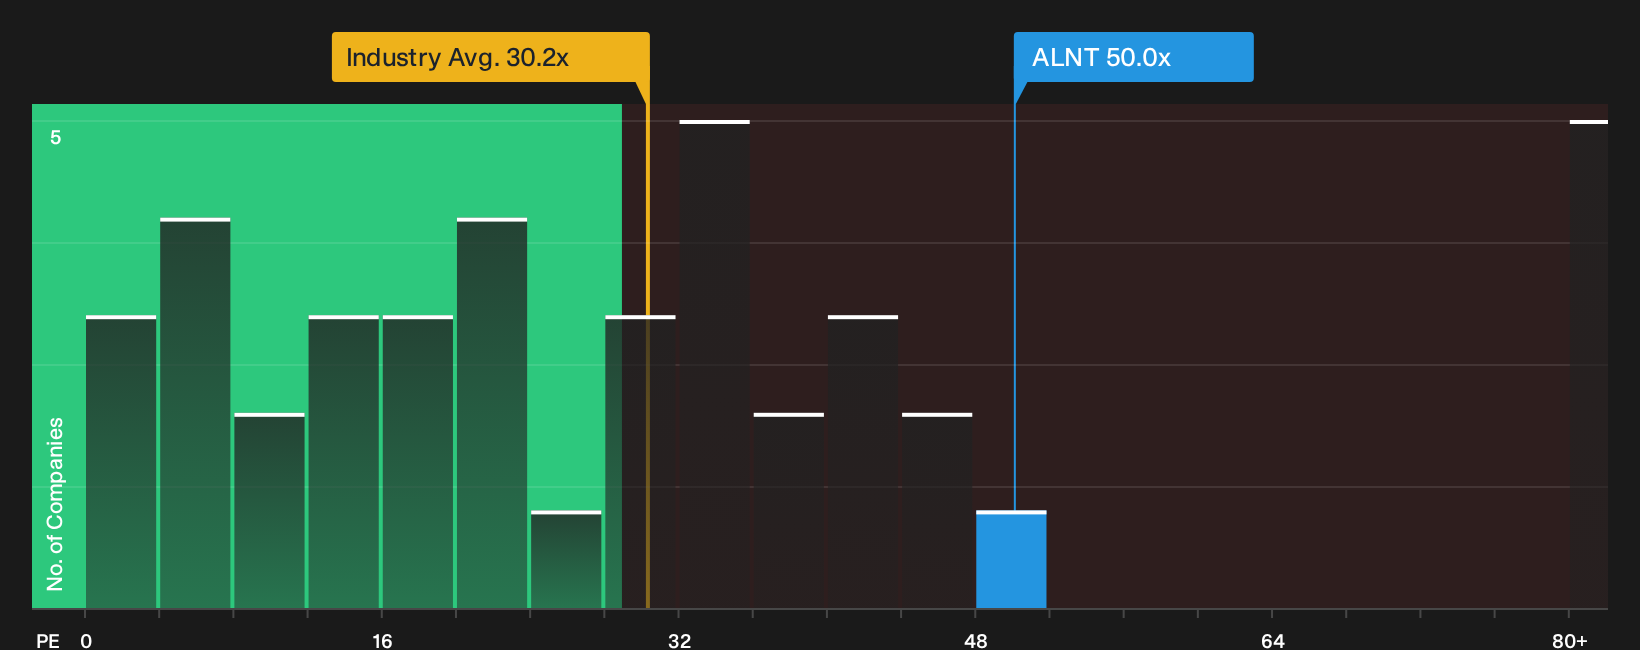
The first narrative leans on future cash flows and lands on a fair value of $118 per share. A simple earnings multiple paints a sharper picture. Allient trades on a P/E of 50x, while the US Electrical industry averages 30.2x and direct peers sit around 25.6x. The fair ratio is 23.1x, which is less than half the current level and points to meaningful valuation risk if sentiment cools. Is that premium a margin story that holds, or a crowd that has moved too far ahead of itself?
To pressure test that gap against earnings assumptions and market expectations, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
For a quick visual sense of how Allient’s current pricing stacks up against sector norms, review the P/E comparison in
Next Steps
Mixed messages on Allient can create more questions than answers, so move quickly, test the numbers yourself, and weigh both sides with 3 key rewards and 1 important warning sign.
Looking for more Allient investment ideas?
If Allient has sharpened your focus, do not stop here. Broaden your watchlist now and give yourself more ways to put your capital to work.
- Target quality at a discount by scanning a focused pool of companies on the 34 high quality undervalued stocks.
- Strengthen downside protection by zeroing in on businesses with resilient finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for future leaders before the crowd pays attention by tracking opportunities through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com