
Downer EDI (ASX:DOW) Could Be 6% Undervalued After The $400 Million Homes Victoria Win
Downer EDI (ASX:DOW) has secured a Homes Victoria contract worth about A$400 million over a period of up to nine years, covering responsive maintenance and repair services for social housing across the East Division.
At a share price of A$7.31, Downer EDI has seen short term momentum pick up, with a 1 month share price return of 7.03% and a 7 day gain of 3.10%. This has occurred even though the 90 day share price return declined 8.40% and the 1 year total shareholder return is marginally down 0.39%. After a very large 3 year total shareholder return of about 7x that shorter term figure, this suggests sentiment has cooled recently, while longer term holders have still seen substantial value creation.
Spot list of solid balance sheet and fundamentals (12 results) that, like Downer EDI, are securing long dated contracts and pairing operational scale with resilient financial foundations.Downer EDI now combines a fresh A$400 million contract with a share price that has already moved higher in the short term. Does that recent optimism still leave enough upside to justify the risk?
Most Popular Narrative: 6% Undervalued
Against a last close of A$7.31, the most followed narrative pegs fair value for Downer EDI at A$7.78. This points to a modest discount backed by a detailed earnings and cash flow view using a 7.25% discount rate.
The analysts have a consensus price target of A$7.78 for Downer EDI based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of A$8.3, and the most bearish reporting a price target of A$6.9.
See why 13 investors see Downer EDI as 6% undervalued.
Result: Fair Value of A$7.78 (UNDERVALUED)
Still, the story can change quickly if Australian telco demand stays soft or if government outsourcing priorities shift away from long dated facilities contracts.
Find out about the key risks to this Downer EDI narrative.
Another View: What The P/E Says About Downer EDI
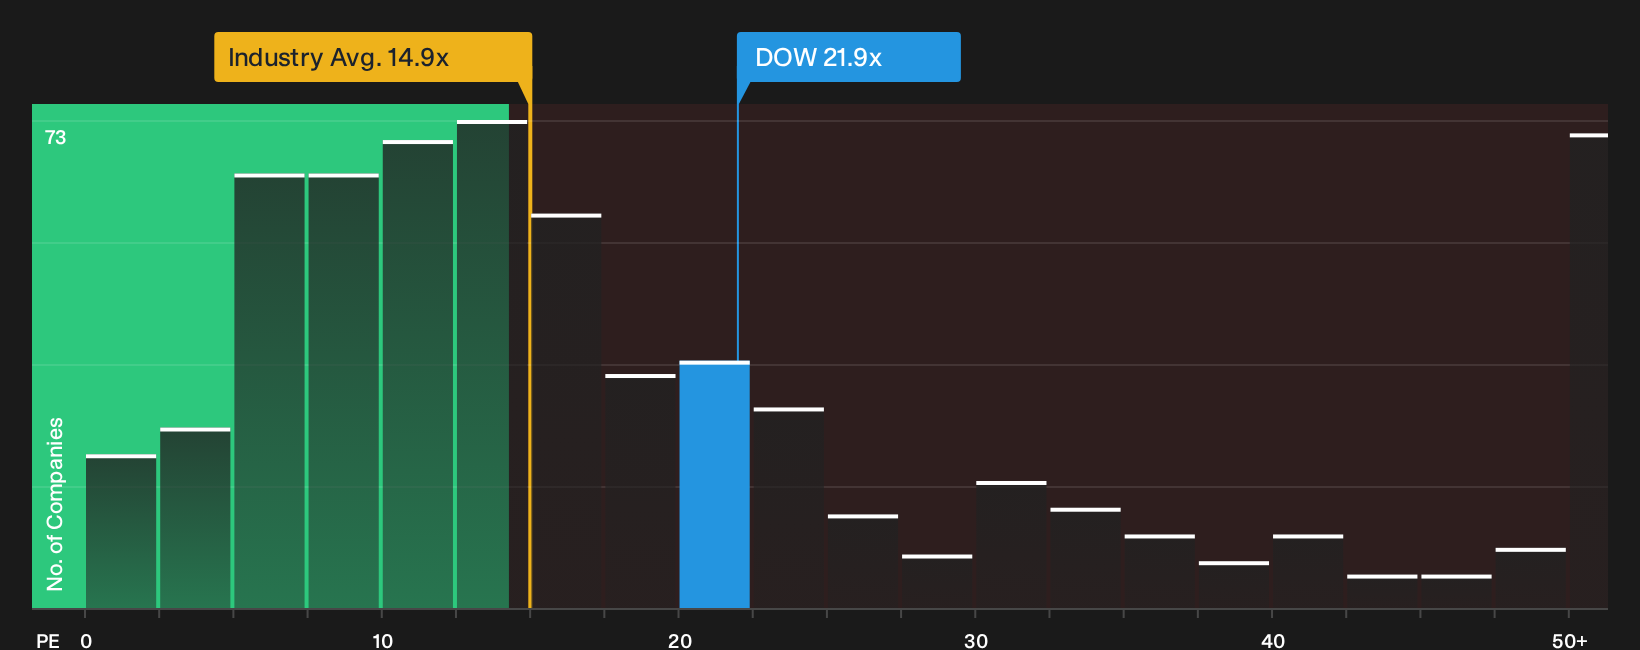
On analyst forecasts and fair value models, Downer EDI looks slightly undervalued. Yet the A$7.31 share price already implies a P/E of 21.9x, which is higher than the global Commercial Services industry at 14.9x and above peers at 20.1x.
The fair ratio points to 26.2x as a level the market could move towards. Investors weighing upside also need to weigh the risk of the multiple drifting closer to sector norms instead. Which side of that gap feels more realistic to you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or quiet opportunity? If you want to move quickly and rely on your own judgement instead of the crowd, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Downer EDI?
If you like the mix of contracts and valuation at Downer EDI, broaden your watchlist now so you are not stuck reacting after the best ideas move.
- Target potential mispricing by scanning a focused group of quality opportunities through the 3 high quality undervalued stocks.
- Prioritise resilience by filtering for companies with strong financial footing and flexible balance sheets using the list of solid balance sheet and fundamentals (12 results).
- Hunt for future leaders by tracking a curated pool of under followed opportunities in the 14 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com