
Did AGM Commentary Just Shift Reece (ASX:REH) Investment Narrative?
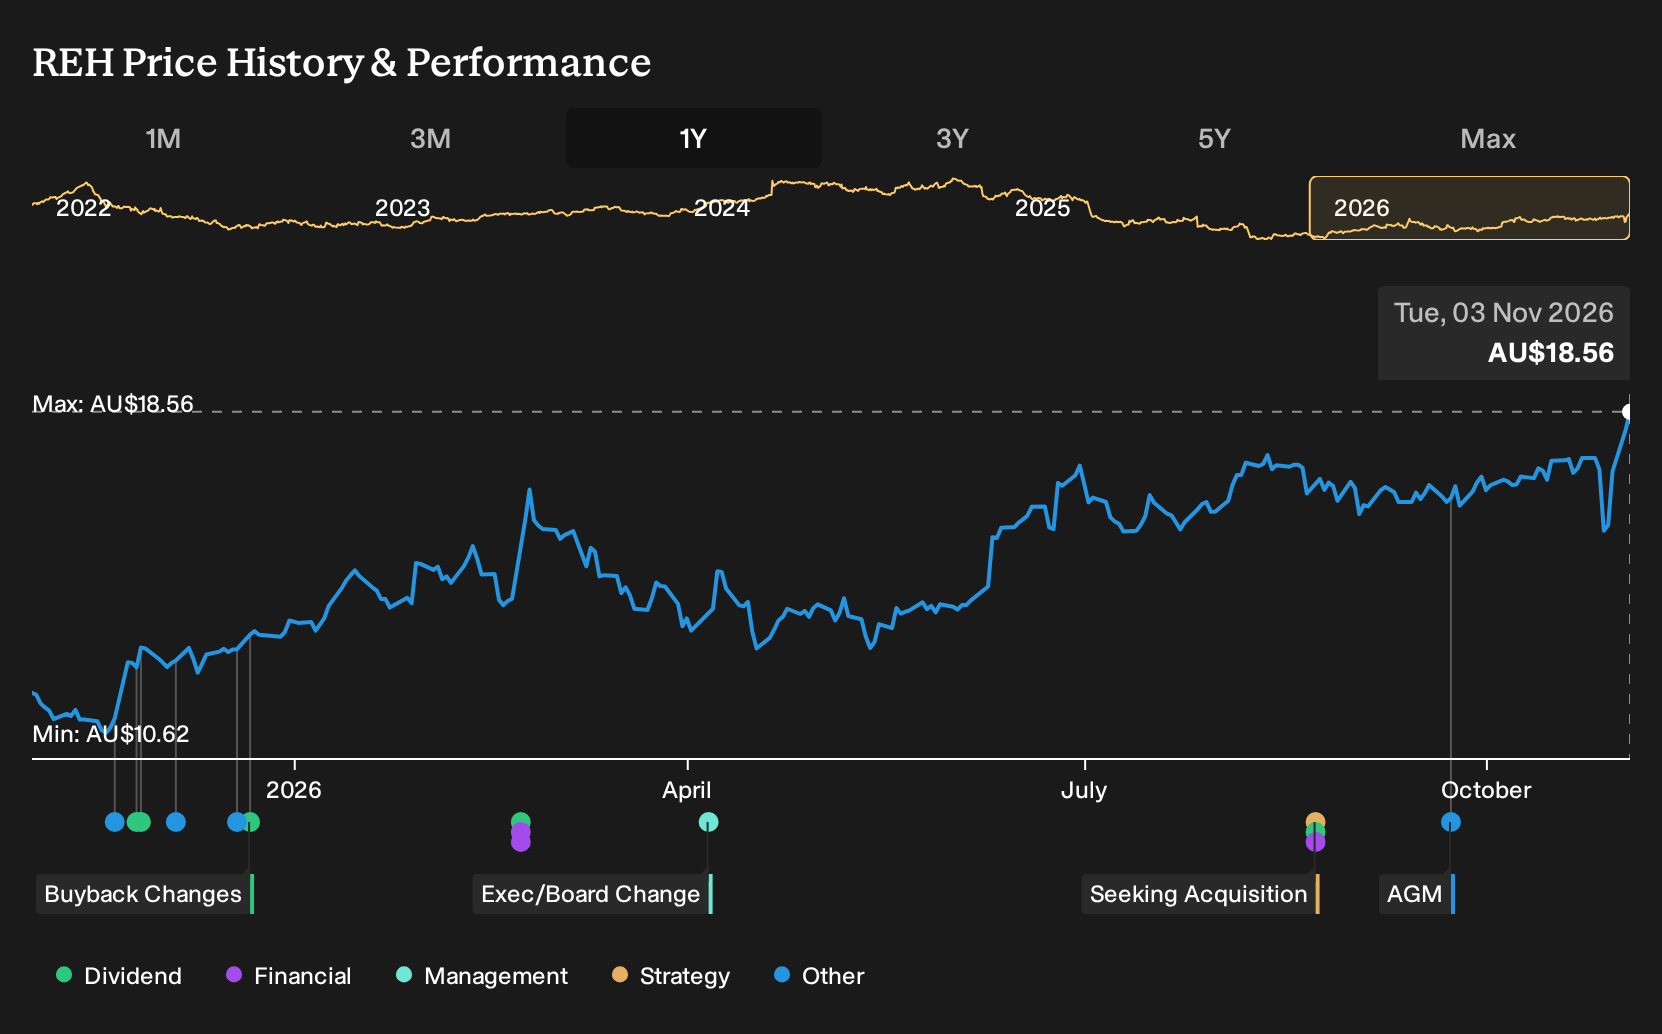
- Reece, the plumbing and heating product distributor, saw its shares move after investors reacted to AGM commentary alongside recent full year and Q1 FY27 figures. This occurred in the context of an upcoming RBA cash rate decision from 4.6%, which is shaping expectations for borrowing costs.
- An important angle is how Reece’s exposure to interest rate sensitive renovation and construction activity places extra weight on management’s AGM messaging about demand and cost discipline at a time when markets are focused on potential shifts in RBA policy.
- We will look at how Reece's investment narrative interacts with AGM commentary as markets assess its exposure to RBA interest rate decisions.
Compare how Reece stacks up against other interest rate sensitive plays by scanning our hand picked list of solid balance sheet and fundamentals (12 results) that may better handle higher funding costs.
Reece Investment Narrative Recap
To own Reece, you need to be comfortable with a plumbing and HVAC distributor that is still investing heavily in branch rollout and digital tools, while its end markets are sensitive to interest costs. The short term swing factor is trading conditions in renovation and construction as the RBA decision feeds through to borrowing and project pipelines.
The biggest near term risk is that already weak U.S. housing activity and softer demand in other regions keep like for like sales under pressure, while new branches and tech spending keep costs high. AGM commentary has sharpened the focus on how disciplined Reece can be on margins and cash while it waits for better volumes.
The AGM update linked to recent full year and Q1 FY27 figures is the key disclosure investors are reacting to. Management comments on demand, pricing and cost control give you a real time feel for how the A$9.4b revenue base is holding up into a rate decision that could push the cash rate above 4.6%.
For you, the read through is simple. If the AGM tone on U.S. losses, margin pressure from expansion and payback on digital tools like Copilot and the maX app sounded measured and consistent with prior plans, the move in Reece’s share price may be more sentiment driven than fundamental. If it hinted at slower branch economics or stickier cost inflation, that feeds directly into the main execution risk and the timing of any earnings recovery.
Reece consensus assumptions and valuation check
Reece's narrative projects A$11.0b revenue and A$437.1m earnings by 2029. This implies 5.4% yearly revenue growth and an earnings increase of about A$129m from A$308.2m today.
Uncover why Reece's fair value indicates a 12% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate angle to watch is margin pressure. The most cautious analysts already saw Reece’s 3.6% margin outlook and A$376.2m earnings forecast for 2029 as optimistic, given softer US housing and higher rates. Those estimates were set before the AGM and RBA decision, so you should expect views to shift as new information lands.
Explore 3 other Reece fair value estimates, including one that suggests as much as 24% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Reece research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Reece. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Reece's overall financial health at a glance.
Looking for more investment ideas beyond Reece?
If the Reece story has sharpened your focus on interest rates, balance sheets and execution risk, it can help to compare it with a broader set of companies that fit different brief, risk and income profiles.
- For potential mispriced opportunities with stronger fundamentals, check out a curated 3 high quality undervalued stocks that combine quality metrics with valuations that still look reasonable.
- If capital preservation matters more than chasing every upswing, consider a 6 resilient stocks with low risk scores that screens for resilient businesses with more defensive profiles.
- For investors hunting for stability and income, scan a 5 dividend fortresses that meet a higher yield hurdle while still passing basic financial health checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com