
How Investors Are Reacting To Integra LifeSciences Holdings (IART) Earnings Beat
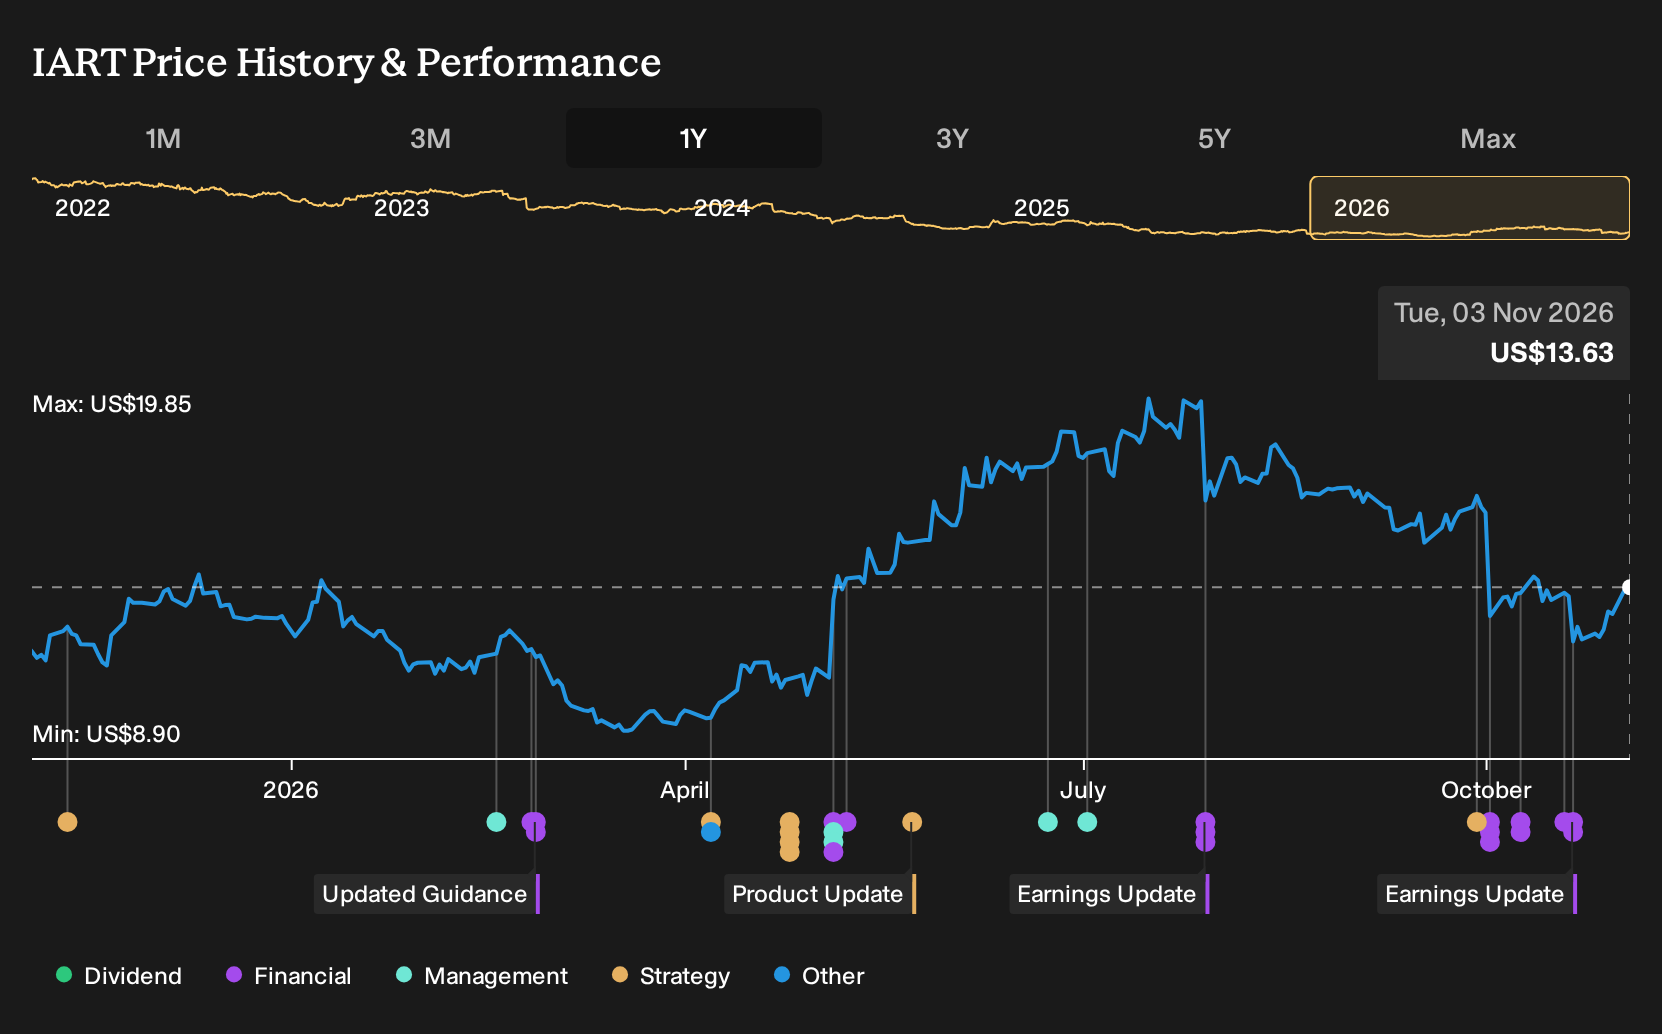
- Integra LifeSciences Holdings reported third quarter 2026 sales of US$411.18 million, net income of US$14.85 million and diluted earnings per share from continuing operations of US$0.19, marking a shift from a loss in the same period a year earlier.
- The company paired this return to profitability with cautious fourth quarter 2026 revenue guidance of US$413 million to US$433 million. It also continued to highlight its neurosurgery portfolio through education and hands-on training at the 2026 Congress of Neurological Surgeons Annual Meeting.
- Next, the focus turns to how Integra LifeSciences Holdings' improved third quarter profitability might reshape its existing investment narrative and risk balance.
Scan how Integra LifeSciences Holdings compares with other potential opportunities by reviewing a curated group of healthcare names screened for strong financials in our list of solid balance sheet and fundamentals (24 results).
Integra LifeSciences Holdings Investment Narrative Recap
To own Integra LifeSciences Holdings, you need to be comfortable with a turnround that leans heavily on cleaner execution in neurosurgery and tissue reconstruction, steadier supply and lower remediation spend. The third quarter swing back to profitability supports that thesis, although interest costs, leverage and prior one off items mean the earnings base is still rebuilding.
The key near term swing factor remains how smoothly product relaunches and manufacturing recoveries translate into margins while quality work and flood related remediation continue. Fourth quarter revenue guidance, which implies a reported decline, tempers expectations for a sharp top line inflection and keeps execution risk firmly in view.
The most relevant update for that thesis is Integra LifeSciences Holdings' fourth quarter 2026 revenue outlook of US$413 million to US$433 million, flagged as a reported decline of 5.2% to 0.5%. That range gives you a concrete yardstick for how quickly lost tissue and wound revenue might come back and how much operating leverage is realistic.
Paired with the third quarter return to profit, this guidance frames the near term trade off between rebuilding margins and absorbing ongoing quality, compliance and manufacturing costs. If revenue tracks the lower end while debt and interest remain heavy, the balance sheet constraint highlighted by analysts, where interest is not well covered by earnings, stays front of mind.
Integra LifeSciences Holdings' current analyst narrative points to revenues of US$1.8b and earnings of US$136.1 million by 2029, based on an assumed 2.0% yearly revenue growth rate. That profit outcome would represent an earnings increase of about US$123 million from US$13.0 million today.
Uncover why Integra LifeSciences Holdings' fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into Integra LifeSciences Holdings as a recovery story, not a repair job. Bullish analysts were modelling about 2.7% annual revenue growth and earnings of roughly US$152.5 million by 2029 before this third quarter profit and cautious fourth quarter guide, so their optimism may either strengthen or cool once they update those models. You can use that spread in opinions as a prompt to compare several scenarios, then decide which assumptions feel realistic to you.
Explore 2 other Integra LifeSciences Holdings fair value estimates, including one that suggests up to 68% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Integra LifeSciences Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Integra LifeSciences Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Integra LifeSciences Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Integra LifeSciences Holdings?
If Integra LifeSciences Holdings has sharpened your focus on quality and risk, you can use that same lens to scan a wider opportunity set with the Simply Wall St Screener. You can line up other businesses against the kind of balance sheet strength, cash flow durability and income potential that fit your own checklist.
- For investors who care most about downside protection and capital resilience, start with a 30 resilient stocks with low risk scores that aim to keep volatility and financial strain in check.
- If income is a priority and you want yields with staying power, scan a hand picked group of 4 dividend fortresses that focus on higher payout potential with an eye on stability.
- When you are hunting for quality that the market may be overlooking, broaden your watchlist with 19 high quality undiscovered gems that combine fundamentals with lower profile coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com