
Is Perimeter Solutions (PRM) Undervalued After Bullish Q3 Earnings Expectations?
Investors are watching Perimeter Solutions (PRM) closely this week as the company heads into its third quarter 2026 earnings report on November 5, following upbeat estimate revisions.
Recent trading has been choppy for Perimeter Solutions, with the share price up 3.97% over the past month but down 18.39% over the last 90 days, even as the 1 year total shareholder return sits at 18.18% and the 3 year total shareholder return is very large. This suggests earlier optimism is being reassessed ahead of earnings.
Scan how Perimeter Solutions compares with other materials stocks that may be setting up for the next move using our curated list of 34 high quality undervalued stocks.
Perimeter Solutions looks like a solid operator on paper, from fire retardants to specialty chemicals, yet the recent swing in returns raises a sharper question. Is that story already embedded in today’s US$28.54 share price, or not?
Most Popular Narrative: 31% Undervalued
On current numbers, the most followed narrative for Perimeter Solutions points to a fair value of $41.50 against a last close of $28.54, so the gap between price and that storyline is front and center as earnings approach.
Integration of MMT and IMS under a long duration ownership model, with targeted capital for new product development, productivity projects and add-on product line acquisitions, is aimed at lifting Specialty Products revenue and improving adjusted EBITDA margins.
Company wide use of value based pricing, productivity programs and vendor managed inventory solutions, such as for the DLA, is intended to offset input cost pressures and support net margin resilience while free cash flow benefits from higher contract backed utilization.
See why 3 investors see Perimeter Solutions as 31% undervalued.
That fair value anchor of $41.50 comes from a discounted cash flow style narrative that applies a 7.81% discount rate to analyst assumptions on revenue growth, profit margins and future earnings through to 2029, then compares the resulting value to where Perimeter Solutions trades today.
The story leans heavily on the idea that long term fire management contracts and Specialty Products integration work together to produce higher earnings power over time. This, in turn, is used to justify a future P/E multiple of 21.4x on projected 2029 earnings and to support the view that the current share price sits at a 31.2% discount to that fair value.
Result: Fair Value of $41.50 (UNDERVALUED)
Still, the Perimeter Solutions narrative depends heavily on long term fire management contracts and smooth MMT and IMS integration, and setbacks in either area could quickly challenge that 31% undervalued story.
Find out about the key risks to this Perimeter Solutions narrative.
Another View: Pricing Tension Around Perimeter Solutions
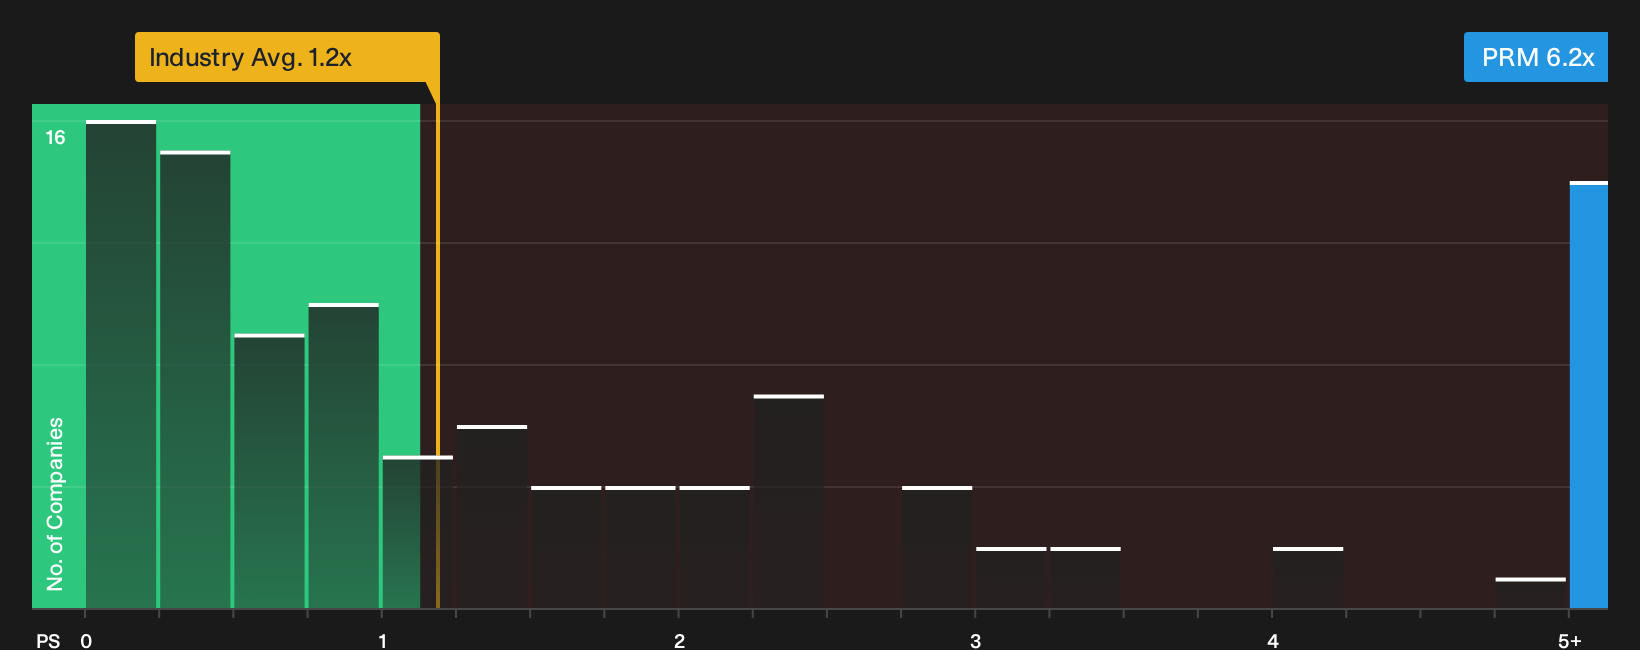
The story shifts once you look at what investors are actually paying for Perimeter Solutions today. On a P/S of 6.2x, the stock trades at more than 5x the US Chemicals industry average of 1.2x and well above the peer average of 2.4x, while the fair ratio sits lower again at 3.7x. That gap points to real valuation risk if expectations reset toward where the market typically prices this kind of business.
For a closer look at what that P/S gap could mean in practice, including how it compares with the fair ratio the market could move toward over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Perimeter Solutions is clearly mixed, which is exactly why the next move belongs to you and your own reading of the numbers. If you want to see what is driving the more optimistic angles around the story, take a closer look at the 3 key rewards.
Looking for more investment ideas beyond Perimeter Solutions?
If Perimeter Solutions has you thinking harder about valuation and risk, do not stop with a single ticker. Put a few contrasting ideas on your radar instead.
- Spot potential mispricings early and size up companies that may be trading below their fundamentals with the help of 34 high quality undervalued stocks.
- Strengthen the income side of your portfolio and compare stocks offering robust cash returns by scanning the market through 4 dividend fortresses.
- Shift attention to financial resilience and sort for businesses with cleaner balance sheets and sturdier fundamentals using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com