
3 Non China Memory Stocks Retail Investors Are Watching After Washington Export Control Risk
Washington is now weighing export controls against the pull of a potential US$45b to US$100b SK Hynix NAND project in upstate New York, and that crossroads is reshaping expectations across memory and packaging stocks far from Dalian. Policy risk is turning into a pricing risk. This piece walks through three US listed companies most exposed to that decision, and why their next chapter could matter for your portfolio.
The stocks highlighted below are only a small sample, and the full screen surfaced 60 more companies with equally compelling narratives that are not covered here. To identify and analyze potential high-conviction ideas that fit your own risk profile, head straight to the US-Listed Non-China NAND Memory and Packaging Stocks screener.
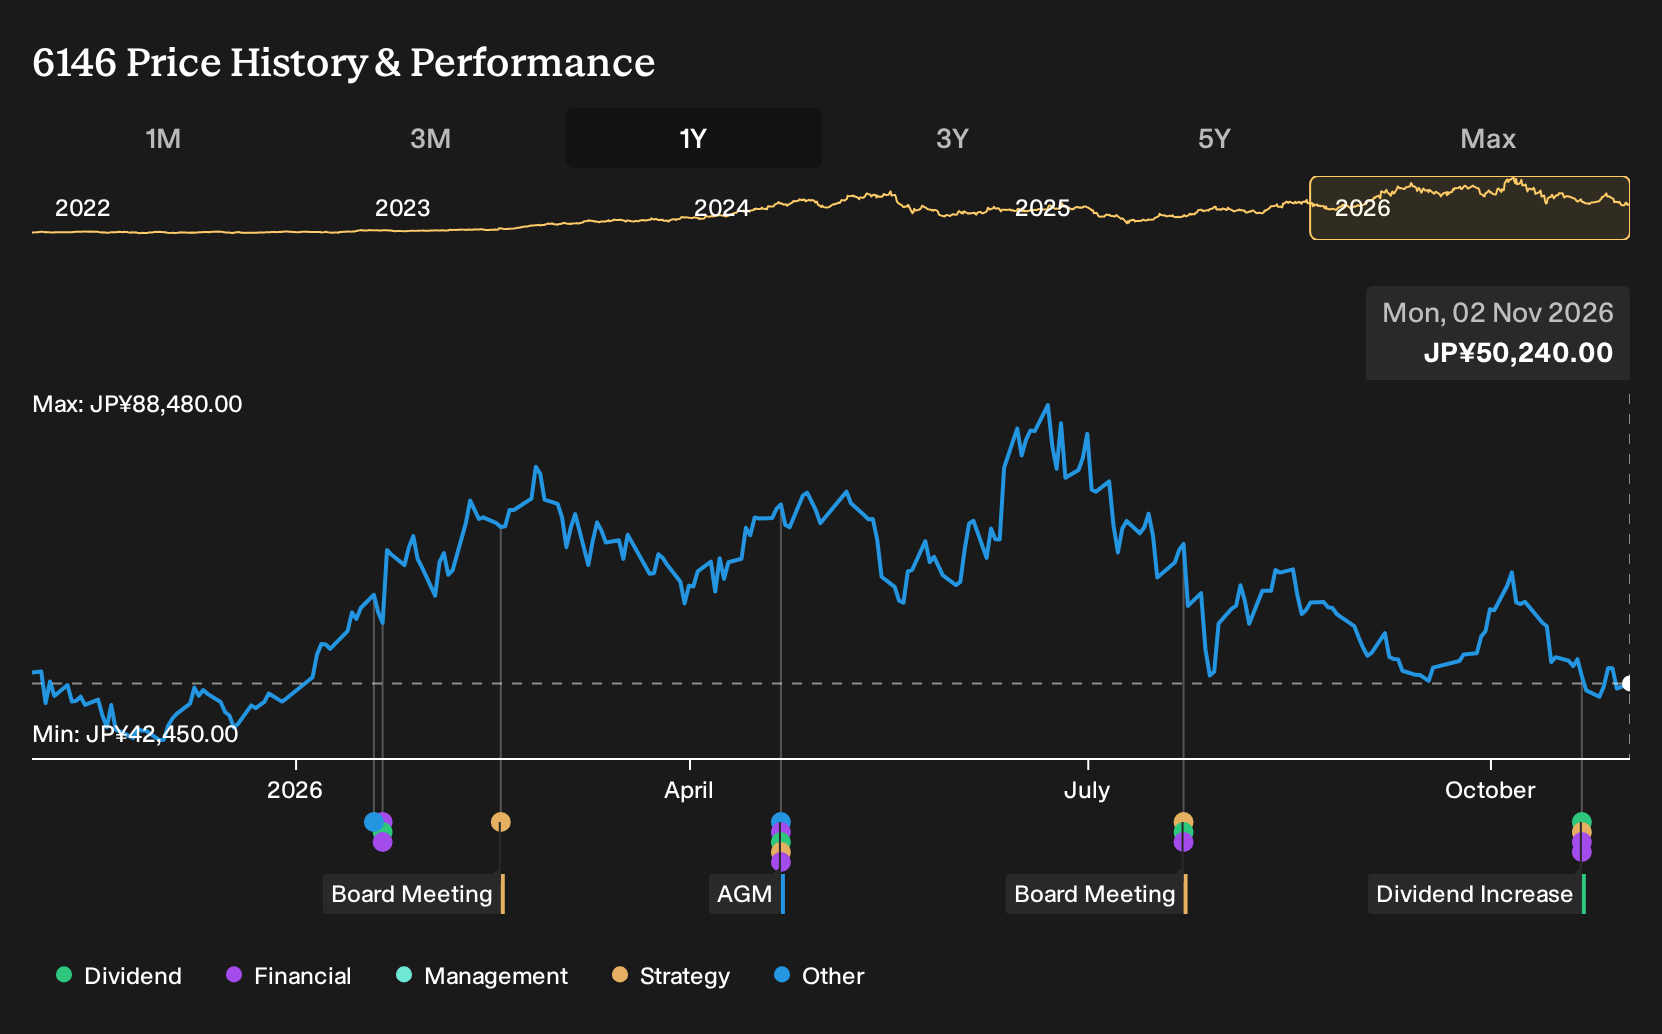
Disco (TSE:6146)
Overview: Disco Corporation supplies precision dicing, grinding, and polishing equipment and tools that chipmakers use to cut and finish semiconductor wafers.
Operations: Disco generates about ¥499,410 million from precision processing systems, including cutting, grinding, and polishing tools for semiconductor manufacturing.
Market Cap: ¥5,451.4 billion
Disco plugs into the screener theme as a key supplier of wafer dicing and grinding tools used in NAND and broader memory production outside mainland China. For investors focused on non China fabs, the appeal of that cash generation still depends on how one unseen pressure plays out.
That pressure point is exactly what makes the 2 key rewards and 1 important warning sign feel so useful right now, with Disco’s upside and fault lines laid out side by side.
Nanya Technology (TWSE:2408)
Overview: Nanya Technology manufactures and sells DRAM and other memory chips used in consumer electronics, data centers, mobile devices and cars.
Market Cap: NT$1.4 trillion
Nanya Technology appears in this US listed non China NAND and memory screen as a DRAM focused producer. Its global footprint gives you indirect exposure to storage pricing and supply outside mainland China at a time when Washington’s scrutiny of Chinese capacity is reshaping how buyers think about where they source critical memory.
"Nanya Technology is transitioning a larger share of its output toward AI infrastructure and server applications, with this segment already above 20% of revenue and targeted to reach 40% to 50% by 2029 to 2030, which could support revenue growth and help sustain margins as mix shifts to higher value products."
The relationship between capital spending and pricing power will play an important role in determining how durable those margins appear.
That mix question sits at the center of the story, and the full narrative for Nanya Technology explains how Nanya Technology’s AI push could affect volatility, capital needs, and potential upside.

Samsung Electro-Mechanics (KOSE:A009150)
Overview: Samsung Electro-Mechanics manufactures multilayer ceramic capacitors, package substrates, camera modules, and other electronic components used across global AI, server, mobile, and automotive hardware.
Operations: The business generates about ₩5.8b from Component products, ₩4.0b from Optics Solution, and ₩2.7b from Package Solution segments, selling mainly into China and broader export markets.
Market Cap: ₩81.4b
Samsung Electro-Mechanics matters for this screener because its package substrates and capacitors sit inside the servers and storage systems that memory makers are racing to build outside mainland China.
"AI server and data center customers are concentrating demand on high temperature, ultra high capacitance MLCCs and large area FCBGA substrates."
What happens to pricing and utilization if a single capacity decision in this tight corner of the supply chain breaks investors’ main assumption?
If that assumption is starting to feel fragile, read the full narrative for Samsung Electro-Mechanics to see how Samsung Electro-Mechanics could turn capacity swings into accelerating leverage on AI hardware demand.

Seeking Alternatives Before Momentum Flies
Fresh ideas often move first. Once momentum builds and prices start flying, the clean entry points can disappear quickly. Scan curated opportunities that are still under the radar and consider them early.
- Spot potential income opportunities by reviewing a curated pool of 28 dividend fortresses that focus on durability while yields stay elevated and investor attention is still catching up.
- Track early AI trends before they are widely followed by scanning 40 profitable AI stocks that aren't just burning cash where cash generation helps filter out stories that rely purely on hype.
- Explore companies involved in infrastructure projects by checking 42 power grid technology and infrastructure stocks while these enablers of electrification and grid upgrades remain less widely recognized.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com