
Republic Bancorp (RBCA.A) Posts Fresh Q3 Earnings, Is The Upside Already Priced In?
Republic Bancorp (RBCA.A) just posted its third quarter and nine month results to September 30, 2026, giving investors fresh numbers on lending income and profitability that can inform how the stock’s recent moves are viewed.
The quarterly update landed against a softer tape, with Republic Bancorp’s share price down 1.4% on the day and roughly 9% over the past three months, yet still up 34.1% year to date and supported by a 43.1% total shareholder return over the past 12 months.
Scan how Republic Bancorp compares with other banks that are showing resilient earnings trends and tight risk control across a hand picked 30 resilient stocks with low risk scores.
After a 34.1% jump this year and a 43.1% total return over twelve months, Republic Bancorp has already rewarded patience. The real question now is whether most of the upside has played out or is not yet fully priced in.
Preferred P/E of 13.8x: Is it justified?
On valuation, Republic Bancorp trades on a P/E of 13.8x, which sits below the peer average of 18.8x yet above the wider US banks sector at 11.3x. The market is assigning the stock a mixed message on earnings quality and durability.
The P/E multiple captures how many dollars investors are willing to pay today for each dollar of profit. For a lender like Republic Bancorp with a broad mix of traditional banking, warehouse lending and payment-related services, that ratio effectively compresses views on credit risk, fee income stability and management execution into a single figure.
That 13.8x level indicates that investors are not treating Republic Bancorp as a bargain bin regional bank. At the same time, the estimated fair P/E of 11.1x suggests the current earnings-based valuation sits above a level the market could move toward if sentiment or growth expectations cool.
Compared with the US banks industry average of 11.3x, the premium is clear. The stock trades richer than the sector and also above the estimated fair ratio of 11.1x. This points to the market pricing in stronger profitability or lower risk than a typical peer and leaves less room for disappointment if earnings or returns fall short of expectations.
Explore the SWS fair ratio for Republic Bancorp.
Result: Price-to-earnings of 13.8x (OVERVALUED).
Still, the story can change quickly if credit losses rise in core lending or if fee-based lines, such as tax refund and payment solutions, face regulatory setbacks.
Find out about the key risks to this Republic Bancorp narrative.
Another view on Republic Bancorp’s value
The picture changes once the SWS DCF model is brought in. On that approach, Republic Bancorp at $91.18 screens as undervalued against an estimated future cash flow value of $143.62, which implies the market is attaching a heavy discount to long term earnings power.
Investors now have two very different messages: one from the 13.8x P/E premium to the sector and another from the cash flow view. This raises a simple question: Which signal should matter more for your own risk tolerance and time horizon?
Look into how the SWS DCF model arrives at its fair value.
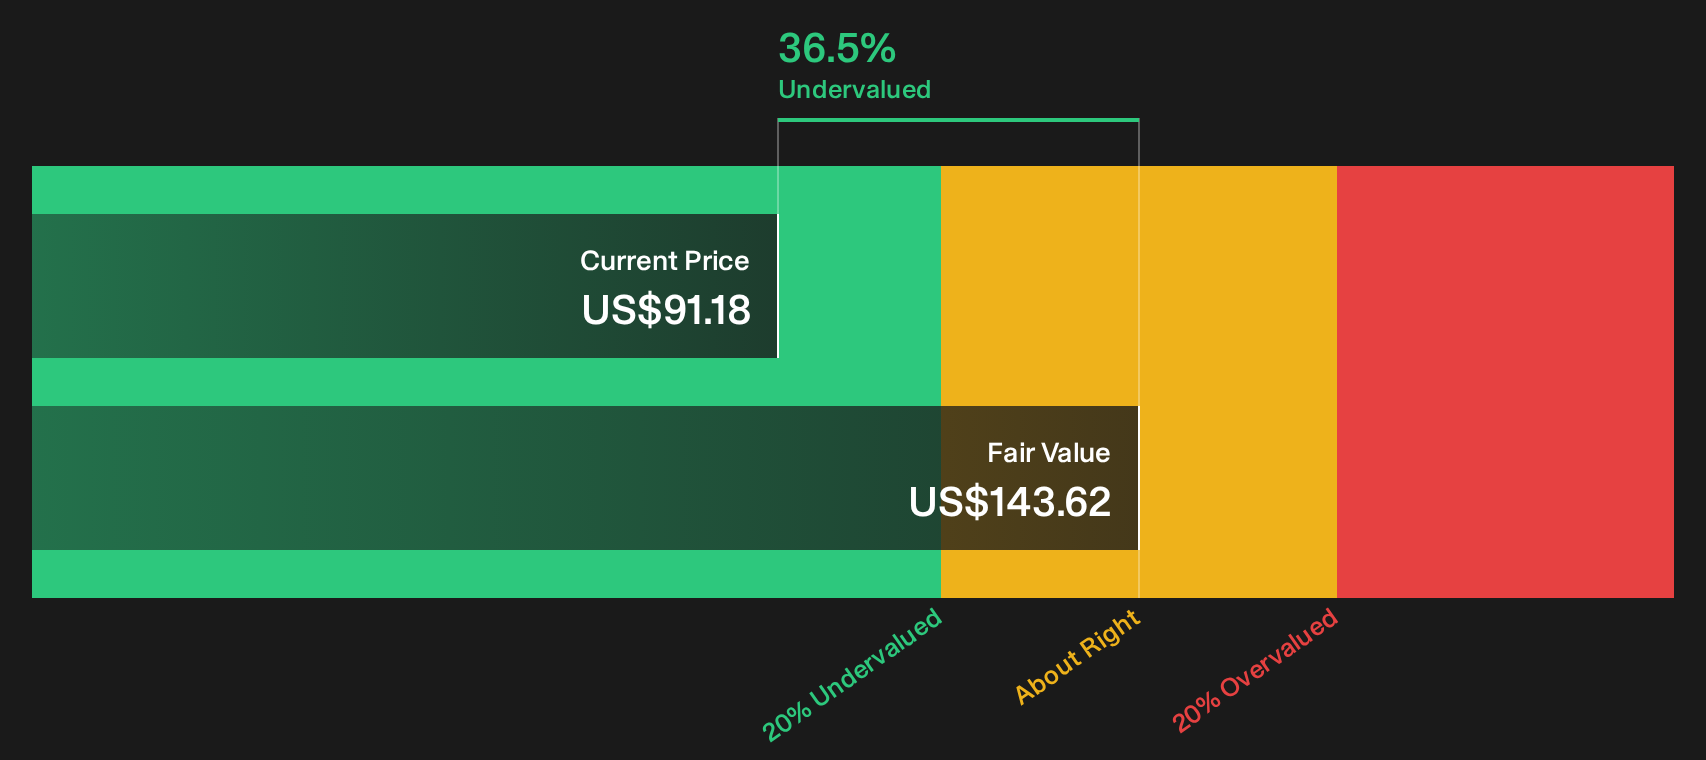
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Republic Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn between the P/E signal and the DCF gap on Republic Bancorp is reasonable. You can act on that tension by stress testing the data yourself, then checking the 4 key rewards
Looking for more investment ideas beyond Republic Bancorp?
If Republic Bancorp sharpened your focus on valuation and risk, do not stop there. Broader idea hunting can refine your watchlist and challenge your assumptions.
- Target quality at a discount by scanning companies that screen well on fundamentals and valuation through the 34 high quality undervalued stocks.
- Build a steadier income stream by reviewing dividend payers with stronger balance sheets using the 4 dividend fortresses.
- Strengthen your downside protection by filtering for businesses with healthier financial positions inside the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com