
Organic Revenue Growth Might Change Elementis Stock Narrative (LSE:ELM)
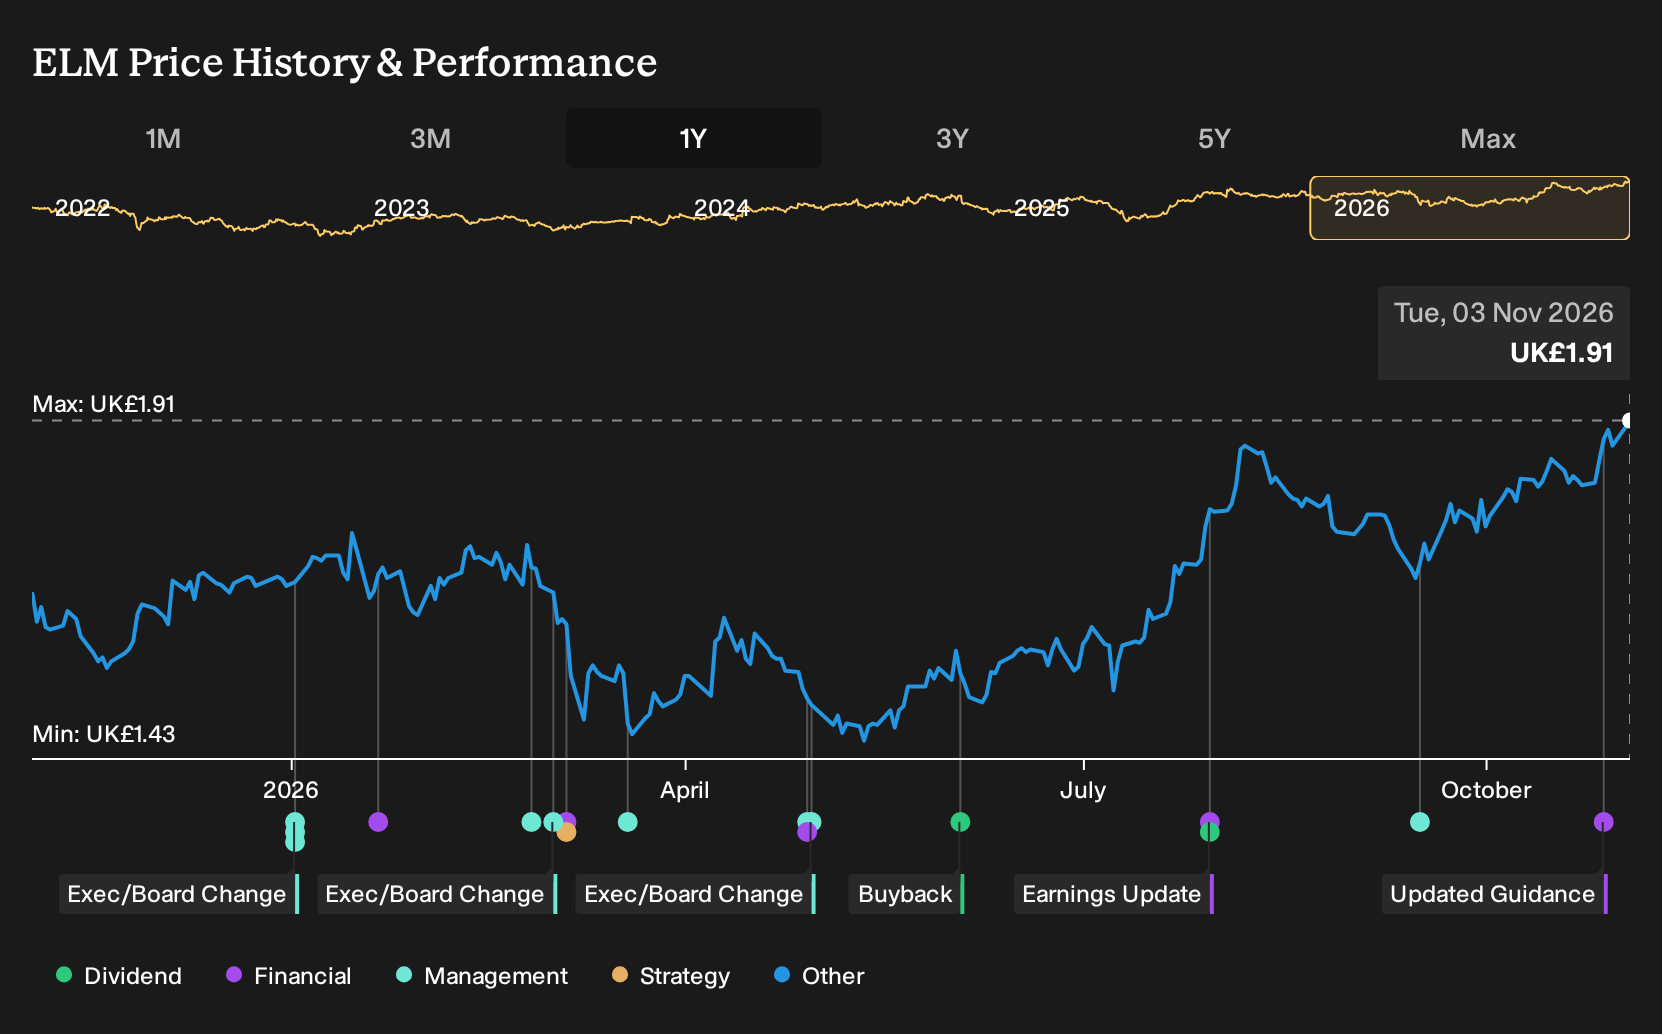
- Elementis reported revenue of $479 million for the nine months to 30 September 2026, with 7% organic constant currency growth supported by Personal Care, Asia, and improved Americas performance, and held a shareholder and analyst call to discuss the update.
- The guidance that fourth quarter revenue should be lower than the third quarter due to early order fulfilment highlights how timing effects and seasonality can meaningfully shift Elementis’ reported top line without necessarily changing underlying demand.
- We now examine how Elementis’ 7% organic revenue increase might influence the existing investment narrative that analysts have built.
Compare Elementis’ latest trading update with other specialty chemical and materials stocks that show similar demand patterns and seasonality using our hand picked list of solid balance sheet and fundamentals (10 results).
Elementis Investment Narrative Recap
To own Elementis, you need to be comfortable with a focused specialty additives story, where Personal Care and Coatings do most of the heavy lifting. The recent 7% organic constant currency revenue move to US$479 million backs up that thesis, but the near term catalyst remains proof that demand in Personal Care and Asia can stay firm without relying on early order timing.
The main short term risk still sits in concentration. After Talc and Chromium disposals, any slowdown or pricing pressure in core rheology modifiers or key geographies would hit harder. Current guidance that Q4 revenue will sit below Q3 looks mostly timing related, so the operating message is more about mix quality than headline growth.
The trading update on 28 October 2026 is the key announcement here. Elementis flagged 7% organic revenue growth for the first nine months, with support from Personal Care, momentum in Asia, and trends in the Americas that management described as better. For you, the moving pieces are end market mix, regional balance, and how much of the uplift comes from underlying demand rather than order phasing.
Management also reminded investors that Q4 should come in below Q3 because some customer orders were pulled forward. That comment matters for catalysts. It reduces the chance of misreading a softer Q4 as a demand crack. It also keeps focus on the bigger question, which is whether Elementis can continue to grow in targeted additives while managing the higher exposure that comes with a narrower portfolio.
Elementis’ current analyst narrative points to revenues of $652.3 million and earnings of $101.4 million by 2029, based on an assumed 1.4% yearly increase in sales and an earnings uplift of about 42% from $71.7 million today.
Uncover why Elementis' fair value indicates an 11% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster in a tight US$2.13 to US$2.36 band, which still reflects very different individual conviction levels. Since these numbers predate the October trading statement and new Q4 guidance, you should weigh them against concentration risks, R&D intensity, and Elementis’ exposure to trade sensitive Asian demand.
Explore another Elementis fair value estimate, including one that suggests as much as 23% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Elementis research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Elementis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elementis' overall financial health at a glance.
Looking For More Investment Ideas Beyond Elementis?
Once you have formed a view on Elementis, it can help to cross check that thesis against other businesses with different balance sheets, cash flow profiles, and payout policies. The Simply Wall St Screener lets you do exactly that in a structured way.
- If you want a shortlist of financially robust businesses, start with a list of solid balance sheet and fundamentals (10 results) that can help you focus on companies with stronger fundamentals and fewer balance sheet surprises.
- For readers who care most about valuation, use a 15 high quality undervalued stocks to find stocks that the model flags as high quality yet priced below their assessed worth.
- If income is your priority, a 4 dividend fortresses can guide you toward companies offering higher yields while still aiming to maintain resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com