
Did Buy Coverage Just Shift AngloGold Ashanti (AU) Investment Narrative?
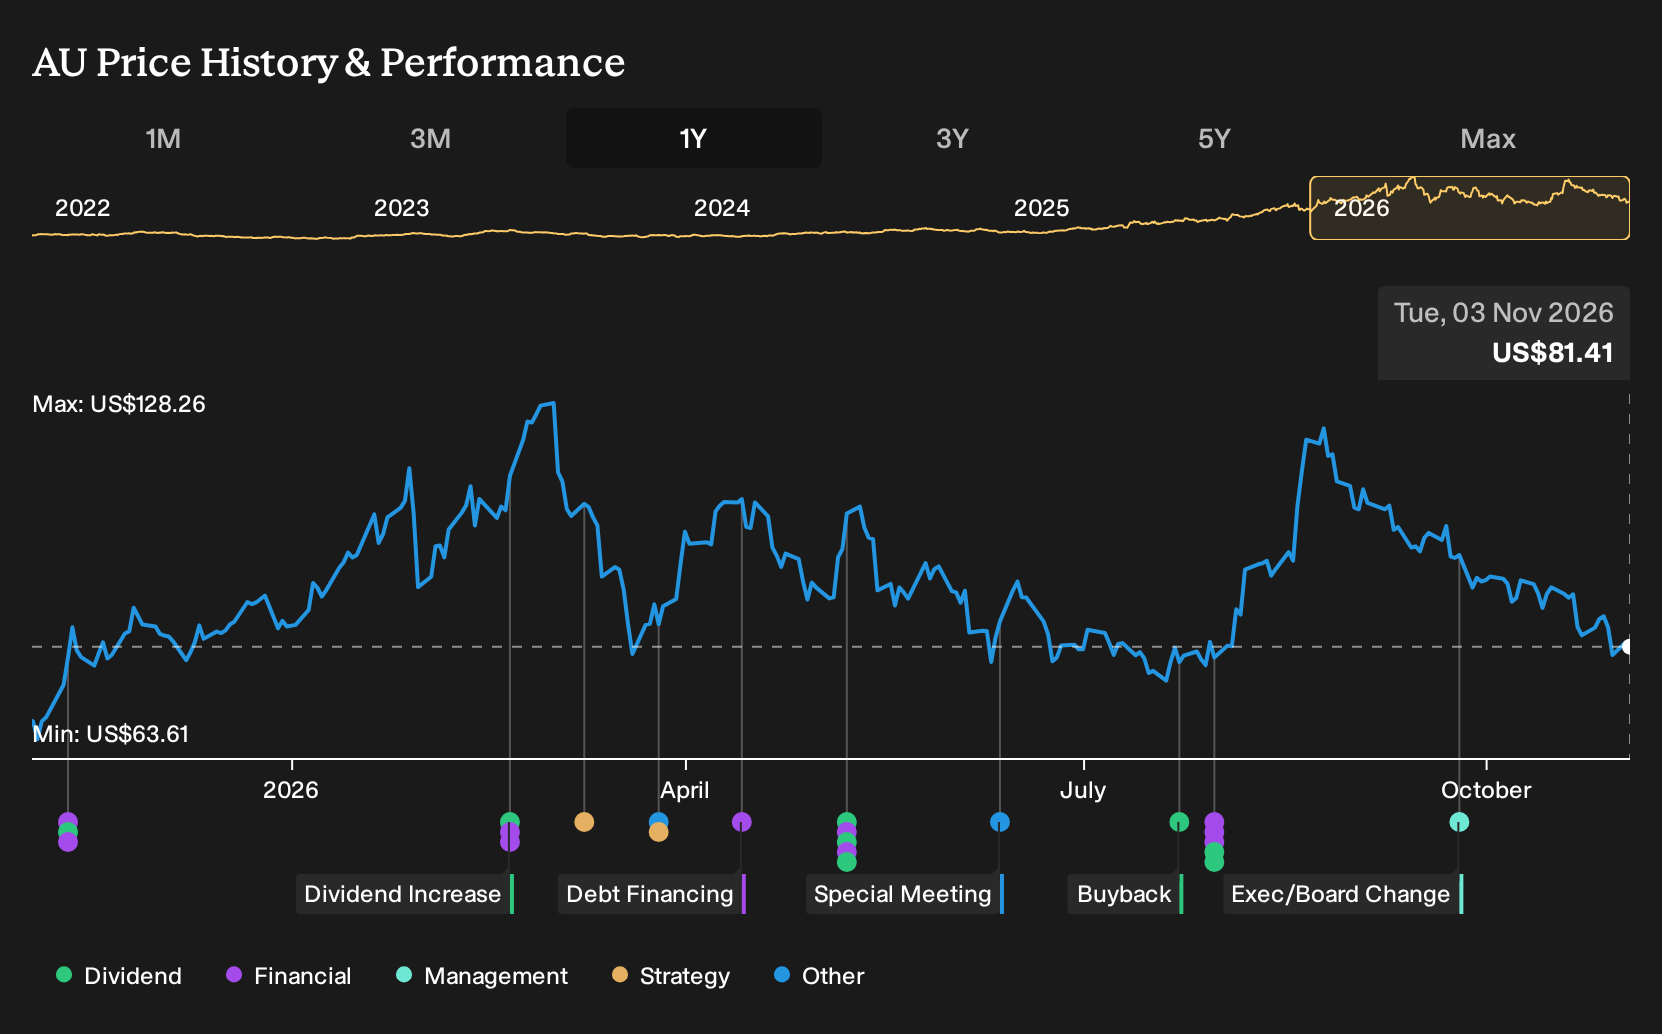
- AngloGold Ashanti recently drew fresh attention as TD Cowen began covering the miner with a Buy rating ahead of its third quarter 2026 results. These results follow a period marked by higher gold prices, the sale of the Serra Grande mine, a fatality at Obuasi and rising operating costs.
- The upcoming earnings release is expected to reflect how effectively AngloGold Ashanti managed production disruptions and cost inflation while maintaining exposure to firm gold pricing. New ETF inclusion and supportive analyst coverage are acting more as amplifiers of that operational story than the main driver.
- We will now look at how AngloGold Ashanti's investment narrative could be affected by the earnings outlook supported by firmer gold prices.
Scan beyond AngloGold Ashanti and see how other producers are lining up for potential moves in this cycle with our hand picked 34 elite gold producer stocks
AngloGold Ashanti Investment Narrative Recap
To own AngloGold Ashanti, you need to be comfortable with a pure play on gold production, where cost discipline and project delivery matter as much as the metal price. The key short term swing factor is how third quarter 2026 results balance firmer pricing against earlier production issues and higher operating costs. Rising total cash costs and all in sustaining costs remain the clearest pressure point on margins.
The biggest operational risk is that inflation, royalties and asset specific challenges at sites like Iduapriem and Siguiri keep eroding profitability just as expectations build into the print. If management shows progress on stabilising Obuasi and advancing growth projects in Nevada and Africa, the earnings release could support the existing longer term production and cash flow narrative.
The most relevant current development is the upcoming third quarter 2026 earnings report on 5 November, backed by an estimate that points to a 28.8% year on year earnings uplift supported by higher gold prices despite earlier production softness. This update will give you a clearer read on whether recent margin strength and high Return on Equity figures are holding.
For catalysts, that single print will show how AngloGold Ashanti is handling cost inflation, the impact of the Serra Grande sale and operational recovery after the Obuasi fatality. Analyst coverage and ETF inclusion, including the Wedbush ReturnOnLeadership US Large Cap ETF position, may influence sentiment around execution, but the real test sits in production delivery, cash costs and progress on the growth pipeline.
AngloGold Ashanti's current earnings are reported at $3.8b, with analysts forecasting consensus earnings of $4.9b by 2029. That implies an earnings increase of $1.1b and forecast revenues of $14.1b by that same year, which aligns with an assumed 6.1% yearly revenue growth rate over the next three years.
Uncover how AngloGold Ashanti's fair value indicates a 39% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on near term cost pressure and more on AngloGold Ashanti turning its Nevada hub and brownfield projects into a larger earnings engine. Before this TD Cowen news, the bullish camp was pencilling in about US$19.4b of revenue and US$6.3b of earnings by 2029. Those estimates and the fresh Buy initiation have not met yet, so treat this moment as a chance to compare sharply different views and decide which narrative you find more convincing.
Explore 4 other AngloGold Ashanti fair value estimates, including one that suggests as much as 71% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A useful starting point for your AngloGold Ashanti research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AngloGold Ashanti. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate AngloGold Ashanti's overall financial health at a glance.
Looking for more investment ideas beyond AngloGold Ashanti?
Once you have formed a view on AngloGold Ashanti, it can help to line it up against other opportunities with different risk and income profiles. The Simply Wall St Screener lets you quickly filter the market into focused shortlists that match your preferred style, whether you lean toward value, resilience or under the radar potential.
- If you want potential upside with strict quality filters, start with a carefully curated set of 19 high quality undiscovered gems that pair solid fundamentals with lower profile coverage.
- If capital preservation ranks higher for you than chasing every rally, narrow your search to a pool of 30 resilient stocks with low risk scores that screen well on balance sheet strength and volatility.
- If income is central to your plan, focus your watchlist on 4 dividend fortresses that combine higher yields with more resilient fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com