
Gartner (IT) Stock Could Be 32% Undervalued On Revenue Decline Fears
Gartner has seen its share price slide over recent years, which puts fresh focus on a simple question for investors: Do the cash flows that the business is expected to generate really support where the stock trades today?
- The share price has fallen 48.7% over the past 3 years, so a lot of earlier optimism around Gartner is now being tested against the durability of its cash generation.
- Recent earnings headlines have highlighted pressure on revenue and rising questions about competition from cheaper AI driven services, which can influence how dependable and growing Gartner's future cash flows look.
- If you'd rather focus on earnings, this one's for you. See what Gartner's 16.6x P/E says about the price.
For investors, the debate is whether Gartner's current market value is properly grounded in the cash flows its business is expected to produce over time.
If you want to evaluate this same cash flow question across a broader group of businesses exposed to AI and IT spending, consider comparing Gartner with 53 AI infrastructure stocks.
Does Gartner Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at the cash Gartner can generate for shareholders and then discounts it back to today. On the latest twelve month numbers, the firm produced free cash flow of about $1.28b, and the projections assume this pool of cash continues to grow from that base rather than shrink.
The 2 Stage Free Cash Flow to Equity approach uses a first phase of explicit forecasts, then tapers into a more mature second stage. This structure fits a business already generating over $1b of free cash flow. Despite Gartner lifting its 2026 guidance while the stock slid after concerns about revenue softness and cheaper AI rivals, the DCF projections put Gartner's estimated intrinsic value substantially above the current share price of $204.22. This gap suggests the market is treating recent revenue worries as more important than the cash generation profile implied by the DCF model. Find out what Gartner could be worth using our Discounted Cash Flow (DCF) estimate.
The Gartner Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Gartner leaves off and spell out which paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or materially less than it trades for today on the market.
Each narrative links its number to a clear view on where Gartner's expansion, profitability profile and key uncertainties might head next. This gives you a reference point you can test against as new information comes through.
Community views on Gartner are split between those who see the cash engine as underappreciated and those who think the current price already bakes in a lot of that story.
Bull case: 13% undervalued
"Expansion of Gartner’s Business & Technology Insights program, which has lifted the Insights library by 18% and increased higher impact research at a double digit rate…"
Discover why this Narrative puts Gartner at 13% undervalued.
Bear case: 5% overvalued
"The current valuation and management’s commitment to aggressive buybacks and free cash flow focus indicate that Gartner’s current share price already reflects expectations for resilient margins…"
Explore why this Narrative puts Gartner at 5% overvalued.
One more Gartner check that sits alongside the valuation work
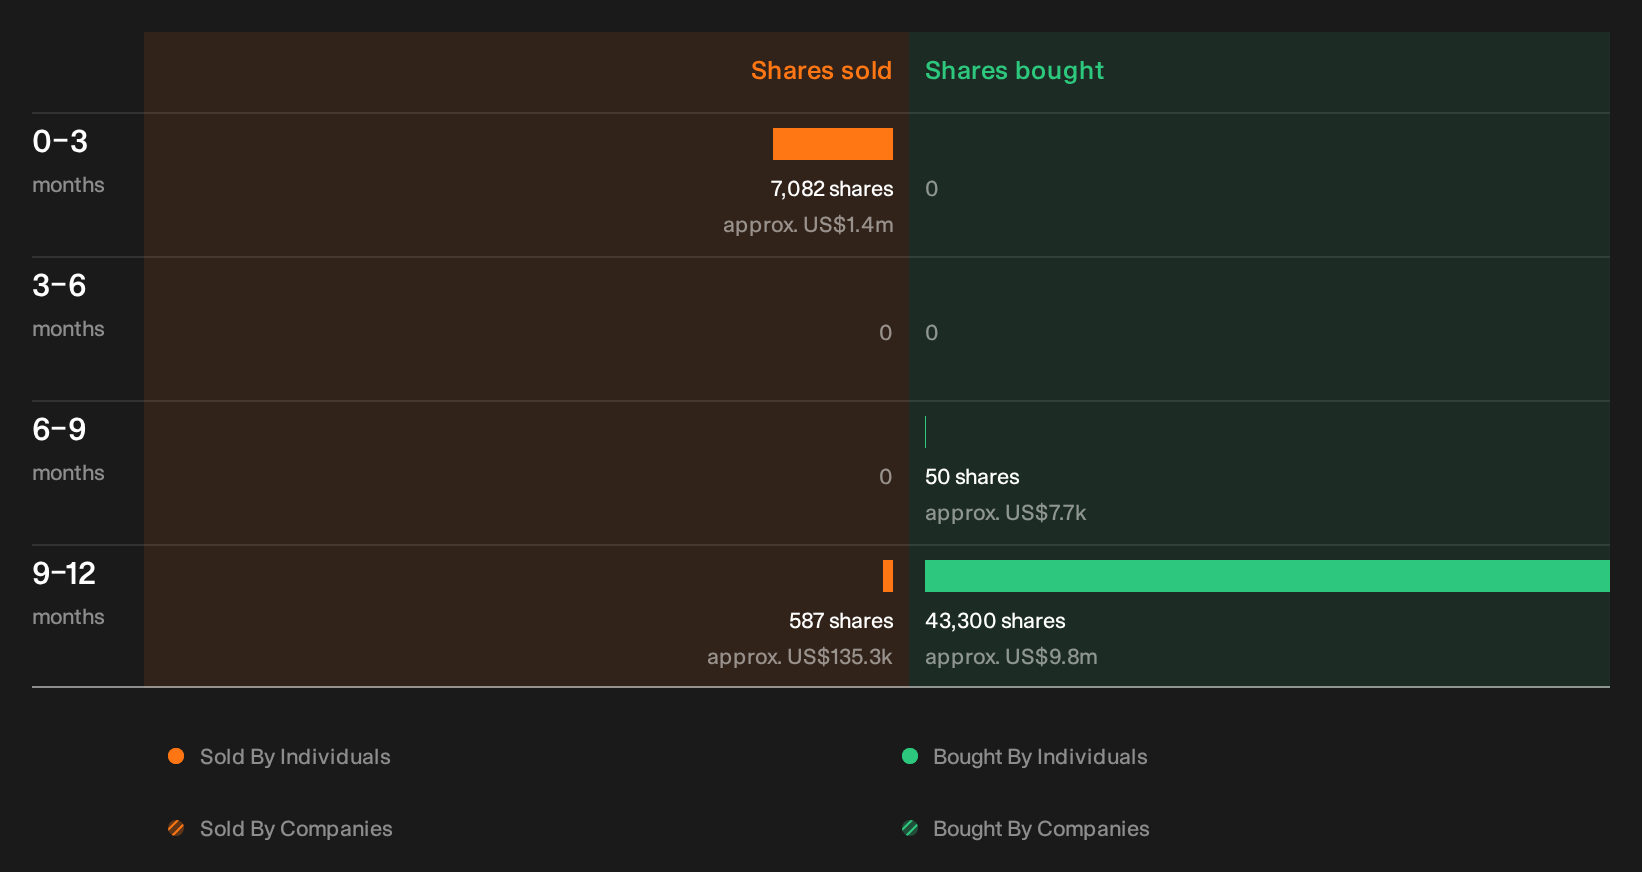
Price, cash generation and market debate are only part of the story for Gartner, because recent trading activity by company insiders can add another layer that readers may want to examine closely. See the recent insider selling flagged for Gartner.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com